分类: business

  • Saint Kitts and Nevis: Can It Become a Digital Finance Leader?

    Saint Kitts and Nevis: Can It Become a Digital Finance Leader?

    For small island nations, global economic leadership is often framed as a question of scale— but the twin-island federation of Saint Kitts and Nevis is rewriting that rulebook. With a population of fewer than 50,000 people, this Caribbean country has long built economic resilience through an outward-focused strategy, leaning into international tourism, cross-border financial services, and its popular citizenship-by-investment program to connect with global markets. Decades of membership in the Eastern Caribbean Currency Union have also delivered consistent monetary stability, laying strong groundwork for its next economic pivot: becoming a collaborative leader in regional digital finance.

    Unlike major global economies where fintech innovation emerges to solve the frictions of large domestic markets, Saint Kitts and Nevis faces a distinct challenge: its local consumer and business base is far too small to support a standalone, large-scale fintech ecosystem. Instead of competing head-to-head with established fintech hubs like Singapore, the United Kingdom, or Brazil, the federation has adopted a different strategic approach: positioning itself as a core connected node in a broader regional digital financial network, where collaboration trumps size.

    This strategy follows decades of deliberate economic transformation. Forty years ago, Saint Kitts and Nevis relied heavily on sugar production for its livelihood. Today, the economy is anchored by tourism, hospitality, real estate, and international financial services, with Basseterre, the capital on Saint Kitts, serving as the federation’s commercial and financial core. The country’s banking sector is led by major regional institutions including St. Kitts-Nevis-Anguilla National Bank, Republic Bank (EC), and CIBC Caribbean. Data from the International Monetary Fund puts Saint Kitts and Nevis’ GDP per capita above $25,000, making it one of the highest-income economies in the Caribbean on a per-person basis. As economic growth remains tightly tied to tourism, construction, and foreign investment, modern digital financial infrastructure and efficient cross-border digital payments have become critical to maintaining national competitiveness.

    For Caribbean fintech, regional integration has always mattered more than national boundaries, a reality Saint Kitts and Nevis has fully embraced. A fintech firm operating only within the federation would struggle to reach a viable customer base, so expansion across the Organisation of Eastern Caribbean States (OECS) and the broader Caribbean is not an option but a necessity. Fortunately, the country already shares integrated financial infrastructure with seven other Eastern Caribbean Currency Union (ECCU) members through the Eastern Caribbean Central Bank (ECCB), a regulator that has emerged as one of the most innovative central banks in the region. Long before many larger global jurisdictions prioritized digital financial innovation, the ECCB began advancing digital payments, expanding financial inclusion, and piloting central bank digital currency (CBDC) technology. For Saint Kitts and Nevis, this regional cooperation unlocks access to cutting-edge innovation that would be prohibitively expensive and complex to develop independently.

    The ECCB’s DCash initiative, the Eastern Caribbean CBDC, put the region on the global fintech map, and Saint Kitts and Nevis has been a core participating market. Launched as one of the world’s first retail CBDC pilot programs, DCash was designed to let individuals and businesses across participating ECCU countries make secure, low-cost digital payments using a digital form of the Eastern Caribbean dollar. The initiative drew global attention because it proved that small island economies could lead financial innovation, rather than only adopting technologies developed in large global markets. While the pilot experienced temporary technical outages that underscored the critical need for strong cybersecurity and system resilience, the experience has shaped the ECCB’s ongoing work to build robust public digital payment infrastructure across the region.

    While Saint Kitts and Nevis has not yet cultivated a large ecosystem of homegrown fintech unicorns, residents and businesses already have widespread access to advanced digital financial services through regional fintech players that operate across multiple Caribbean markets. One of the most prominent providers is WiPay, a Trinidad and Tobago-based fintech that offers online payment gateways, merchant acquiring, digital invoicing, and e-commerce payment solutions across the Caribbean, including Saint Kitts and Nevis. WiPay’s platform allows local hotels, retailers, and small and medium-sized enterprises (SMEs) to accept digital payments from both regional and international customers. Another key regional player is CaribPay, which delivers payment processing and digital payment solutions for businesses across the Eastern Caribbean, helping merchants modernize their payment acceptance without needing to build and maintain complex in-house technical infrastructure.

    Traditional financial institutions are also keeping pace with digital innovation. St. Kitts-Nevis-Anguilla National Bank has invested heavily in upgrading its mobile banking and online service offerings, while Republic Bank (EC) continues to expand its digital banking capabilities across the Eastern Caribbean. Today, these established banks compete as much on digital customer experience as they do on traditional branch network size, marking a major shift in how the sector operates. Rather than chasing the goal of producing dozens of domestic fintech startups, Saint Kitts and Nevis is focused on integrating deeply into a regional digital financial ecosystem where specialized providers serve multiple small island economies from a shared infrastructure base.

    A key competitive advantage for the federation as an international financial center is its robust, internationally aligned regulatory framework. Maintaining global investor confidence is one of the government’s top priorities, and policymakers have deliberately balanced support for fintech innovation with strong anti-money laundering (AML), counter-terrorist financing (CFT), and prudential regulation. The ECCB continues to modernize financial supervision across the entire currency union, and domestic regulators have strengthened oversight frameworks to align with leading international standards. Far from viewing strong regulation as a barrier to growth, policymakers recognize that clear, robust governance delivers the certainty investors and innovators need to operate. For a small international financial center, a reputation for transparency and compliance remains one of its most valuable economic assets.

    Looking ahead, trusted interoperable digital identity is emerging as the next frontier for digital transformation across the Eastern Caribbean, and Saint Kitts and Nevis is well positioned to benefit from regional progress in this area. While digital payments have improved dramatically across the region in recent years, broader digital economic growth depends on secure, cross-border recognized digital ID. A trusted digital identity system would simplify customer onboarding for financial services, cut compliance costs, and improve access to both banking and government services by eliminating repeated physical identity checks. For a region where citizens, businesses, and travelers cross national boundaries regularly, interoperable digital identity could prove just as transformative as interoperable digital payments. When paired with expanded e-government services, it could reduce administrative burdens, boost financial inclusion, and improve overall economic competitiveness.

    In the end, Saint Kitts and Nevis never aimed to build one of the world’s largest fintech sectors. Its strategic goal is far more aligned with its strengths: deepening regional integration through shared digital payment infrastructure, interoperable digital identity, and cross-border digital financial services. By leveraging innovative regional fintech providers and partnering with the ECCB on cutting-edge digital initiatives, the small federation is proving that small market size does not equal small influence. It is setting an example for other small open economies, showing how collaborative regional strategy can carve out a meaningful, influential role in the global digital finance landscape.
  • Aantal agrarische bedrijven  met 41 procent gegroeid

    Aantal agrarische bedrijven met 41 procent gegroeid

    Over a 17-year period ending in 2025, the total number of agricultural operations across Suriname has expanded by 41%, rising from 10,234 registered enterprises in 2008 to 14,409 as of last year, according to newly released official census data. Agriculture, Livestock and Fisheries Minister Mike Noersalim framed the sharp growth as clear evidence of the agri-food sector’s enduring vitality and outsized importance to Suriname’s national economy.

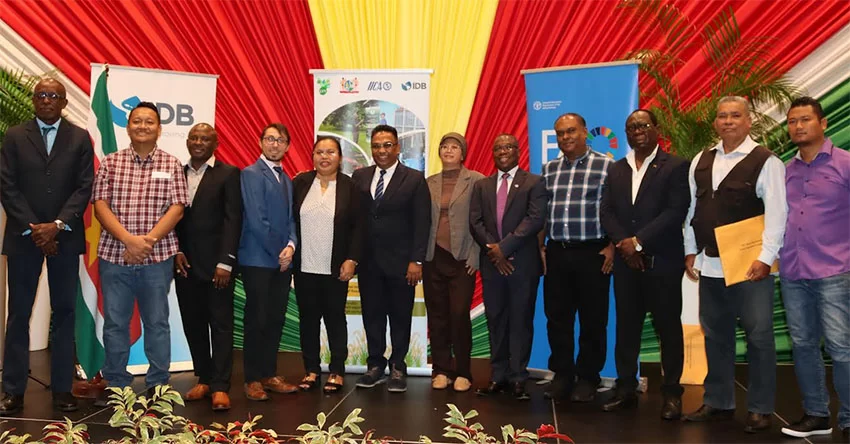
    Minister Noersalim unveiled the full findings of the 2026 Agricultural Census Statistical Report at an official launch event held Friday in Torarica. Beyond tracking the overall growth in farm numbers, the comprehensive national census also delivers granular insights into the age demographics of farming professionals across different regions of the country, revealing stark geographic divides in generational composition.

    Data from the report shows that aging workforces are a pressing challenge for the commercial agricultural sector concentrated in Suriname’s coastal districts. The capital district of Paramaribo stands out with the highest average farmer age across the nation, at 56.5 years old. In contrast, inland districts including Brokopondo and Marowijne report far younger average demographics among active agricultural workers, creating a sharp contrast with coastal aging trends.

    For Minister Noersalim, the census data does more than document the current state of Suriname’s agriculture sector—it also maps out clear priorities for future policy intervention to support sustainable long-term growth. To build on the rising number of agricultural enterprises, the Ministry of Agriculture, Livestock and Fisheries (LVV) is prioritizing expanded access to affordable capital for producers. The ministry is pushing to broaden credit access through the National Development Bank of Suriname (NOB), a change that would allow both new entry-level farmers and established operations to secure capital more easily to scale up their activities.

    Alongside financial reform, the ministry is also launching targeted initiatives to attract more young people to pursue professional, modern careers in agriculture, with the goal of accelerating generational turnover in aging regional sectors. To achieve this, LVV is strengthening strategic partnerships with domestic education institutions. “We are building out collaborative academic ties with training and higher education providers including ADEK, PTC and USTI, while also holding targeted outreach sessions at the primary school level to spark early interest in agricultural careers,” Noersalim explained in his launch address.

    The national agricultural census initiative was made possible in part by financial backing from the Inter-American Development Bank (IDB), with technical and expert support provided by the Food and Agriculture Organization of the United Nations (FAO) and the Inter-American Institute for Cooperation on Agriculture (IICA). Noersalim extended gratitude to the thousands of Surinamese farmers who shared their data and on-the-ground experience with census researchers, as well as project lead Sheila Aldjah and the full team of field enumerators, administrative staff, and ICT specialists who delivered the final report.

    Minister Noersalim emphasized that the completion of the census and publication of the report marks a starting point, not an end point, for sector-wide improvement. He noted that the detailed demographic and sector data will now serve as a foundation for evidence-based policy development and targeted, actionable reforms for Suriname’s agriculture industry. “The counting work is finished, but our shared mission begins today,” Noersalim said. “Let us turn these numbers into decisive action, into sustainable growth, and into a resilient, youth-driven agricultural sector that future generations can build on with pride.”

  • BIG ENERGY PLANS

    BIG ENERGY PLANS

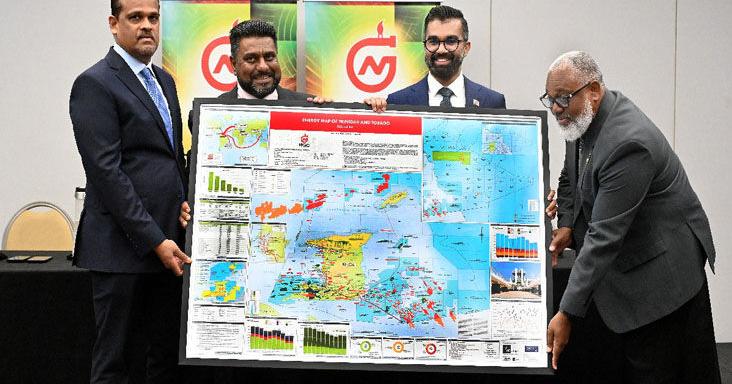
    Trinidad and Tobago’s energy sector is poised for major updates in the coming days, with Prime Minister Kamla Persad-Bissessar scheduled to unveil new national energy initiatives, National Gas Company (NGC) chairman Gerald Ramdeen has confirmed. Ramdeen shared the announcement following a formal land transfer ceremony held at Port of Spain’s Hyatt Regency on Wednesday, where NGC secured permanent freehold title to the land hosting its critical Beachfield gas processing facility in Guayaguayare.

    Over the past two months, Ramdeen explained, NGC has worked closely with the Ministry of Energy and international upstream energy partners to develop new initiatives designed to unlock greater economic returns for Trinidad and Tobago’s people. While he declined to preview specific details of the coming announcements, noting that the Prime Minister would lead the official reveal, Ramdeen confirmed that major progress has also been achieved at the Point Lisas Industrial Estate, where NGC is collaborating with existing downstream operators including global agribusiness firm Nutrien and prospective first-time investors interested in entering the Trinidad and Tobago market. “Companies that have never operated here before are now ready, willing and able to commit capital to projects on the estate,” Ramdeen said, adding that the upcoming announcements will underscore the current administration’s focus on delivering tangible progress in the energy sector, which forms the backbone of the country’s economy.

    The formal vesting of the Beachfield land title, completed by Commissioner of State Lands at Wednesday’s ceremony, resolves a 20-year-old ambiguity over land occupation that dates back to the facility’s original construction and commissioning by British Gas between 2004 and 2006. Ramdeen noted that a long-standing structural issue had left NGC managing many of the country’s most strategic energy assets, including the Beachfield plant and the Port of Galeota, without holding formal legal title to the underlying land – an arrangement he described as fundamentally untenable. The resolution of this issue, he emphasized, was made possible by the targeted work of Minister of Land and Legal Affairs Saddam Hosein and his team.

    Critically, the formalization of land ownership clears the final regulatory barrier for the development of the Manatee natural gas project, a joint venture between NGC and Shell Trinidad. The Beachfield facility is earmarked to serve as the core onshore infrastructure for processing gas extracted from the Manatee field, and the new land title grants all necessary authorizations for planned facility upgrades and expansion works to support the project.

    Ramdeen framed the land transfer as a model of collaborative governance, bringing together the Ministry of Land and Legal Affairs, the Office of the Commissioner of State Lands and NGC to resolve a decades-long backlog issue. “By closing out an outstanding matter that has lingered for over 20 years, NGC’s current leadership has reinforced just how critical good governance, disciplined stewardship of state assets and cross-agency partnerships are to advancing Trinidad and Tobago’s long-term energy security,” he said.

    Minister Hosein echoed that sentiment, noting that his department’s work to formalize NGC’s land ownership directly supports the country’s broader energy goals. “The Ministry of Land and Legal Affairs is proud to have played a critical part in advancing and securing the country’s energy sector,” Hosein said. “We stand ready to continue supporting NGC through efficient, transparent legal and administrative processes to create the certainty needed for strategic projects like Manatee to move forward without delay. This milestone is proof of our shared commitment to delivering long-term, sustainable value for all the people of Trinidad and Tobago.”

    NGC acting president Edmund Subyran added that the land title approval removes all remaining roadblocks for the joint Manatee project with Shell. “This achievement represents more than just a transfer of land. It is the culmination of dedicated work from all parties who remained focused on getting the right outcome for the country,” Subyran said. “With these approvals now in place, NGC and Shell can move forward immediately with the facility upgrades needed to support the Manatee project, while also strengthening NGC’s operational capabilities to maintain a reliable domestic gas supply for Trinidad and Tobago.”

    Ramdeen added that the upcoming announcements from the Prime Minister will highlight the government’s progress in unlocking the full economic value of the country’s natural resource reserves. “What the people of this country and the broader region will see is the actual monetization of our natural gas molecules, which will deliver tangible new revenue streams to benefit all citizens of Trinidad and Tobago,” he said, adding that the public will be “very proud” of the work the administration has completed to advance the sector.

  • Corporate tax windfall raises urgency for faster reforms

    Corporate tax windfall raises urgency for faster reforms

    Barbados has recorded a windfall of more than $150 million in additional corporate tax revenue following the implementation of landmark global tax reforms, but industry leaders are sounding a warning that the Caribbean nation risks losing international companies to more operationally efficient jurisdictions unless it accelerates public sector modernization.

    The new tax regime, which includes the Qualified Domestic Minimum Top-up Tax paired with the OECD-led Pillar Two framework, sets a 15% effective minimum tax for large multinational enterprises and a 9% rate for domestic companies. Introduced to bring Barbados’ tax code in line with global standards and defend its domestic corporate tax base, the reform has already delivered a substantial infusion into the island’s public coffers, data from the Central Bank of Barbados confirms. The Mia Mottley-led administration plans to direct the extra revenue toward strengthening social safety nets, expanding regulatory capacity, and delivering direct economic relief to local citizens.

    However, the unexpected revenue boost has reignited debates over Barbados’ long-term competitiveness as an international business hub, with observers questioning whether higher tax rates will erode the island’s long-standing appeal to global corporations. Carmel Haynes, executive director of the Barbados International Business Association (BIBA), told reporters that while the tax overhaul initially triggered unease across the offshore business sector, overall investor confidence has held up better than early forecasts predicted. “Early projections of a mass exodus of foreign capital simply did not come to pass,” Haynes noted. “While there have been some companies that chose to relocate, we continue to see new business incorporations, so it would be wrong to write off Barbados’ attractiveness at this stage.”

    Central Bank data backs this assessment: after an initial uptick in non-renewals of foreign currency permits when the reform was first rolled out, renewal rates have since stabilized, and the island’s largest corporate taxpayers have opted to retain their local operations. “We have not seen a mass departure of firms over the 9% domestic rate,” Haynes said. “The fact that major taxpayers are still here and meeting their new higher tax obligations signals solid confidence in the market.”

    The impact of the new regime has been uneven across different industry segments. Highly mobile corporate structures set up primarily for tax minimization have faced the most pressure to relocate, but core sectors where Barbados holds established global market share have seen little disruption. Notably, the captive insurance industry, where Barbados ranks among the world’s top five domiciles alongside Bermuda, the Cayman Islands, and Delaware, has remained largely stable.

    Haynes pointed out that many multinationals choose Barbados for strategic advantages that go far beyond base tax rates, including the island’s extensive network of double taxation treaties that offer unique legal protections for firms operating in complex regional markets like Cuba and Venezuela. Now that the 15% global minimum tax has leveled the playing field across all participating jurisdictions, Barbados still retains key competitive edges over its Caribbean peers: administrative and corporate setup costs remain significantly lower than in higher-cost hubs like Bermuda and the Cayman Islands, and the island has long marketed itself as having a highly educated professional workforce that keeps labor costs stable while meeting global regulatory substance requirements. This skilled talent pool is paired with decades of regulatory stability and legal predictability, factors that continue to reassure long-term foreign investors.

    Even with these inherent strengths, BIBA is urging the government not to take existing investor loyalty for granted. With tax rate differences largely eliminated by OECD rules, non-tax factors — particularly administrative efficiency and speed of service delivery — have become the most critical differentiator for competing international business hubs. The association is calling on the Mottley administration to reinvest the new tax revenue directly into public service modernization, cutting bureaucratic red tape, and advancing long-delayed digital transformation projects. A top priority is full digitization of the Corporate Affairs and Intellectual Property Office (CAIPO), with local businesses calling for faster company registration processing, automated cross-agency data sharing to cut redundant paperwork, and legal recognition of digital signatures for corporate transactions.

    “When companies know their applications will be processed quickly, their questions answered and their needs met efficiently, we will outcompete other jurisdictions,” Haynes said. “We cannot rest on our past successes. We cannot assume companies currently operating here will stay indefinitely. We have to meet their modern needs and prove we want their business by delivering the highest quality services possible.” While some government agencies including Business Barbados and the Financial Services Commission have already started expanding staffing to improve service, Haynes warned that the pace of reform needs to accelerate sharply to avoid frustrating investors. “If companies get fed up with delays and leave, the damage will already be done,” she said.

    Looking ahead, long-term uncertainty around the global Pillar Two framework remains, driven by shifting geopolitical dynamics. The United States has not yet formally adopted the regime, facing growing domestic political pushback against global tax mandates, leaving open questions about whether the 15% minimum tax will remain intact over the next decade. “Geopolitical shifts could change the long-term trajectory of the global minimum tax regime,” Haynes noted. “It is still too early to tell if this framework is permanent, so we cannot yet know what its ultimate impact on Barbados will be.”

  • Inside Saint Lucia’s latest CIP report: $402.2m generated in 2024/25

    Inside Saint Lucia’s latest CIP report: $402.2m generated in 2024/25

    Saint Lucia’s flagship Citizenship by Investment (CBI) Programme generated a total of EC$402.2 million (equivalent to US$148.8 million) in revenue for the 2024/25 financial year, marking a strong financial performance even as regional CBI schemes face mounting international pressure, according to the programme’s newly released annual report.

    The official report, which was presented to the country’s Parliament in April, outlines both the substantial economic benefits the scheme delivers to Saint Lucia and the escalating regulatory and diplomatic challenges it confronts. Across the Caribbean, citizenship-by-investment initiatives have come under growing scrutiny from Western global partners in recent months. The United Kingdom has already implemented stricter visa requirements for Saint Lucian passport holders, while the European Union has ramped up pressure on Caribbean nations running similar programmes, demanding they wind down these schemes entirely by 2028.

    An analysis of the report by local outlet St. Lucia Times reveals key operational shifts designed to address international concerns while maintaining the programme’s financial output. For the 12-month period ending March 31, 2025, the CBI Unit received 2,957 new applications. Of these, 2,278 applications gained final approval, while 355 were rejected outright.

    While the total number of new incoming applications dropped compared to the 2023/24 financial year, the unit dramatically increased its total processing volume: it completed work on 2,633 applications in 2024/25, a sharp rise from just 1,248 processed applications the previous year. Officials say this jump reflects a targeted push to clear existing backlogs and streamline workflow to match ongoing applicant demand.

    One of the most significant operational changes highlighted in the report is the marked increase in application refusals. This year’s 355 denials represent a more than fourfold increase from the 77 refusals recorded in 2023/24. While the report does not publish case-by-case reasoning for rejections, it repeatedly attributes the rise to enhanced compliance frameworks, upgraded due diligence processes, and stricter applicant vetting protocols rolled out over the past year. These strengthened safeguards have been prioritized as the entire Caribbean CBI sector faces closer international examination.

    On the financial front, the programme continues to deliver major injections into Saint Lucia’s public finances. The report confirms that EC$86 million in surplus revenue from the CBI Unit was transferred directly to the national government this year. When combined with contributions to the National Economic Fund and proceeds from bond investments linked to the programme, total government revenue from the CBI initiative reached EC$141.8 million. These funds are allocated to critical public projects across healthcare, education, infrastructure, community development, and other core public services.

    The CBI Programme itself ended the financial year with a surplus of EC$145.5 million, and its cash reserves grew to EC$261 million, up from EC$146 million at the end of the 2023/24 period. Over the longer term, the report documents explosive growth of the programme since its early days: annual applications rose from just 36 in the 2016/17 financial year to nearly 3,000 in the latest reporting period, hitting a peak of 5,642 applications in 2023/24. Even with a dip in new applications this year, the higher processing volume confirms the unit’s commitment to reducing backlogs while upholding stricter oversight standards.

    In his introductory overview of the report, Deputy Prime Minister Dr Ernest Hilaire, who has direct oversight of the CBI Programme, emphasized that the scheme serves as a critical economic buffer for the island nation, noting it “supports the country in moments of economic uncertainty”. Acting Chairman Julian Charles praised the unit’s work, calling its 2024/25 results an “exceptional performance”, highlighting that total revenue rose 67 percent compared to the previous financial year.

    Looking ahead, the report announces plans for further reforms to solidify the programme’s standing amid growing international scrutiny. Upcoming changes include strengthening national legislation governing the scheme, improving internal governance structures, and building greater international confidence in Saint Lucia’s CBI framework.

  • Beneficial ownership law ‘aims to streamline compliance’

    Beneficial ownership law ‘aims to streamline compliance’

    Barbados has enacted a landmark beneficial ownership reform bill that will consolidate existing regulatory data instead of imposing new reporting requirements on local businesses, according to senior government Senator Lisa Cummins. Speaking during Wednesday’s Senate debate, the leader of government business in the chamber framed the new legislation as a transformative step that simultaneously eases regulatory burdens for legitimate enterprises and reinforces the Caribbean nation’s standing as a transparent, credible global financial hub.

    Contrary to concerns that the law would require businesses to submit extra paperwork, Cummins clarified that the reform only overhauls how existing beneficial ownership information is collected and organized. For years, relevant data on ultimate business owners has already been gathered by multiple domestic regulators, including the Central Bank of Barbados, the Financial Services Commission, and other sector-specific oversight bodies. This information has long been required as part of routine regulatory processes, from initial license applications and changes in major shareholding structures to ongoing supervisory reviews, fit-and-proper person assessments, and enforcement compliance checks.

    Currently, competent domestic authorities already share this collected data with international partners under bilateral and multilateral treaties that Barbados has signed onto. The information already supports a wide range of critical activities, including criminal probes, anti-money laundering operations, terrorist financing investigations, regulatory audits, sanctions enforcement, and other law enforcement initiatives, with the country’s Financial Intelligence Unit leading much of this investigative work, Cummins added.

    A key structural change outlined in the legislation is the restructuring of the former International Business Unit, whose duties have been split between two existing and new entities: the Tax Policy Unit under the Ministry of Finance, and the newly created Business Compliance Unit, known as BCOM. Under the new framework, BCOM will be tasked with maintaining a centralized national beneficial ownership register. This single centralized system will allow businesses to submit required information just one time, eliminating the redundant practice of providing identical data to multiple separate regulatory agencies.

    “What the legislation actually sets out to do is to simplify and create coherence around the collection of business data for all businesses under the beneficial ownership regime,” Cummins explained. “That unit [BCOM] is now going to take responsibility for collating in a single place all of the information with one single submission by businesses.”

    Cummins emphasized that the reform is a critical step to protect Barbados’ financial system and preserve its positive standing with global regulatory partners. “We want to make sure that Barbados cannot be used as a jurisdiction to hide dirty money,” she said. The new law uses a tiered regulatory approach that strengthens necessary safeguards against money laundering and terrorist financing, while cutting unnecessary red tape for law-abiding businesses, she added. This, in turn, will protect Barbadian businesses’ continued access to the global financial system.

    The reform positions Barbados as a jurisdiction that proactively modernizes, upgrades, and transforms its international financial sector through consistent, transparent regulatory practice, Cummins told the Senate, capping the debate on the bipartisan-backed reform.

  • Column: Banken zetten met hogere ATM-tarieven digitale economie op achterstand

    Column: Banken zetten met hogere ATM-tarieven digitale economie op achterstand

    For years, Suriname has laid out a clear national goal: transitioning to a modern, fully digital economy. The country’s commercial banks have poured resources into developing new electronic payment platforms, the Central Bank has actively promoted non-cash transaction circulation, and public outreach campaigns have repeatedly encouraged Surinamese society to reduce its reliance on physical cash. This trajectory makes solid economic sense: cutting cash usage brings a long list of public and private benefits, from improved financial security and greater transaction transparency to lower logistics costs for cash transport and more efficient overall payment processing.

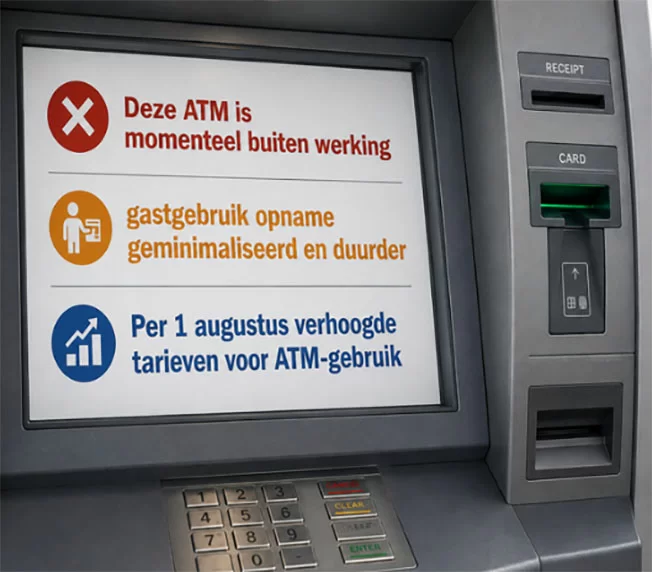
    It is for this very reason that local banks’ recent decision to once again raise user fees for automated teller machine (ATM) transactions stands as a puzzling, counterproductive step that runs directly against the nation’s digitalization ambition. The issue is not whether ATM operating costs justify price adjustments — maintaining, securing and managing a nationwide ATM network does require consistent capital investment. The core problem is that this policy misaligns with the broader goal of moving Suriname toward a less cash-reliant financial system.

    Human behavior is inherently shaped by financial incentives, and higher ATM costs will inevitably drive predictable changes in how people access and use their money. When frequent cash withdrawals become more expensive, most consumers will adapt by withdrawing larger sums of money less often. Once that cash leaves the formal banking system, it stays in circulation as physical currency held in personal wallets, household savings and retail cash registers, rather than flowing back into digital transactions. Ironically, the push to raise ATM fees is likely to result in *more* physical cash in active circulation across the country — the exact opposite outcome that banks and policymakers have worked for years to achieve.

    A successful shift to a digital financial system requires not just affordable services, but reliable access to financial infrastructure that the public can trust. Long before the latest fee hike, most Surinamese already knew the widespread frustration of broken or overcrowded ATMs, especially around monthly salary payment periods. Consumers often wait in lengthy queues only to find that the machine is out of service or cannot process their transaction. Now that withdrawals cost more, consumers who do find a working ATM are even more motivated to take out large lump sums rather than make multiple smaller withdrawals. This only reinforces cultural reliance on physical cash, pushing the country further from its digitalization goal.

    The fragmented pricing structure for cross-bank ATM use amplifies this problem. Even though Suriname has a formal nationwide ATM network, many consumers do not experience it as a unified, accessible system. Customers who withdraw cash from an ATM operated by a bank other than their own are already charged a premium rate. This leads people to travel out of their way to use an ATM from their own bank, even if another machine is located just around the corner. The result is longer wait times at popular machines, unnecessary vehicle traffic that increases carbon emissions and congestion, and inefficient underutilization of the country’s existing ATM infrastructure.

    Beyond rolling back the recent fee increase, a broader reevaluation of the incentives Suriname is creating for its citizens is long overdue. If the official national goal is to accelerate the adoption of digital payments, the system must make digital transactions an attractive, simple and reliable option for ordinary people, not penalize cash access in ways that backfire.

    This requires strategic investment across the financial sector: fully functional, well-maintained ATMs that work consistently when people need them, stable digital payment infrastructure that can handle widespread use, and a regulatory framework that does not discourage consumers from participating in the formal, non-cash financial system. After all, a digital economy is not built by raising barriers to access for ordinary people — it is built by earning public trust and making digital options the clear, beneficial choice for daily use.

    The responsibility to correct this misalignment does not fall only on Suriname’s commercial banks. The national government and the National Assembly also have key roles to play in ensuring that policies to promote digital financial flows actually deliver on their intended goals. Real progress requires a payment ecosystem where convenience, reliability and affordability work in tandem, not against each other. Only when ordinary Surinamese consumers experience digital payments as the easiest and most cost-effective option for daily transactions will physical cash gradually recede into the background of the national economy.

  • Bouwkosten blijven stijgen: prijzen in een jaar tijd gemiddeld 7,3% hoger

    Bouwkosten blijven stijgen: prijzen in een jaar tijd gemiddeld 7,3% hoger

    New preliminary data released by the Algemeen Bureau voor de Statistiek (ABS) confirms that construction sector costs in Suriname have continued their upward trend through the second quarter of 2026, marking one of the steepest year-over-year increases in recent years.

    Compared to the same three-month period in 2025, average construction prices climbed 7.3% in the second quarter of 2026. When measured against the first quarter of 2026, prices also rose by a steady 1.4%, according to the bureau’s latest Construction Price Index report published August 7, 2026.

    The ABS’ Construction Price Index is designed to track average price fluctuations for a standardized basket of materials, goods, and services required across three core construction segments: residential home building, non-residential utility construction, and civil engineering projects. To generate the most accurate reading of current market conditions, the index draws on price data collected from roughly 50 construction firms operating across Paramaribo and Wanica, covering 107 distinct products and services grouped into 16 main categories.

    Detailed index breakdowns reflect the consistent upward trajectory of construction costs: the index climbed from 1236.9 points recorded in the first quarter of 2026 to 1253.7 points by the end of the second quarter, matching the 1.4% quarter-over-quarter and 7.3% year-over-year growth rates reported by the ABS.

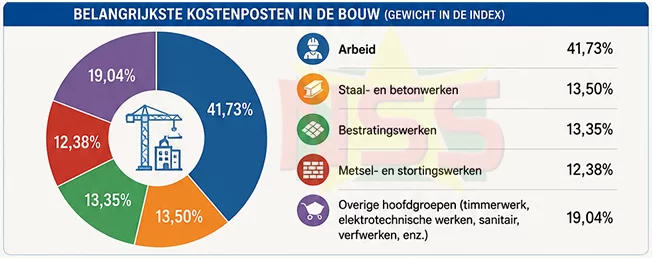
    When broken down by cost category, labor accounts for the single largest share of total construction expenditure by a wide margin, holding a 41.73% weighting in the overall index. Following labor, the next biggest cost drivers are steel and concrete works at 13.50%, paving works at 13.35%, and masonry and concrete pouring works at 12.38%. Because these four segments make up more than 80% of total construction costs combined, shifts in their pricing have an outsized impact on the overall index trend.

    Industry analysts warn that sustained rising construction prices will ripple through both private and public construction segments across the country. For private households, higher input costs will almost certainly translate to elevated prices for newly built residential properties, as well as higher quotes for home renovation projects. For public sector stakeholders, increasing construction costs will put additional budget pressure on infrastructure projects, including public road upgrades, new school construction, and the development of other core public amenities.

  • PUC Signals Review as Opposition to BTL-Smart Acquisition Broadens

    PUC Signals Review as Opposition to BTL-Smart Acquisition Broadens

    A high-stakes proposed consolidation in Belize’s telecommunications sector has entered a formal regulatory review phase, with the nation’s Public Utilities Commission (PUC) moving to assess Belize Telemedia Limited’s (BTL) planned 100% acquisition of rival provider Speednet Communications Limited, branded as SMART. The review comes as major business groups, independent legislators, and opposition lawmakers have ramped up demands for rigorous, law-aligned scrutiny of the transaction, raising red flags over competition, legal compliance, and public interest.

    In an official statement released Wednesday, the PUC pushed back against any assumptions of pre-judgment, emphasizing that its entire evaluation process will adhere strictly to existing legal frameworks, regulatory rules, and established procedural standards. The regulator acknowledged that the proposed takeover has sparked intense public attention, and that it recognizes the range of concerns and divergent perspectives held by industry stakeholders and the general public alike. Without taking an early stance on whether the acquisition is beneficial or harmful, the PUC underlined that it is legally bound to maintain full impartiality until its assessment is finalized.

    During its review, the commission will examine a broad set of critical factors, including consumer protection guarantees, uninterrupted service delivery for current Speednet and BTL customers, binding commitments for ongoing service quality, smooth transition plans for the merger, and overall market transparency and fairness. The PUC noted that its final determination will stand as its official position on the proposed transaction, though it has not yet announced a public timeline for completing the process.

    The PUC’s confirmation of its review came one day after BTL announced that its board of directors, backed by the company’s senior leadership team, had given preliminary approval to the plan to acquire all outstanding issued share capital of Speednet. BTL clarified that the deal remains conditional on the completion of full due diligence and further negotiations before any binding share purchase agreement is signed.

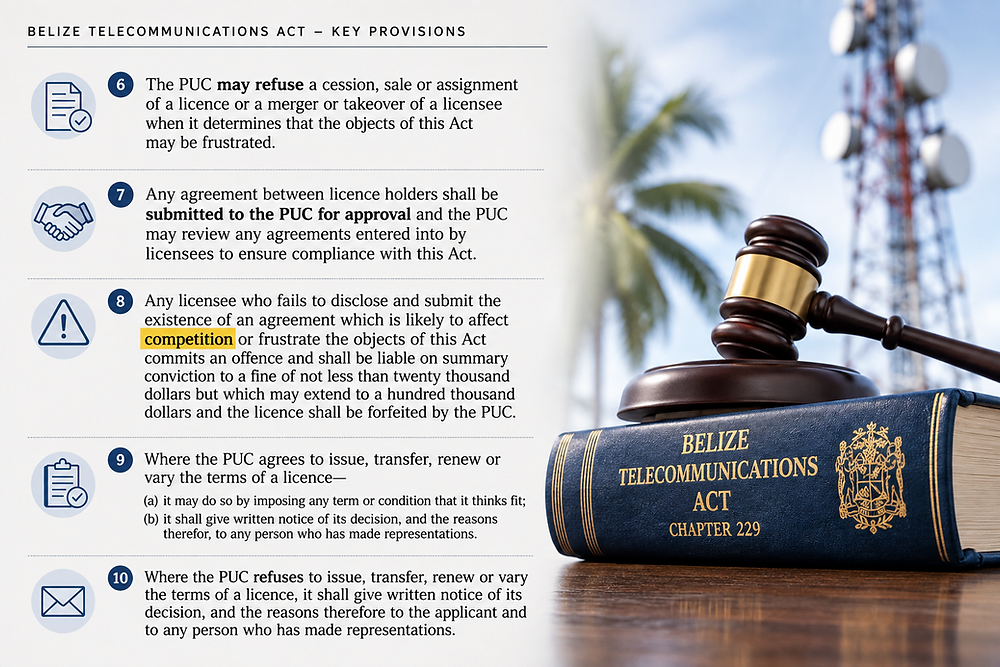
    With the review officially underway, focus has now shifted fully to the PUC’s statutory responsibilities outlined in the Belize Telecommunications Act. Section 19 of the legislation mandates that any telecommunications license holder must obtain prior written approval from the commission before transferring its license, ceding operational control, merging with another licensed entity, or completing a takeover. The law also grants the PUC authority to reject a proposed transaction if it finds the deal would undermine the core objectives of the telecommunications legislation. These statutory objectives include expanding access to reliable, affordable telecommunications services, supporting healthy market competition, encouraging industry investment and innovation, ensuring fair pricing, and protecting the interests of end users, service providers, and consumers.

    Beyond regulatory circles, key national social partner organizations have mobilized to coordinate a collective response to the proposed acquisition. On August 5, four of Belize’s leading civil society and business groups— the Belize Chamber of Commerce and Industry (BCCI), the Belize Network of Non-Governmental Organizations (BNN), the National Evangelical Association of Belize (NEAB), and the National Trade Union Congress of Belize (NTUCB)—issued a joint statement announcing they had convened to outline coordinated next steps. The groups plan to launch a cross-membership information sharing initiative designed to boost transparency around the deal, help stakeholders understand the potential impacts of the acquisition, and enable informed collective decision-making on how to proceed. The organizations reaffirmed their commitment to upholding good governance, protecting national economic stability, and advancing the public interest, noting they will consult their full membership bases before committing to any further action.

    Independent senators have also added their voices to the growing calls for rigorous oversight, reaffirming legal concerns about the proposed deal. Four independent senators released a joint statement on August 4, following a contentious sitting of the Senate Tuesday that saw opposition senators walk out of the chamber. All but one independent senator—Louis Wade, who represents national churches—joined the walkout before releasing their joint statement. In the document, the independent senators aligned themselves with the concerns previously raised by the BCCI, NTUCB, and opposition parties, which center on the acquisition’s legal compliance, potential harm to market competition, and the independence of the process used to value Speednet for the deal.

    The senators argued that creating a single monopoly provider in Belize’s telecommunications market would directly violate Section 42(4) of the Telecommunications Act. They also noted that existing law requires a mandatory regulatory review for any merger or acquisition that would substantially reduce competition in the market, and called on the PUC to resolve all outstanding concerns about the proposed shareholding change before any transaction is allowed to move forward.

    For its part, BTL has defended the proposed acquisition, framing it as a strategic investment that will deliver widespread benefits for Belize. The company claims the merger will eliminate redundant telecommunications infrastructure across the country, improve overall network reliability for consumers, expand connectivity access to rural underserved communities, and deliver stronger returns for shareholders. BTL also emphasized that the transaction will not require additional borrowing or new capital investment from the Belize Social Security Board.

    Now that the PUC has officially confirmed the launch of its statutory review, the national debate has shifted away from discussions of the commercial benefits of the deal and toward the legal and regulatory process that must conclude before any final agreement can be implemented. For the moment, the PUC has made clear it will not issue any judgment on the acquisition until its full review is complete.

  • Antigua Cruise Port Nominated for Caribbean’s Best Cruise Terminal at World Cruise Awards

    Antigua Cruise Port Nominated for Caribbean’s Best Cruise Terminal at World Cruise Awards

    In a major milestone for Caribbean cruise tourism, two major regional terminals operated by Global Ports Holding (GPH) – Antigua Cruise Port and Nassau Cruise Port in the Bahamas – have earned nominations for the 2026 Caribbean’s Best Cruise Terminal award from the World Cruise Awards.

    The industry recognition highlights Antigua Cruise Port’s consistent track record of targeted investment in upgrading cruise infrastructure and rolling out customer-centric improvements designed to elevate the overall experience for travelers visiting the island nation. GPH, the world’s largest independent cruise port operator, notes that both nominations are a direct reflection of the company’s ongoing strategic priorities: delivering operational excellence, curating memorable, high-quality experiences for passengers, and making long-term investments to build infrastructure that meets global industry standards.

    Following the announcement of the nominations, GPH has issued a public call for voting, extending gratitude to the communities, travel industry partners, and returning visitors that have supported its two Caribbean ports. Members of the public can cast their votes for the award via the official online voting portal hosted on the World Cruise Awards website for the Caribbean’s Best Cruise Terminal 2026 category.

    Industry observers note that nominations for this competitive award draw attention to the Caribbean’s position as one of the world’s top cruise destinations, with ongoing infrastructure upgrades helping the region attract increased passenger volumes and reinforce its market share in the global cruise sector.