分类: business

  • Eerste cao tussen IWWO en DP World Paramaribo rond

    Eerste cao tussen IWWO en DP World Paramaribo rond

    After more than a year of structured negotiations, the Integra/DP World Workers Organization (IWWO) and DP World’s Paramaribo operations have finalized and agreed to their first-ever collective labor agreement, a landmark deal that establishes a formal framework for labor-management relations at the South American port facility.

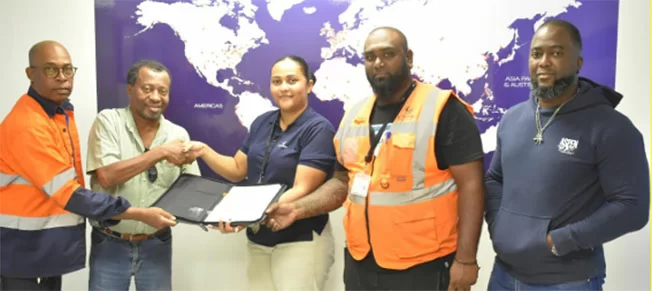
    Robby Berenstein, chairperson of IWWO and the figure identified second from left in accompanying photos of the negotiations, called the new agreement a critical foundational milestone for future collaboration between the port’s workforce and its executive leadership. Negotiations for the deal were first launched in June 2025, when representatives from IWWO’s governing board and DP World Paramaribo’s management came together to draft an initial outline that set core priorities and ground rules for talks. By March 2026, the parties had produced a fully developed draft agreement complete with specific, binding clauses and operational provisions.

    Berenstein emphasized that the entire negotiation process unfolded in a constructive, collaborative atmosphere. He credited open dialogue, mutual trust, and a shared commitment to crafting a modern, balanced agreement that meets the needs of both sides for the efficient, successful completion of talks. “We are delighted that this process has resulted in an agreement that aligns with the needs of today and prepares us to address the challenges of tomorrow,” Berenstein stated in remarks following the finalization of the deal.

    DP World Paramaribo’s negotiation team was led by a cross-functional group of senior leaders including People Manager Xamira Visser, Chief Executive Officer Mervel Kotzebue, and Shalinie Ramdjas, Employee Engagement and Compensation Human Resources Business Partner.

    As the first formal collective bargaining agreement between the two organizations, particular focus was placed throughout negotiations on striking a fair, sustainable balance between the interests of the port’s 83 IWWO member workers and the operational needs of DP World as the employer. The finalized accord formalizes agreements on a range of core workplace issues, including employment terms, worker rights, and shared responsibilities for both parties.

    For IWWO, the new agreement also represents a key step forward in professionalizing formal social dialogue within DP World Paramaribo. The organization says the deal will serve as a enduring framework for long-term sustainable labor relations, tying together worker interests, business growth, and constructive social partnership between management and the workforce. Currently, IWWO counts 83 registered members among DP World Paramaribo’s staff.

  • Flow Dominica to retire legacy Cwdom.dm email domain in September

    Flow Dominica to retire legacy Cwdom.dm email domain in September

    Caribbean-based telecommunications provider Flow Dominica has announced that its long-running legacy email service, cwdom.dm, will be permanently shut down in stages between late August and the end of September 2026. The company has laid out a clear timeline for the wind-down to give existing users ample time to migrate their critical data and minimize disruptions to their personal and professional communications.

    According to an official press statement released by the firm, the first phase of the decommissioning process will launch on Monday, August 31. On this date, all cwdom.dm accounts will lose the ability to send outgoing emails. The second phase will follow two weeks later, on Tuesday, September 15, when the provider will stop routing incoming emails to legacy cwdom.dm addresses. By Wednesday, September 30, the entire service will be fully retired. After this final deadline, users will be permanently locked out of their accounts, with no option to recover stored messages or account data from the outdated platform.

    Francine Harve Jean-Jacques, Marketing and Communications Executive at Flow Dominica, explained that the phased wind-down was designed specifically to prioritize customer convenience. The decision to retire the service, she noted, was driven by the fact that the underlying infrastructure supporting cwdom.dm has reached the end of its operational lifespan. The aging platform can no longer meet the modern security, functionality, and reliability standards that contemporary email users expect from their service providers.

    “We understand that many of our customers have relied on their cwdom.dm email addresses for years, and this change may feel inconvenient,” Harve Jean-Jacques said. “That is why we structured this transition in stages: to give every user enough time to move their important contacts, emails, and other data without last-minute panic.” She added that the company’s top priority throughout the process is to ensure remaining users have access to clear guidance, dedicated support, and all the resources they need to complete their migration before the final shutdown date.

    Flow Dominica is urging all customers still using cwdom.dm email addresses to start their transition immediately, rather than waiting until the September 30 deadline to avoid permanent data loss. The company says it will be providing ongoing updates and support to help users switch to its current, modern email offerings or alternative third-party services as needed.

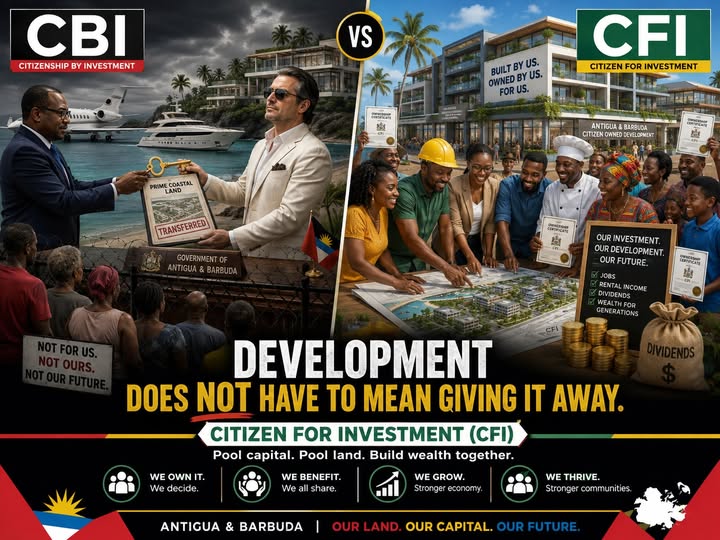
  • OPINION: Time for a”Citizens for Investment” Progamme

    OPINION: Time for a”Citizens for Investment” Progamme

    Across many developed and developing economies alike, stagnating wage growth, widening wealth inequality, and declining public trust in institutional investment strategies have created a pressing economic moment that demands creative, people-centered solutions. For decades, large-scale investment has largely been driven by institutional investors, corporate boards, and government infrastructure funds – channels that often prioritize short-term shareholder returns over long-term community benefit, leaving ordinary citizens locked out of both decision-making processes and the financial gains that come from strategic local and national investment.

    This exclusion does not just hold back individual households; it weakens the overall resilience of national economies. When investment is disconnected from the needs and priorities of the people it is supposed to serve, projects often face public pushback, delays, or fail to deliver the intended social and economic outcomes. It is this gap that a proposed “Citizens for Investment” programme aims to fill, reimagining how investment is structured and who gets to benefit from it.

    The core premise of the programme is simple: open up accessible, low-barrier investment opportunities to ordinary citizens, rather than concentrating capital ownership in the hands of a small group of institutional stakeholders. Unlike traditional retail investment schemes that focus on speculative stock market trading, the Citizens for Investment programme would prioritize long-term, productive investments in key domestic sectors – from renewable energy infrastructure and affordable housing to small business development and public health care expansion.

    To make the programme inclusive for low- and middle-income households, it would include structured protections: capped minimum investment amounts to reduce barriers to entry, government-backed guarantees to limit downside risk for participants, and tax incentives for returns generated from qualifying socially beneficial projects. Participants would also gain limited but meaningful input into the selection of regional projects, ensuring that investment aligns with local community needs rather than distant corporate interests.

    Proponents argue that this model delivers three key wins. First, it democratizes wealth building, allowing ordinary citizens to build long-term assets alongside institutional investors, rather than relying solely on wage income to build financial security. Second, it unlocks billions in untapped domestic capital that can be directed toward pressing national priorities, from the clean energy transition to addressing housing shortages, that often struggle to secure sufficient funding from traditional sources. Third, it rebuilds public trust in investment and economic policy by putting citizens directly at the center of decision-making, reducing the NIMBYism and opposition to critical infrastructure projects that stems from a sense of disenfranchisement.

    Critics, however, have raised valid concerns about the potential risks of such a programme. They warn that expanding retail investment into large infrastructure projects could expose inexperienced investors to unforeseen market volatility, even with government guarantees, and that bureaucratic red tape could slow down project delivery compared to traditional institutional investment models. These concerns are not unfounded, and they demand careful programme design that prioritizes investor protection and transparent governance at every stage.

    Despite these valid questions, the current economic context makes the case for piloting a well-designed Citizens for Investment programme stronger than ever. Persistently high wealth inequality, the massive unmet funding need for the global clean energy transition, and growing public discontent with top-down economic policy all point to the need for new models that deliver both economic growth and shared prosperity. It is time for policymakers and economic leaders to take this idea seriously, test it in targeted regional pilots, and build a programme that works for all citizens, not just the financial elite.

  • 84% of BCWU Members Turn Against BTL-Speednet Deal

    84% of BCWU Members Turn Against BTL-Speednet Deal

    Nearly four years after initial reports of a potential industry consolidation first emerged in Belize’s telecommunications sector, a major turning point has arrived: 84 percent of members from the Belize Communications Workers Union (BCWU) have formally withdrawn their support for Belize Telemedia Limited’s (BTL) planned takeover of mobile network operator Speednet, which trades under the brand name SMART. This decisive shift in member sentiment followed an emergency gathering of union representatives held last Thursday, where votes were cast on the proposed deal after seven months of unresolvable negotiations with BTL leadership. The road to this rejection stretches back to January 9 of this year, when unconfirmed media reports first leaked word of BTL’s plans to acquire Speednet and associated cable assets. Reacting quickly to the lack of official communication, the BCWU requested an emergency meeting with BTL management just three days after the reports broke. At that initial meeting, union leaders emphasized that their members occupied multiple critical roles beyond just being BTL employees: many are also BTL shareholders, taxpayers contributing to national public funds, Social Security contributors, and private citizens with a direct personal and financial stake in how the acquisition shapes the country’s telecommunications industry. During that first meeting, the BCWU laid out a clear list of non-negotiable issues that required transparent clarification from BTL before any member support could be secured. Top priorities included binding guarantees for job security for all current BTL employees, a full breakdown of the real financial costs and long-term economic implications of the merger, public confirmation that all required procurement and regulatory approval processes had been followed correctly, answers to outstanding questions about post-merger corporate governance and public disclosure, clarity on whether existing Speednet employees would be allowed to join the BCWU after the acquisition is completed, and a commitment to a phased approval process that includes full, good-faith consultation with the National Trade Union Congress of Belize (NTUCB). In the months following that initial meeting, BTL leadership has only distributed a general employee bulletin that outlines the claimed national benefits of the deal, according to the BCWU. Union representatives note that this surface-level communication fails to address any of the specific, detailed concerns raised by their members, and far more direct engagement with affected workers is required to resolve open questions. Throughout the entire negotiation process, the BCWU says it has maintained a consistent stance calling for full transparency, timely two-way communication, formal consultation with relevant labor bodies, and good-faith negotiations with BTL’s executive team. The overwhelming vote against the current proposal, the union argues, directly reflects the fact that none of these core demands have been met, and none of the outstanding concerns have been resolved. Moving forward, the BCWU announced it will coordinate closely with the NTUCB to map out its next steps in opposing the deal as currently structured. In an official statement released after the emergency vote, the union reiterated that BTL’s workers are key stakeholders in the acquisition, and their legitimate concerns cannot be sidelined in the push to complete the merger. “The workers of BTL are stakeholders in this process, and their voices must be heard,” the statement read.

  • ‘Generator use right during power crisis’

    ‘Generator use right during power crisis’

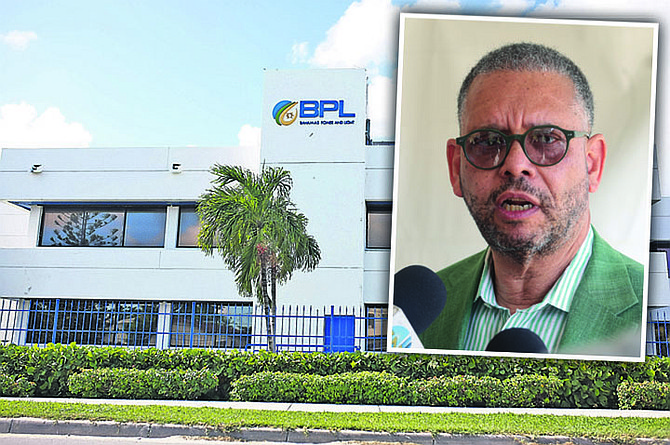
    New Providence is once again grappling with widespread, recurring power disruptions that have left communities across the island — including several upscale western neighborhoods near the Baha Mar resort — without electricity for stretches as long as 24 hours, and the crisis has sparked sharp division among Bahamian business leaders over how the private sector should respond to a strained national grid.

    Robert Sands, senior vice-president of the $3.5 billion Baha Mar resort complex, has framed large businesses’ voluntary shift to backup generators during peak grid stress as an act of responsible corporate citizenship, pushing back against growing criticism from the country’s top business advocacy group over the costs and instability of the current power system.

    Sands explained that Baha Mar and other large corporate entities have partnered with Bahamas Power and Light (BPL), the national utility provider, for years, activating on-site standby generation to cut their grid draw when system capacity nears its limit. “This is not a new occurrence, and I think that’s good corporate citizenry in a country where entities like Baha Mar do well and benefit from the country,” Sands told reporters on the sidelines of an event at the National Art Gallery. “It’s only important that we support and give back to support the country through challenging times.”

    BPL has pinned the recent spate of outages on a perfect storm of seasonal and infrastructure issues: soaring summer temperatures driving record electricity demand, paired with aging equipment failures, underground cable faults, and overloaded circuits that push transformers to peak operating capacity. To prevent catastrophic damage to grid infrastructure, BPL chief operating officer Anthony Christie confirmed the utility has implemented controlled load balancing to relieve strain on overtaxed hardware. Deputy Director of Energy Verron Darville added that regulators and the utility have specifically requested government agencies and large private customers with backup generation capacity to exit the grid during peak demand windows, reserving remaining capacity for residential users and small businesses that lack the resources to generate their own power.

    Sands emphasized that shifting to in-house generators has not interrupted Baha Mar’s operations or slowed the country’s ongoing tourism recovery, even as he acknowledged the widespread outages are a major nuisance for residents and visitors alike. “No impact at all,” he said of the effect on Baha Mar’s operations. “It’s been an irritant.”

    The resort executive also pushed for greater public patience with BPL, arguing that grid reliability has improved markedly in recent months despite current challenges. “We have to be patient,” he said. “These are some stumbling blocks, but by and large, we have been supportive of the progress and also the future of BPL. And even as I said, it has been an irritant, but it has not been a stumbling block to the growth of tourism in our country.” Sands declined to share the exact total cost Baha Mar incurs to run on generator power, only confirming the resort pays market rate for the diesel required, and noting that BPL maintains fair terms for corporate participants in the voluntary load reduction program.

    But the Bahamas Chamber of Commerce and Employers Confederation has rejected Sands’ framing, warning that the ongoing electricity crisis is placing an unsustainable additional burden on businesses already reeling from high taxes, rising input costs, and heavy regulatory requirements. Chamber CEO Leo Rolle said repeated outages directly cut into business productivity while forcing all companies — not just large resorts with the ability to invest in backup generation — to absorb unplanned additional operating expenses.

    The Chamber has issued a formal call for the Davis administration, BPL, and Bahamas Grid to release a clear, actionable roadmap and public timeline for fixing the grid and restoring consistent, reliable power across New Providence. To mitigate harm for small and medium enterprises in the near term, the group has also proposed policy solutions including expanded subsidized energy audits, targeted grants to help small businesses adopt solar power and energy-efficient equipment, and expanded duty-free concessions for high-efficiency energy infrastructure.

  • Dominican cement industry leads Latin America and Caribbean exports

    Dominican cement industry leads Latin America and Caribbean exports

    The Dominican Republic’s cement industry has solidified its position as a core engine of the country’s export economy, cementing the nation’s status as the leading exporter of cement, lime, and gypsum across the Latin America and Caribbean (LAC) region. New trade data analyzed by economic researchers offers a clear snapshot of both the industry’s recent gains and the broader challenges facing the Dominican Republic’s trade sector.

    New figures drawn from the General Directorate of Customs (DGA), and compiled and published by the Regional Center for Sustainable Economic Strategies (Crees), show that total Dominican exports reached $3.34 billion in the first six months of 2026. That marks a robust 35.1% year-over-year increase compared to the same January-to-June period in 2025. The chemicals and minerals sector, one of the country’s most consistent trade contributors, accounted for $295 million of that first-half total – equal to 8.8% of all national exports. When broken down further, cement and copper alone made up 4.8% of the country’s total export revenue in the period.

    Data from a 2025 report published by the Dominican Ministry of Industry, Commerce and MSMEs (MICM) underscores just how dominant the country has become in the regional building materials market. Across the entire LAC region, total combined exports of cement, lime, and gypsum hit $581.3 million in 2025. The Dominican Republic captured a 25.4% share of that regional total, outperforming historic regional leaders Mexico and Guatemala to claim the top spot as the region’s largest exporter of these materials.

    Representatives from the Dominican Association of Portland Cement Producers (Adocem) note that the strong export performance from the cement sector proves the value of investing in a resilient domestic industrial base. A robust local manufacturing ecosystem, the association argues, can both satisfy domestic demand for core building materials and successfully compete against international producers in cross-border markets.

    While welcoming the strong growth in exports across key sectors like cement, Crees has sounded a note of caution about the long-term stability of the Dominican Republic’s trade profile. The economic research center points out that the country’s export revenue remains heavily concentrated in a small handful of sectors, creating vulnerability to global market shocks. To mitigate this risk, Crees is calling for urgent policy action to expand trade diversification and boost the production and export of higher-value-added goods.

    Adocem has aligned itself with the push for greater export diversification, arguing that strengthening local manufacturing across core sectors is a key pathway to achieving that goal. A thriving domestic manufacturing industry, the association notes, drives increased foreign and domestic investment, spurs innovation, pushes firms to improve operational efficiency, and encourages the adoption of more sustainable production practices – all of which support the shift toward a more diverse, value-driven export economy.

    To continue building on the progress seen in the cement sector and expand that success to other industries, Adocem emphasized the critical role of thoughtful public policy. The association called for government policies that prioritize productive private investment, guarantee legal certainty for industrial operations, strengthen national competitiveness in global markets, and improve domestic producers’ access to international markets. These policy adjustments, the group argues, would allow domestic industries to scale up production, generate higher levels of economic value, and drive more inclusive, sustainable growth across the Dominican economy.

  • Asonahores calls for free beach access and clear rules

    Asonahores calls for free beach access and clear rules

    A long-simmering debate over coastal access in the Dominican Republic has gained new clarity after a top tourism industry executive laid out a balanced path forward that protects both public rights and private investment. Aguie Lendor, executive vice president of the Dominican Hotel and Tourism Association (Asonahores), laid out the organization’s official stance in a recent interview with local news outlet El Despertador, making clear that the group supports permanent, free access to the country’s iconic coastline for all people — both Dominican citizens and international visitors. Lendor emphasized that the public holds an inherent right to enjoy the country’s beaches, a position that aligns with widespread public sentiment across the Caribbean nation. However, she also pushed for the introduction of clear, structured regulations that can foster peaceful coexistence between members of the public visiting beaches and the hotel properties that line much of the Dominican coastline. In her argument for targeted regulation, Lendor highlighted the significant investments hotels make to maintain the coastal areas adjacent to their properties. These investments cover a wide range of critical services, from regular beach cleaning and waste management to on-site security personnel, ongoing infrastructure upkeep, and public amenities that benefit all beachgoers, not just hotel guests. These ongoing responsibilities, she argued, must be factored into any new regulatory framework governing coastal space use. Ultimately, Lendor stressed that the core goal of any policy should be striking a fair, sustainable balance: one that preserves the public’s right to access and enjoy Dominican beaches, while avoiding harm to the tourism sector — the single largest driver of economic activity and employment in the Dominican Republic. “We need to make harmonious use of our resources,” Lendor told El Despertador, framing the issue as a key priority for the long-term health of both the Dominican public and its vital tourism economy.

  • The Dominican Republic in the AI Economy starts with venture capital

    The Dominican Republic in the AI Economy starts with venture capital

    Across Latin America and the Caribbean, nations are racing to position themselves as leaders in high-growth, future-focused sectors: artificial intelligence, semiconductor manufacturing, advanced production, and nearshoring operations. The Dominican Republic is no exception. It has rolled out a national AI strategy, secured a landmark sovereign AI partnership with global tech giant NVIDIA, and actively markets itself as a regional tech hub to international investors via its trade and investment promotion agency ProDominicana. This strategic push is far more than superficial nation branding; it represents a deliberate effort to lift the Dominican economy into higher-productivity sectors that generate robust intellectual property (IP) and high-value export revenue. But beneath these bold policy announcements lies an unresolved, critical question: who will provide the risk capital needed to back homegrown Dominican companies competing in these new industries?

    Current financing mechanisms in the country are not built to meet this need. The Dominican financial sector is well-versed in traditional credit lending, which relies on collateral, established revenue streams, predictable cash flow, and credit history to assess risk. These tools work effectively for mature businesses and traditional small and medium-sized enterprises, but they are fundamentally incompatible with early-stage innovation. A startup developing proprietary AI, cutting-edge software, new fintech infrastructure, or advanced materials often spends years building intangible assets like code, research datasets, and team expertise before turning a profit. Its most valuable holdings are not physical real estate that can be seized as loan collateral—they are future growth potential that traditional banks are not structured to evaluate or fund.

    This is where venture capital fills a unique gap: it takes on the uncertainty of early-stage innovation in exchange for equity, aligning risk with the potential for outsized growth. When this distinction is ignored and all entrepreneurial funding is lumped into a single category of “business financing,” systemic confusion emerges. Founders chase debt products they can never realistically repay, banks are forced to take on risks they cannot price, and potential investors lack clear regulatory and structural frameworks to deploy capital. The end result is not just less funding for startups—it is weaker competition in the very industries the country is trying to build.

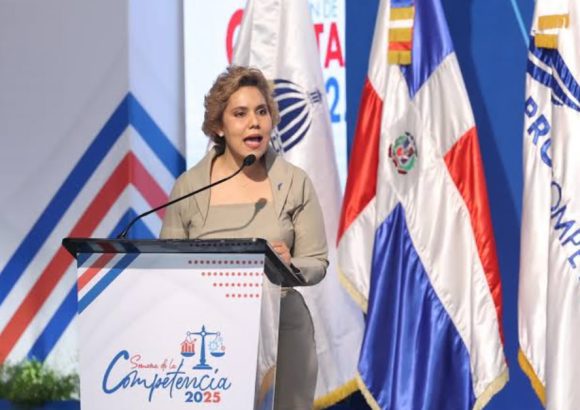
    Competition policy, as it is currently practiced, often only intervenes after companies have already grown to dominate a market. Regulators step in to review mergers, break up abusive monopolies, or investigate price gouging only when market concentration has already occurred. But in technology-intensive sectors, the competitive landscape is shaped years before any dominant player emerges. One startup secures the risk capital it needs to hire top talent, acquire customers, and survive years of unprofitability, while its potential competitor cannot close a funding round and disappears before regulators ever learn its name. This gap is especially acute across Latin America and the Caribbean, where the Inter-American Development Bank (IDB) has documented that pre-existing market concentration, regulatory barriers, and weak enforcement already limit new entry, innovation, and economic opportunity.

    As regional competition grapple with new challenges posed by AI, digital platforms, and data-driven market power—including network effects, outsized scale advantages, and platforms that become critical infrastructure for other businesses—a modern approach to competition must expand its focus. It cannot only question whether large incumbents are behaving fairly; it must also ask whether new, independent challengers can access the capital they need to enter the market, scale, and ultimately compete. This does not mean competition authorities should become venture capital funds, but it does mean that the development of a local venture capital ecosystem is directly tied to their core mission: ensuring markets remain genuinely open to new competitors.

    While the Dominican Republic already hosts a small number of successful startups—including Santo Domingo-based AlterEstate, which has secured backing from 500 Global, and cacao-focused startup Inaru, which has raised roughly $12 million—these isolated success stories do not add up to a functional, measurable national venture market. The country has general frameworks for entrepreneurship, foreign investment, and securities regulation, as well as sophisticated financial institutions and investment vehicles. But it lacks a coherent, well-defined venture capital architecture that answers core questions for both local and international investors: Which institution is responsible for developing the national venture ecosystem? Which local financial institutions are permitted to allocate capital to the venture asset class? How should early-stage funds, convertible investment instruments, and cross-border venture portfolios be regulated and taxed? What tax rules apply when capital gains from exits are reinvested into new startups? How can public and multilateral de-risking reduce early-stage losses without crowding out private investment?

    The absence of clear answers to these basic questions does not ban venture investment—it makes the market illegible. Foreign investors do not require the elimination of risk; they require risk to be clearly defined and structured. The Dominican Republic is far from alone in facing this gap. A 2025 IDB study of five Caribbean economies found that most regional venture ecosystems remain nascent, marked by limited investment activity, widespread financing gaps, weak exit mechanisms, and a need for regulatory reform, stronger investor networks, and public de-risking.

    The urgency of addressing this gap has grown as global venture capital has become more concentrated. The Latin American Venture Capital Association (LAVCA) reports that regional venture investment is increasingly concentrated in a smaller number of larger deals, with follow-on funding for existing portfolio companies representing half of all early-stage investment between 2023 and 2025. At the same time, UN Trade and Development data shows that while digital economy foreign investment grew 14% recently, just 10 countries capture 80% of all new digital projects. Declaring a goal to become a regional tech hub is no longer enough; countries are now competing to build the full ecosystem of infrastructure, talent, regulation, and risk capital that allows homegrown tech companies to form and scale locally.

    Before the Dominican Republic designs new tax incentives or rewrites regulations, author Jonathan Joel Mentor argues it first needs to map the existing venture market to build a shared evidence base for policy. He proposes a national Venture-Market Competitiveness Map that assesses five core layers of the ecosystem: strategic demand (which strategic sectors require venture capital to develop local Dominican technologies and competitors), capital supply (which investors, ticket sizes, stages, and vehicles currently exist), regulatory legibility (can local and foreign investors clearly understand legal, tax, and compliance requirements), commercial access (can funded startups access corporate clients, public procurement contracts, and export markets), and liquidity (can investors exit positions and recycle returns into new generations of startups).

    No single public institution owns all parts of this ecosystem: competition authorities oversee market entry and contestability, trade and investment agencies attract foreign capital and support internationalization, industrial development bodies focus on productivity growth, financial regulators oversee investor protection and legal structures, multilateral institutions prioritize private sector development, and private financial institutions manage capital allocation. The map would give all these stakeholders a shared evidence base to align their decisions, budgets, and interventions.

    To build this map, the country first needs to answer a set of basic empirical questions that currently lack public answers: How much venture capital is currently being deployed in the Dominican Republic? Which sectors is it going into? What stages of company growth receive funding? Where does this capital come from? Through what legal and financial structures is it invested? Where do promising startups hit dead ends trying to raise their next funding round? Why do most Dominican founders choose to register their companies abroad? Which regulatory frictions deter investment from both local and foreign backers? How does the venture financing gap shape competition in strategic sectors from AI to fintech to tourism technology?

    Answering these questions would require collecting transaction-level data, conducting legal analysis, interviewing investors, benchmarking against peer markets, and establishing a formal institutional process to maintain an updated baseline. A national State of Venture Capital and Innovation report would give all relevant public and private stakeholders a shared foundation for future policy and intervention.

    Mentor emphasizes that the Dominican Republic’s strategic ambition to build tech-intensive, high-value industries is correct. But ambition alone cannot build new industries. New sectors only emerge when talent, regulation, customers, and capital operate as a connected system. Without a functional local venture market, Dominican founders will continue to build their companies domestically but finance them abroad, foreign technology will scale more easily in the local market than Dominican homegrown tech can, and the country will end up consuming innovation while other jurisdictions capture the IP, equity value, and economic benefits. The competition for the future of the Dominican economy does not start when the first large AI tech giant ends up before a regulator—it starts now, with building the market architecture that determines whether a Dominican challenger can get funded at all.
  • LISTEN: Antigua PM Browne Announces Major Overhaul of Offshore Banking Sector

    LISTEN: Antigua PM Browne Announces Major Overhaul of Offshore Banking Sector

    Antigua and Barbuda’s Prime Minister Gaston Browne has tabled dramatic, sector-altering reforms that will bring an end to the country’s long-standing offshore banking model as it currently operates, unveiling steep increases in mandatory capital reserves and the elimination of decades of preferential tax treatment for offshore financial institutions.

    Speaking during his regular weekly public radio address, Browne outlined that the proposed reforms would raise the minimum required capital for licensed offshore banks from the current range of US$3 million to US$5 million to approximately US$20 million. He framed the sharp capital hike as a critical safeguard for depositors and a necessary step to shore up the resilience of Antigua and Barbuda’s entire financial system.

    Browne emphasized that the existing low capital thresholds left the nation exposed to unnecessary systemic risk, arguing that the current requirements offered too little protection against institutional losses, mismanagement, and the potential misappropriation of customer deposits. “It’s just too low,” he stated, noting that a US$20 million minimum capital requirement would create a far more robust financial buffer that can absorb unexpected shocks without endangering depositor funds or national financial stability.

    In addition to the capital overhaul, the prime minister proposed scrapping the preferential tax regime that has long benefited offshore banks, bringing them into parity with domestic commercial entities by imposing the standard 25% domestic corporate tax rate with no exceptions. “Any such entity operating in that sector should pay the exact domestic rate of tax — so 25%, no special dispensation,” Browne said.

    The prime minister has already directed two key regulatory bodies — the Ministry of Legal Affairs and the Financial Services Regulatory Commission (FSRC) — to lead a comprehensive sector review and deliver formal recommendations for the restructuring framework. The review will not only cover capital rules and tax policy but also include new measures to crack down on profit shifting, a common practice where multinational firms move profits to lower-tax jurisdictions to avoid paying domestic taxes.

    Browne made clear that the cumulative changes will fundamentally reshape the offshore financial sector, noting “Essentially, the sector as we know it will probably cease to exist.” Under the proposed new structure, the government would pivot to allowing only wholesale banking operations, including locally hosted branches of well-established, large international banks, while continuing to support the country’s existing international business company regime.

    The prime minister justified the sweeping changes by noting that the legacy offshore banking model has failed to deliver meaningful economic value to Antigua and Barbuda’s broader population. He added that the sector has also drawn persistent, heightened scrutiny from global international regulatory bodies over concerns related to aggressive tax avoidance practices, weak regulatory controls, and allegations of widespread financial misconduct.

    As of the announcement, none of the proposed changes have been finalized or enacted into law. Browne confirmed that the final regulatory structure of the reformed sector will be set once the government receives and reviews the formal recommendations from the Ministry of Legal Affairs and the FSRC.

  • Call for Expressions of Interest : Project to support entrepreneurial invention and startups

    Call for Expressions of Interest : Project to support entrepreneurial invention and startups

    Haiti’s Ministry of Commerce and Industry (MCI) has opened a call for expressions of interest to recruit the first cohort of a new national university-focused startup incubation initiative, aimed at revitalizing the country’s entrepreneurial landscape. Spearheaded by MCI Minister James Monazard as part of the government’s mandate to boost trade, industrial development, and small business growth, the Project to Support Entrepreneurial Invention and University Startups (AIESU) seeks to build a resilient, interconnected university entrepreneurial ecosystem across Haiti through a phased rollout of campus-based startup incubators.

    The initiative is launching its pilot phase at Quisqueya University, with this call for candidates marking the first major milestone of the pilot. Through the open call, program organizers will select eight innovative early-stage ventures to participate in a six-month structured incubation program, designed to help founders refine their concepts and scale their impact.

    Eligible applicants include current students, recent graduates, academic researchers, and cross-disciplinary teams affiliated with any accredited higher education institution in Haiti. The program accepts proposals across eight high-priority sectors that align with Haiti’s long-term economic and social development goals: digital technologies, artificial intelligence, agribusiness, manufacturing, green economy, health, creative industries, and innovative services.

    Shortlisted ventures will be evaluated based on a clear set of criteria that balance innovation potential and national impact. Judges will score applications on the originality of their idea, market fit, technical feasibility, long-term business model viability, projected growth trajectory, team capacity and commitment, and the venture’s projected contribution to inclusive economic and social progress across Haiti.

    Selected startups will gain access to a comprehensive package of support to advance their projects. Benefits include dedicated co-working space, structured entrepreneurship training, one-on-one mentorship from industry experts, end-to-end technical, legal, and administrative guidance, support in preparing for future funding rounds, and referrals to Haiti’s Investment Facilitation Center (FDI) for high-performing projects with strong investment appeal.

    To complete an application, candidates must submit a filled-out application form, official photo identification, curriculum vitae for all team members, official proof of affiliation with a recognized Haitian higher education institution, and a five-page maximum concept note outlining their venture. All application materials must be submitted through the official MCI portal at https://mci.gouv.ht/aiesu.

    The selection process follows a structured multi-step timeline, beginning with a closing date for applications of August 15, 2026. Administrative eligibility checks will run from August 17 to 25, while the independent selection committee will conduct technical evaluations of qualified applications between August 26 and September 10. Shortlisted candidates will be invited to deliver in-person or virtual pitches to the committee between September 15 and 20, followed by final deliberations between September 21 and 25. Results will be published between September 25 and 30, with selected ventures receiving official notification by the end of September. The six-month incubation program is scheduled to officially launch on October 1, 2026.

    Participation in the open call is completely free for all eligible candidates. MCI notes that selection for the incubation program does not guarantee direct funding, and reserves the right to request additional documentation or conduct compliance verifications at any stage of the selection process.