分类: business

  • Economy : Accounting framework for local authorities

    Economy : Accounting framework for local authorities

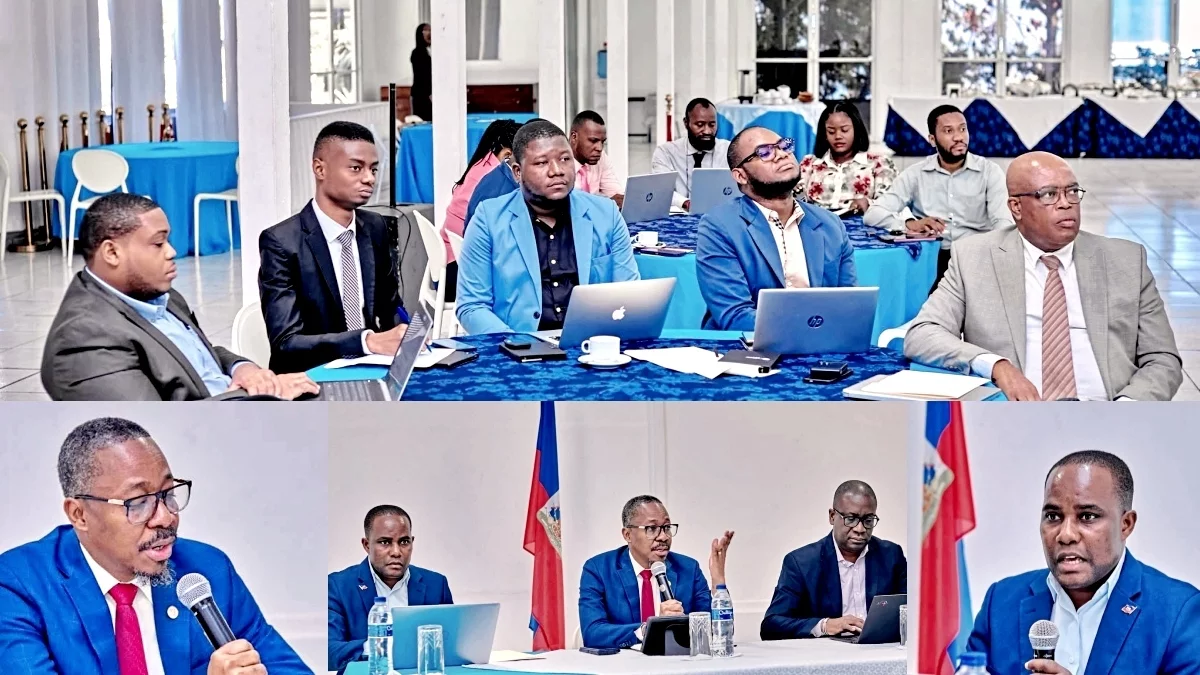
    Against a backdrop of ongoing efforts to modernize Haiti’s public financial management system, a pivotal multi-stakeholder meeting took place last week at Port-au-Prince’s Hotel Montana, bringing together key national and local actors to advance long-awaited reform of local authority accounting practices. Organized by Haiti’s Directorate General of the Treasury and Public Accounting (DGTCP), the gathering included representatives from the Ministry of the Interior and Local Authorities, senior public treasury accountants, delegations from the Superior Court of Auditors and Administrative Disputes (CSC/CA), and municipal leaders from seven of Haiti’s most populous jurisdictions: Port-au-Prince, Delmas, Cité Soleil, Tabarre, Pétion-ville, Carrefour, and Croix-des-Bouquets.

    Opening the summit, Jean Michel Silin, Director General of the Budget, marked a key milestone in the reform process, announcing that years of planning have transitioned into tangible action. Silin confirmed that the long-planned assessment of Haiti’s existing local authority accounting framework has officially moved beyond conceptual stages and is now actively underway, with all work fully documented and undergoing systematic consolidation. He underlined that the overarching reform strategy has been intentionally structured to be progressive, practical, and long-term sustainable, developed through iterative collaboration with all affected stakeholders to deliver tangible improvements in public service delivery for Haitian citizens.

    Guided by Nicodème Adzra, a financial management expert from Expertise France, alongside technical leads from the DGTCP and CSC/CA, working sessions centered on two core priority areas. First, participants mapped and reviewed end-to-end workflows for both local government revenue collection and public expenditure, diving into granular details of current processes, approval procedures, the existing chart of accounts, and the digital IT tools currently used by local authorities to manage public funds. Second, the group discussed clarifying and strengthening the CSC/CA’s mandate to provide effective oversight and targeted capacity support to municipal and local governments across the country.

    Looking ahead to the coming months, stakeholders have outlined clear next steps to keep the reform on track. The next major milestone will be the completion of the ongoing assessment and the publication of a technical analysis note, drafted using insights and data collected from recent field visits to local authorities across Haiti. This document will form the evidence-based foundation for two critical subsequent efforts: a full revision of the outdated local accounting framework, and the development of a comprehensive national training and capacity-building program. This program will be rolled out alongside the broader launch of the Haitian State’s new standardized Chart of Accounts (PCEH), a key plank of national public financial reform.

  • Olie boven $107 terwijl Washington “overwinning” uitroept

    Olie boven $107 terwijl Washington “overwinning” uitroept

    On Monday, global crude oil prices jumped more than 3% following two high-stakes energy infrastructure disruptions over the weekend: an attack on an Iranian vessel in the Strait of Hormuz and a drone strike that damaged Saudi Arabia’s critical East-West oil pipeline. Benchmark Brent crude climbed $3.21 to settle at $107.82 per barrel, while U.S. West Texas Intermediate gained $3.17 to reach $103.22 per barrel. This uptick extended an existing rally, after Brent closed at $101.21 on September 9 — its highest level since late May. Market analysts note the price increase is not driven by a single isolated incident, but rather markets pricing in the probability of a prolonged regional conflict that disrupts global energy supplies.

    Washington has pushed back against growing anxiety, claiming that transit traffic through the Strait of Hormuz, one of the world’s most vital energy chokepoints through which roughly one-fifth of global oil and gas supplies pass, is improving despite a ongoing diplomatic deadlock between the U.S. and Iran. U.S. Energy Secretary Chris Wright said Sunday that an average of 10 million barrels of oil passed through the strait daily over the previous week, adding that volumes have recovered to two-thirds or more of pre-conflict levels. Former U.S. President Trump echoed these claims, asserting that U.S. forces have “full control” over the waterway and are escorting vessels carrying millions of barrels of oil through the passage.

    Iran has directly disputed these U.S. claims. Tehran maintains it retains control over access to the Strait of Hormuz, and has warned vessels against using unapproved shipping routes. Last week, Iran announced a new restricted shipping zone around the critical waterway, tightening its leverage over transit.

    Independent shipping data from tanker trackers backs up Iran’s implicit assertion that traffic remains far below normal levels. Preliminary tracking data cited by Reuters shows that the number of daily transits through the strait dropped to single digits over the weekend, well below the 10-day average of 14 transits per day. In total, just 14 vessels passed through the waterway over the entire weekend, with four exiting the Persian Gulf and 10 entering. Before the U.S.-Israeli war against Iran began in February, more than 100 vessels transited the strait daily, carrying an estimated 20 million barrels of oil. Reuters notes that the data remains preliminary and may be updated, as some vessels travel with their Automatic Identification System transponders disabled to avoid detection, placing them outside official counts.

    The disruption has put massive pressure on alternative supply routes that Saudi Arabia turned to after Iran’s blockade of the Strait of Hormuz. Saudi officials confirmed that the kingdom’s East-West oil pipeline, which carries crude to Red Sea export terminals, was temporarily shut down after a drone strike launched from Iraqi territory. If the pipeline remains offline, roughly 4% of global oil supply could be taken off the market. A wave of recent rocket and drone attacks by Yemen’s Houthi movement on southern Saudi Arabia has further amplified uncertainty over energy exports from the world’s largest oil producer.

    On Tuesday, Houthi forces struck civilian and economic sites across the Saudi cities of Abha, Khamis Mushait, Jizan and Najran, leaving 73 people injured including women and children. The attack marks a sharp escalation of the long-running Yemeni civil war, which reignited in July after nearly four years of relative calm under a UN-brokered ceasefire.

    Despite repeated U.S. reassurances that the strait is open for business, market analysts warn that upward pressure on oil prices will persist as long as Hormuz transit remains disrupted. “Despite American claims to the contrary, Hormuz is not under U.S. control, and oil is not flowing freely,” said Chris Beauchamp, chief market analyst at IG Group. Beauchamp explained that transits through the strait remain severely restricted, vessels continue to face attack risks, and Houthi strikes on energy infrastructure add an extra layer of uncertainty for global energy markets. “Near-month futures are still trading at a premium to spot prices, which reflects market expectations that supply disruptions will continue, putting additional pressure on the already fragile global economy,” he added.

    Christopher Haines, Global Head of Oil at Energy Aspects, also forecasts that crude prices will keep rising, pointing out that flows through the Strait of Hormuz remain drastically lower than pre-conflict levels, while global inventories that helped stabilize markets over the past six months have shrunk considerably. “The U.S. Strategic Petroleum Reserve has very little capacity to add additional supply now that planned releases have been completed… Meanwhile, China will not be able to cut back on crude purchases as it did this summer, as seasonal winter demand is ramping up,” Haines told Al Jazeera. “Crude buying has remained robust because refineries have to run at higher rates to produce the heating fuels the Northern Hemisphere needs for the cold season. We believe oil prices can continue climbing, because without the inventory buffers we had in previous months, prices will have to rise to cool demand.”

    Over the weekend, new security incidents reinforced the ongoing risk to transit. Early Sunday, the UK Maritime Trade Operations reported that a vessel was hit by an unknown projectile while transiting Hormuz. Then on Monday, Iran’s Islamic Revolutionary Guard Corps announced it had intercepted and destroyed an advanced U.S. MQ-1 drone flying over the strait.

    Diplomatic efforts to de-escalate the crisis have also hit a wall. A planned meeting between Gulf states and Iran in Oman, scheduled for Monday to discuss potential agreements on Hormuz transit, was postponed — a major setback to diplomatic efforts to end the six-month conflict. Iran said Monday that Saudi Arabia requested the postponement in response to recent events in Yemen. U.S. Energy Secretary Wright also poured cold water on hopes for a near-term diplomatic breakthrough, telling Bloomberg that “betting on a consensus agreement with Iran today is certainly not a good wager.”

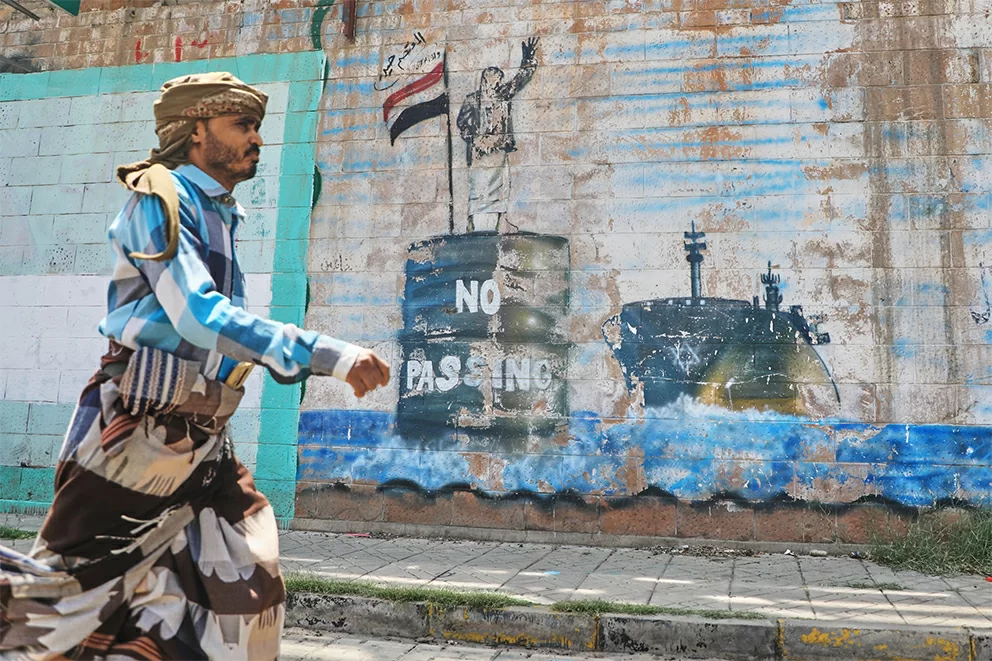
    Growing Houthi control over another critical global shipping chokepoint, the Bab al-Mandeb strait off Yemen’s western coast, is adding further upward pressure to oil prices, according to maritime experts. “The Bab al-Mandeb, which connects Asia to Europe, is now largely under Houthi control,” Abdul Khalique, head of the Liverpool John Moores University Maritime Centre, told Al Jazeera. After seizing the port of Mocha and the Hanish and Zuqar islands earlier this week, Iranian-aligned Houthi forces captured the strategically vital island of Perim (also called Mayyun) and the mainland town of Dhubab, giving the group effective control over Yemen’s entire Red Sea coastline.

    Khalique added that war risk insurance premiums for Hormuz transits have skyrocketed, jumping from roughly 0.25% of a vessel’s hull value before the war to between 3% and 10% today, depending on the vessel and route. “For a $100 million tanker, that works out to a war risk premium of $3 million to $10 million for a single transit, before adding coverage for cargo and additional freight costs,” he said. “The U.S. may have substantial military control over the theater of operations, but it has not restored the conditions needed for normal commercial shipping to resume. That gap is exactly why oil prices keep rising even as Washington declares victory.”

    With no diplomatic breakthrough on the horizon and multiple key chokepoints remain disrupted, Beauchamp says a return to the March 2024 price highs is only a matter of time. “With no party rushing to negotiate, it looks like oil prices will keep climbing, and a return to the March peaks is a question of when, not if,” he said.

  • Antigua and Barbuda Targets 1.5 Million Cruise Visitors Within Two Years

    Antigua and Barbuda Targets 1.5 Million Cruise Visitors Within Two Years

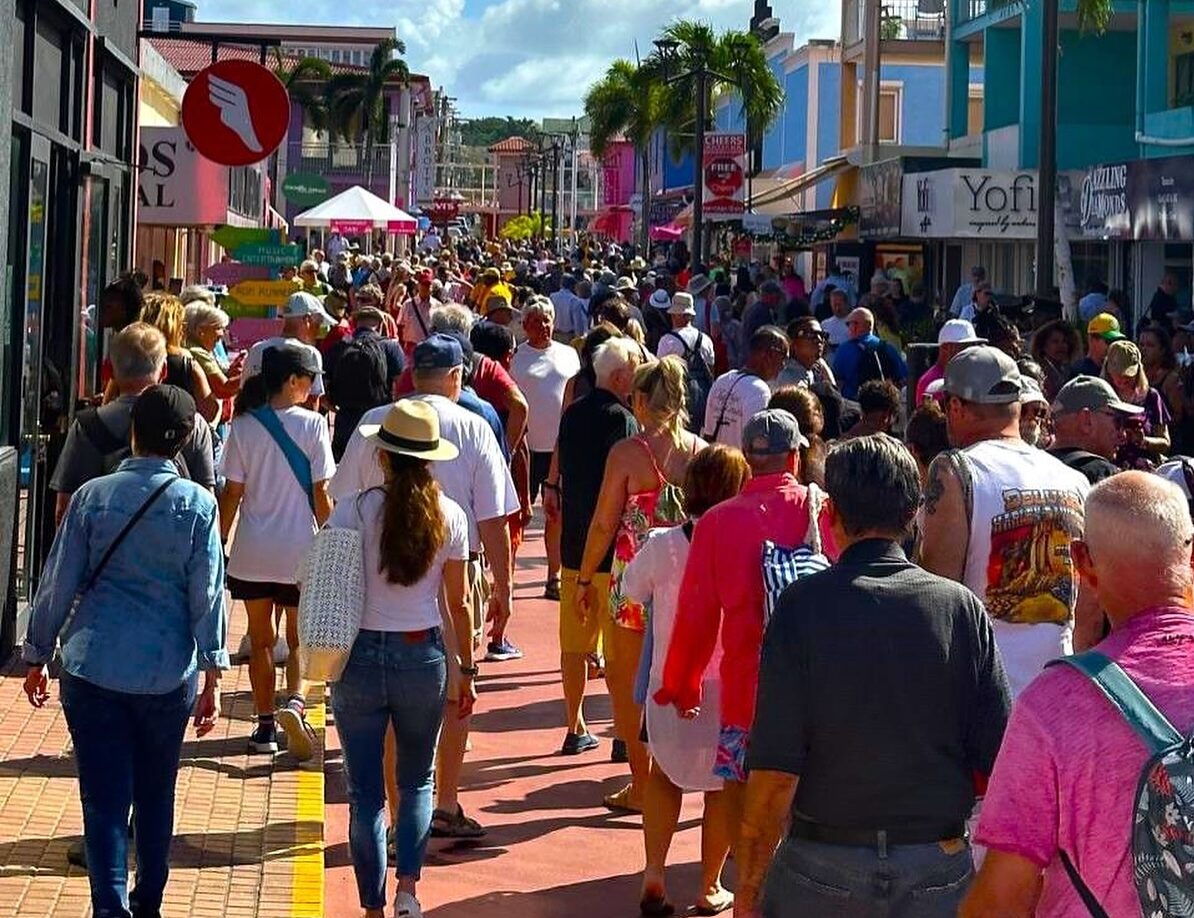
    ST. JOHN’S, Antigua and Barbuda — As the Caribbean nation accelerates upgrades to its cruise infrastructure and on-shore visitor experiences, Prime Minister Gaston Browne has unveiled an ambitious goal to draw roughly 1.5 million annual cruise ship visitors to Antigua and Barbuda over the next 24 months.

    When Browne’s administration first took office more than 10 years ago, the country welcomed just 500,000 cruise tourists annually, meaning the new target would represent a 200% jump in visitor volumes from that baseline. Browne shared the projection during his regular weekly broadcast to the public, emphasizing how far the country’s cruise sector has come in the past decade.

    Among the key developments poised to support this growth goal is the Upland Development project located on Newgate Street, a shoreside commercial space built specifically to cater to cruise passengers. Browne confirmed the project is in its final stages of completion and will be fully operational in time for the upcoming cruise season. The development will host 20 retail outlets, with a notable portion of the commercial space reserved exclusively for local small businesses, ensuring community members benefit directly from growing tourism demand.

    Browne highlighted the critical role of international partner Global Ports Holding in advancing the country’s cruise ambitions, noting the firm has poured significant capital into expanding and upgrading Antigua and Barbuda’s port infrastructure. That investment has transformed the country’s standing in the competitive Caribbean cruise market: just over a decade ago, Antigua and Barbuda was widely regarded as having one of the weakest cruise tourism offerings in the entire region. Today, it is gaining international recognition as a top-tier cruise destination and building the capacity to capture a much larger share of the regional market.

    Despite the clear optimism around the growth target, Browne did not release additional granular details to support the projection. He offered no specifics on projected numbers of ship calls, pre-confirmed passenger bookings from major cruise lines, or what additional large-scale infrastructure projects will need to be completed to handle a tripling of annual visitor volumes. Industry analysts note that hitting the 1.5 million target will hinge on several critical factors: sustained growth in the number of cruise ships choosing to include Antigua and Barbuda on their itineraries, sufficient port capacity to accommodate larger and more frequent vessel arrivals, and the country’s ability to scale up complementary services including ground transportation, guided tours, retail offerings, and hospitality staff to serve the sudden influx of passengers.

  • Antigua and Barbuda’s PM Accuses Local Banks Of Failing Borrowers with Conservative Lending

    Antigua and Barbuda’s PM Accuses Local Banks Of Failing Borrowers with Conservative Lending

    The prime minister of Antigua and Barbuda has publicly raised sharp criticisms against the nation’s domestic banking sector, arguing that excessively conservative lending approaches are leaving countless qualified borrowers locked out of access to critical capital. In a recent public address, the country’s leader highlighted that local financial institutions have drastically tightened their lending standards in recent months, adopting risk-aversion policies that go far beyond prudent financial management.

    This overly cautious stance, the prime minister claims, is creating unnecessary barriers for small business owners, aspiring homeowners, and entrepreneurs seeking funding to grow their ventures or cover unexpected expenses. Many borrowers who would have previously qualified for mortgages, small business loans, or personal lines of credit are now being rejected outright or offered terms with prohibitively high interest rates that put financing out of reach.

    The prime minister emphasized that this trend is not just harming individual borrowers—it is also dragging down broader economic growth across the twin-island nation. Restricted access to credit slows business expansion, suppresses job creation, and weakens the housing market, creating ripple effects that touch multiple sectors of the local economy. The head of government has indicated that he intends to convene urgent talks with banking industry leaders to address the issue, pushing for a reevaluation of current lending policies that balances the banks’ need for risk management with the economy’s demand for accessible, affordable credit. He called on financial institutions to find a middle ground that supports both financial stability and inclusive economic growth, warning that continued inaction could lead to prolonged stagnation for businesses and households alike.

  • IMF cautions Caribbean states as Middle East war drives up energy costs

    IMF cautions Caribbean states as Middle East war drives up energy costs

    Six months into an expanding Middle East conflict that has severely disrupted shipping through the Strait of Hormuz, one of the world’s most critical energy chokepoints, small oil-importing Caribbean island nations are facing mounting economic pressure that is stretching already tight government budgets to breaking point. The conflict, which has escalated beyond the initial US-Iran confrontation, has cut ship traffic through the key route to just 10 percent of pre-war levels, sending global energy, shipping and commodity prices soaring and creating cascading economic risks for vulnerable regional economies.

    With the exception of Guyana, which has recently grown into a major regional oil exporter, nearly all Caribbean nations rely almost entirely on imported fossil fuels to power their economies. Governments across the region have already rolled out emergency support programs to shield households and businesses from spiking energy and transport costs, but these interventions come at a steep fiscal cost. For St. Kitts and Nevis specifically, the energy shock overlaps with an additional hit from declining revenues from its flagship Citizenship by Investment (CBI) program, compounding the challenge for the federation’s policymakers.

    Against this fragile economic backdrop, the International Monetary Fund (IMF) is calling on Caribbean governments to adopt a carefully balanced approach that protects vulnerable populations while safeguarding their limited remaining fiscal capacity. In an exclusive comment to SKNVibes.com, an IMF spokesperson emphasized that targeted, temporary support for low-income and at-risk groups is far preferable to broad, universal price interventions that distort market signals and drain public resources.

    “Given limited fiscal buffers in many Caribbean countries, fiscal policy should prioritize protecting the most vulnerable through targeted and temporary measures, while avoiding broad-based interventions that distort price signals,” the spokesperson stated. The institution also warned regional governments against pushing back needed fiscal consolidation efforts, noting that rebuilding fiscal buffers is a critical priority amid already high public debt, persistent global uncertainty, and the constant risk of climate-fueled natural disasters that require emergency response capacity. Strengthening core fiscal frameworks, boosting domestic revenue mobilization, and improving the efficiency of public spending would, the IMF argues, leave regional governments better positioned to absorb future external shocks.

    The economic ripple effects of the Middle East conflict extend far beyond energy prices alone. Higher shipping and transport costs have pushed up prices for imported food and other essential consumer goods, exacerbating cost-of-living pressures for households across the region. Brent crude prices have remained consistently elevated, a persistent drag on economies that import nearly all their energy needs.

    The IMF has confirmed it stands ready to support Caribbean member states navigating these headwinds through policy guidance, institutional capacity building, and targeted financing where appropriate. As a recent example, the Fund’s Executive Board approved a 36-month precautionary Stand-By Arrangement worth $257 million for Barbados in June 2026 to help the country manage external economic shocks.

    While the global economy has demonstrated unexpected resilience in the face of the ongoing energy shock, IMF officials stress that impacts are distributed very unevenly across countries, with energy-importing small states like those in the Caribbean bearing the brunt of the crisis. Speaking at a September press briefing, IMF Director of Communications Julie Kozack noted that the global economy has “weathered the shocks, the energy shock in particular, better than feared,” keeping 2026 global growth on track to hit around 3 percent. Kozack attributed this resilience to a range of policy adjustments, including countries drawing down strategic oil and gas reserves, shifting to alternative energy suppliers, and implementing targeted demand reduction measures.

    Kozack also outlined the competing forces currently shaping the global economic outlook, saying the world economy is being pulled in two opposing directions. On one hand, the ongoing negative supply shock driven by elevated energy and broader commodity prices, including fertilizer and food, continues to weigh on growth and push up costs. On the other hand, a positive demand shock driven by the fast-expanding AI technology cycle is supporting growth in major advanced and emerging economies.

    Despite the overall global resilience, the energy shock is far from over, Kozack warned. Elevated oil and gas prices have persisted, and refined fuel products including diesel and jet fuel remain far more expensive than pre-conflict levels. She added that while drawing down strategic reserves has helped ease near-term price pressures, those reserves will eventually need to be replenished, creating future upward pressure on prices. Additionally, growing energy demand from the rapid expansion of AI technology and the approaching winter in the Northern Hemisphere are expected to place further strain on global energy markets in the coming months.

    Beyond the energy crisis, Kozack identified two other major systemic risks facing the global economy: soaring public debt and stalled disinflation. Global public debt now stands at nearly 100 percent of global GDP, its highest level since the end of World War II, and the IMF projects it will continue to climb in coming years. The disinflation process that followed the 2022 global cost-of-living crisis has now stalled, leading the Fund to revise its 2026 global headline inflation forecast upward to 4.7 percent in its July World Economic Outlook update. While core inflation projections remain largely unchanged and long-term inflation expectations remain anchored, short-term expectations have risen over the past year, adding to policy uncertainty.

    For Caribbean governments, the overlapping challenges create a complex policy balancing act: policymakers must shield consumers from the immediate impact of spiking energy and food costs, while maintaining long-term fiscal stability and building resilience to withstand further potential external shocks.

  • Reversing ‘draconian’ changes to Companies Act makes SVG more attractive –– PM

    Reversing ‘draconian’ changes to Companies Act makes SVG more attractive –– PM

    St. Vincent and the Grenadines’ Parliament has greenlit a sweeping set of amendments to the national Companies Act, a reform package Prime Minister Godwin Friday says will roll back overly harsh 2016 regulatory changes, boost the country’s investment appeal, and uphold the nation’s core economic interests. Introducing the Companies (Amendment) Bill 2026, Friday framed the new legislation as a targeted correction for unintended economic damage caused by the previous Unity Labour Party administration’s 2016 reform package.

    According to Friday, the 2016 amendments imposed unreasonably restrictive requirements and crippling financial penalties on both domestic and foreign companies, particularly external firms seeking to invest in or own land within the country. He added that the former Ralph Gonsalves-led government brought the 2016 law to a parliamentary vote without meaningful consultation with business and industry stakeholders. Partial provisions of that 2016 law were already repealed in August, when parliament passed an earlier revision without opposition backing.

    While Friday acknowledged that the 2016 reform was originally intended to strengthen regulatory oversight and curb documented abuses, he argued that its actual outcome was to impose onerous operational conditions on fully legitimate businesses, drive away much-needed foreign direct investment, and erode St. Vincent and the Grenadines (SVG)’s competitiveness in regional and global markets.

    The new reforms form a core plank of the government’s broader economic strategy to leverage both domestic and foreign private capital to pull the country out of its ongoing debt crisis and expand inclusive economic opportunity for citizens. SVG currently carries EC$3.5 billion in public debt, equal to 113% of the country’s annual GDP, with 40 cents of every dollar of government revenue allocated to debt servicing. With public finances under severe strain, Friday noted that the state can no longer act as the primary driver of national economic growth. Instead, his administration’s policy prioritizes liberalizing private capital and building a supportive, attractive business environment across SVG.

    “We are committed to stimulating growth in the private sector because it is only through growth in the productive sectors that we can really accelerate the development of our economy, grow our way out of the debt situation that we are in currently, and… provide opportunities for our people,” Friday told parliament. “The private sector is the engine of growth, not government. My administration is not here to compete against the private sector, whether it’s domestic or foreign, and we do not begrudge anybody making money — because if they don’t make money, they won’t invest.”

    Linking the new bill to the pro-investment message he delivered during an official visit to Taiwan in August, Friday reaffirmed that “SVG is open for business.” He said the legislative changes are designed to send a clear, consistent signal to both domestic and global investors that the country welcomes credible investment, including from external companies seeking to own land or operate commercial activities within its borders.

    A centerpiece of the 2016 amendments that the new reform targets was a tangled web of registration requirements that far outpaced reasonable regional standards. The most controversial rule mandated that not only must an external company that owns land in SVG register locally, every parent company shareholder in that firm’s ownership chain was also required to register as an external company in SVG — even if that shareholder entity had no actual business operations in the country beyond indirect ownership. By striking this requirement from the books, the new bill eliminates unnecessary red tape, cuts administrative burdens, and makes external corporate ownership of property and investment far more attractive to international players.

    Friday explained that in practice, the 2016 rules led legal advisors to stop recommending corporate ownership structures for foreign investors, instead pushing individuals to hold land in their personal names. This limited the use of legitimate corporate investment vehicles and directly weakened SVG’s competitiveness as a Caribbean investment hub.

    Even more damaging, Friday said, were the exorbitant fees and penalties the 2016 regime imposed that no other Caribbean jurisdiction charged, especially for firms that missed registration deadlines or failed to update corporate information on time. Under the original 2016 rules, an unregistered foreign company operating in SVG faced a fine of EC$350 per day for every day it remained unregistered — a penalty structure Friday called “outside the pale” of reasonable regulatory practice. Firms could quickly accumulate enormous penalty sums through no malicious intent, he noted, often due to administrative delays, poor advice, or simple tardiness, pushing accumulated penalties to levels that made investors question whether it was worth maintaining operations in SVG at all.

    The 2026 reform replaces that daily penalty structure with a capped system: a EC$135 monthly fine with a total maximum penalty of roughly EC$27,000. Friday described the new structure as reasonable, arguing it will encourage voluntary compliance rather than driving companies away from the jurisdiction. Similarly, the original EC$100 daily penalty for late filing of updates to “fundamental changes” such as corporate name changes, director appointments, or revised corporate objectives will be replaced with a EC$50 monthly penalty, alongside extending the filing window from 30 to 60 days to accommodate the practical delays of cross-border document filing and certification. Friday emphasized that penalties are meant to encourage compliance, not generate government revenue, a core principle that guided the new penalty structure.

    The bill also introduces a six-month amnesty program designed to regularize the status of companies that have accumulated unpaid late fees and penalties, replacing the previous opaque system of ad-hoc cabinet discretion with a transparent, equal-access framework open to all qualifying companies. Under the amnesty, both local and external companies with outstanding charges from late annual returns or fundamental change filings can settle their status by paying just 50% of their total accumulated debt, with that payment counted as full settlement. Companies that decline to take advantage of the amnesty will remain liable for 100% of their outstanding penalties and will not be eligible for future discretionary relief from cabinet.

    Friday noted that the program will allow hundreds of companies that have fallen behind on filings — in some cases carrying hundreds of thousands of dollars in accumulated penalties — to return to good standing, resume operations, and contribute to SVG’s economic growth. The amnesty will also generate government revenue that would otherwise likely go uncollected, he said, noting “half a loaf is better than none.” At the same time, it clears debilitating legacy liabilities that have kept companies from expanding, hiring new employees, and operating as active contributors to local communities.

    Friday stressed that the reforms do not amount to a regulatory free-for-all, nor do they abandon the rule of law. Instead, the changes are intentionally structured to be pro-business without sacrificing critical regulatory safeguards. “This is really… the environment in which we’re creating. There’s no hostility. There’s no seeking to be punitive. What we are wanting to do, we want business to do business. We want the country to free up. We want people to feel the country light again,” he said. The government will remain vigilant in upholding regulatory standards and protecting SVG’s national interests, he added, balancing pro-investment policy with the state’s responsibility to secure tax revenues, job growth, and broad economic benefits for citizens. The goal of regulation, he argued, should be to enable legitimate economic activity rather than smother it.

    Not all lawmakers support the reforms, however. Opposition Leader Ralph Gonsalves, who led the previous administration that passed the 2016 amendments, has denounced the 2026 bill as “a bad bill.” He accused the current government of sacrificing critical public revenue and weakening regulatory safeguards to benefit non-compliant external companies and a small group of local lawyers who, he claims, failed to fulfill their professional duties to foreign clients. Gonsalves, a trained lawyer, argued that the reforms will disproportionately benefit non-compliant external companies that owe millions of dollars in accumulated penalties, as well as local attorneys who collected fees from clients but never completed required corporate filings. He also warned that the scale of fee reductions — which he calculates reach 98% to 99% in some cases — is arbitrary, illogical, and creates dangerous regulatory precedent.
  • Ex-CEO Cox threatens legal action

    Ex-CEO Cox threatens legal action

    A high-stakes corporate dispute has emerged at state-owned telecommunications giant Telecommunications Services of Trinidad and Tobago (TSTT), as former acting chief executive officer Keino Cox is moving forward with planned legal action against the company. Cox alleges the TSTT board retaliated against him after he flagged widespread potential corporate governance violations by top company officials.

    Cox’s legal team, led by prominent Senior Counsel Ramesh Lawrence Maharaj and operating out of the RLM & Co law firm, delivered a formal pre-action protocol letter to TSTT on Friday. The correspondence sets a strict seven-day deadline for the telecom provider to deliver a substantive response to the claims, failing which Cox will initiate formal litigation in the appropriate court.

    According to the legal documents, Cox held the post of acting CEO for 12 months starting July 21, 2025, via two consecutive six-month appointments. His legal team emphasizes that his tenure delivered exceptional financial results for the company: profit after tax surged 103% to $214 million, Earnings Before Interest, Taxes, Depreciation and Amortisation (EBITDA) jumped by $135 million to reach $910 million, and the company restored $35 million in positive retained earnings. Beyond financial performance, the letter highlights the successful expansion of the company’s community outreach programs, including the popular Future Leaders Internship Programme that provides opportunities for young local workers.

    Shortly after Cox raised his concerns over internal governance, the board placed him on immediate administrative leave and declined to renew his acting CEO appointment. The legal team firmly rejects the unstated insinuation that Cox’s removal was connected to any improper conduct related to TSTT’s Humming Bird call-centre contract. The letter clarifies that the procurement process for that contract followed all required protocols: the opportunity was publicly advertised, evaluations were conducted by an independent third-party committee, and the final contract was formally approved by TSTT’s own Procurement and Disposal Advisory Committee.

    Instead, Cox’s attorneys directly tie his removal to the governance concerns he brought forward to the board, specifically focusing on a proposed $470 million bond refinancing plan and the conduct of three top TSTT leaders: chairman Kern Dass, corporate secretary Viveka Pargass, and acting chief financial officer Robert Panker.

    The legal correspondence outlines that TSTT’s independent financial advisor, Ernst & Young, explicitly recommended against pursuing the refinancing in July and August, projecting that delaying the transaction until October would cut between $7 million and $8 million in unnecessary redemption fees. Despite this formal professional advice, a board memorandum was circulated advancing the July refinancing timeline, and Cox raised formal objections to the flawed process during a full board meeting.

    Beyond the refinancing dispute, Cox also flagged a series of concerns regarding corporate secretary Pargass, including allegations that she failed to properly disclose outside secondary employment that creates a potential conflict of interest, caused costly delays in securing TSTT’s mandatory Money Lender’s Licence, and authorized new hires outside the company’s official hiring protocols.

    The letter accuses the TSTT board of choosing to retaliate against the whistleblower rather than launching a full independent investigation into the serious governance concerns he reported. It formally notifies Dass, all sitting directors, and Pargass that Cox intends to refer all evidence of potential misconduct in public office to the Director of Public Prosecutions (DPP) or other relevant regulatory bodies if his claims are not resolved appropriately.

    Cox’s legal team also adds that unnamed TSTT officials have made damaging public statements that falsely tie Cox to misconduct in the Humming Bird contract matter, irreparably harming his professional reputation. In addition to a formal response to his claims, the legal team is demanding full disclosure of the exact reasons for the non-renewal of Cox’s appointment, complete details of any formal allegations against him, and all supporting documentation that TSTT relied on to make its decision to remove him.

    Notably, even amid the ongoing dispute, Cox has indicated he remains open to returning to his role as acting CEO, provided that appropriate safeguards are put in place to prevent further retaliation and the company compensates him for the financial losses and reputational damage he has sustained to date.

  • Local Entrepreneurs Invited to Pitch Business Ideas to Commonwealth Investors

    Local Entrepreneurs Invited to Pitch Business Ideas to Commonwealth Investors

    A new initiative is connecting emerging local business founders with a network of seasoned investment professionals spanning the Commonwealth bloc, creating a rare pathway for early-stage ventures to secure critical funding and strategic partnerships. The program, organized jointly by local business development agencies and Commonwealth trade bodies, calls on innovators across all sectors—from sustainable agriculture to fintech and digital services—to submit their business concepts for a chance to present directly to a panel of active Commonwealth investors.

    Organizers note that the initiative addresses a long-standing gap for many small and medium-sized enterprises (SMEs), which often struggle to access early-stage capital beyond local banking networks. Unlike traditional funding rounds, the pitch event is designed to foster long-term collaboration, with investors offering not just capital but also industry connections, mentorship, and access to expanded regional markets across the Commonwealth’s 56 member nations.

    Eligible entrepreneurs must complete their applications by a specified upcoming deadline, with shortlisted candidates invited to deliver in-person or virtual pitches later this quarter. Selection criteria prioritize scalable business models, positive community impact, and innovative solutions to shared regional challenges, ranging from climate adaptation to digital inclusion. For many emerging local founders, this opportunity represents more than just funding—it is a chance to turn local ideas into globally competitive businesses while strengthening economic ties across the Commonwealth network.

  • Saudi-Arabië sluit East-West pijpleiding na aanval; Houthi’s versterken controle over Rode Zee

    Saudi-Arabië sluit East-West pijpleiding na aanval; Houthi’s versterken controle over Rode Zee

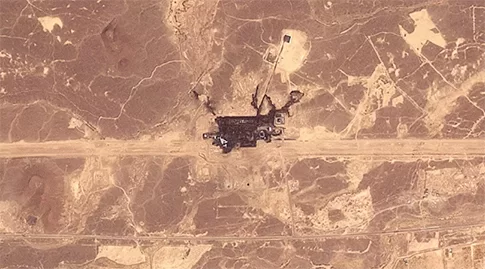
    A dramatic escalation of regional unrest in the Middle East has sent shockwaves through global energy markets, after Saudi Arabia ordered an emergency temporary shutdown of its critical East-West crude oil pipeline on Saturday, triggered by a damaging drone attack.\n\nSpanning 1,200 kilometers across the Arabian Peninsula, the East-West pipeline serves as a linchpin of global oil exports from the Middle East, a role that has grown increasingly vital in recent months as the Strait of Hormuz, another key energy chokepoint, has been largely rendered unusable by ongoing regional conflict. Satellite imagery captured by Planet Labs PBC on September 11, 2026, shows visible damage to infrastructure along the pipeline’s route, located southeast of Medina. The assault left multiple casualties and destroyed multiple structures, including a local mosque in the Jazan region.\n\nBoth Baghdad and Riyadh have pinned responsibility for the attack on Iran-backed militias operating within Iraqi territory. In response to the security breach, Iraqi military officials have dismissed a senior regional military commander amid the fallout.\n\nThe pipeline shutdown has immediately disrupted global oil flows. The route carries 4 to 5 million barrels of crude daily, accounting for roughly 4% to 5% of total global oil supply. Saudi Arabia’s ability to maintain consistent export volumes is now under threat, piling unprecedented pressure on already tight energy markets worldwide.\n\nCompounding the crisis, Yemen’s Houthi rebels have expanded their military control over key Red Sea shipping lanes by seizing the strategic island of Perim, which sits at the heart of the Bab el-Mandeb Strait—commonly known as the “Gate of Tears,” another of the world’s most critical chokepoints for global oil trade. The capture significantly strengthens the Houthi’s ability to disrupt maritime traffic in the region.\n\nGrowing insecurity around major energy transit routes has already triggered sharp volatility in energy pricing. Global crude benchmarks have risen steeply over the past week, while diesel prices in the United States have surged to an all-time record, topping $6 per gallon.\n\nIn response to the expanding threat, Saudi Arabia has formally requested direct military support from the United States to counter Houthi advances. U.S. President Donald Trump confirmed he has held discussions with Saudi Crown Prince Mohammed bin Salman, but clarified that Washington will not deploy direct military intervention at this stage. Instead, the U.S. will provide intelligence sharing support to Riyadh. Separately, Houthi representatives confirmed they have reached out to the U.S. government to request that Washington avoid direct involvement in the conflict.

  • BHTA chairman champions Tourism 3.0

    BHTA chairman champions Tourism 3.0

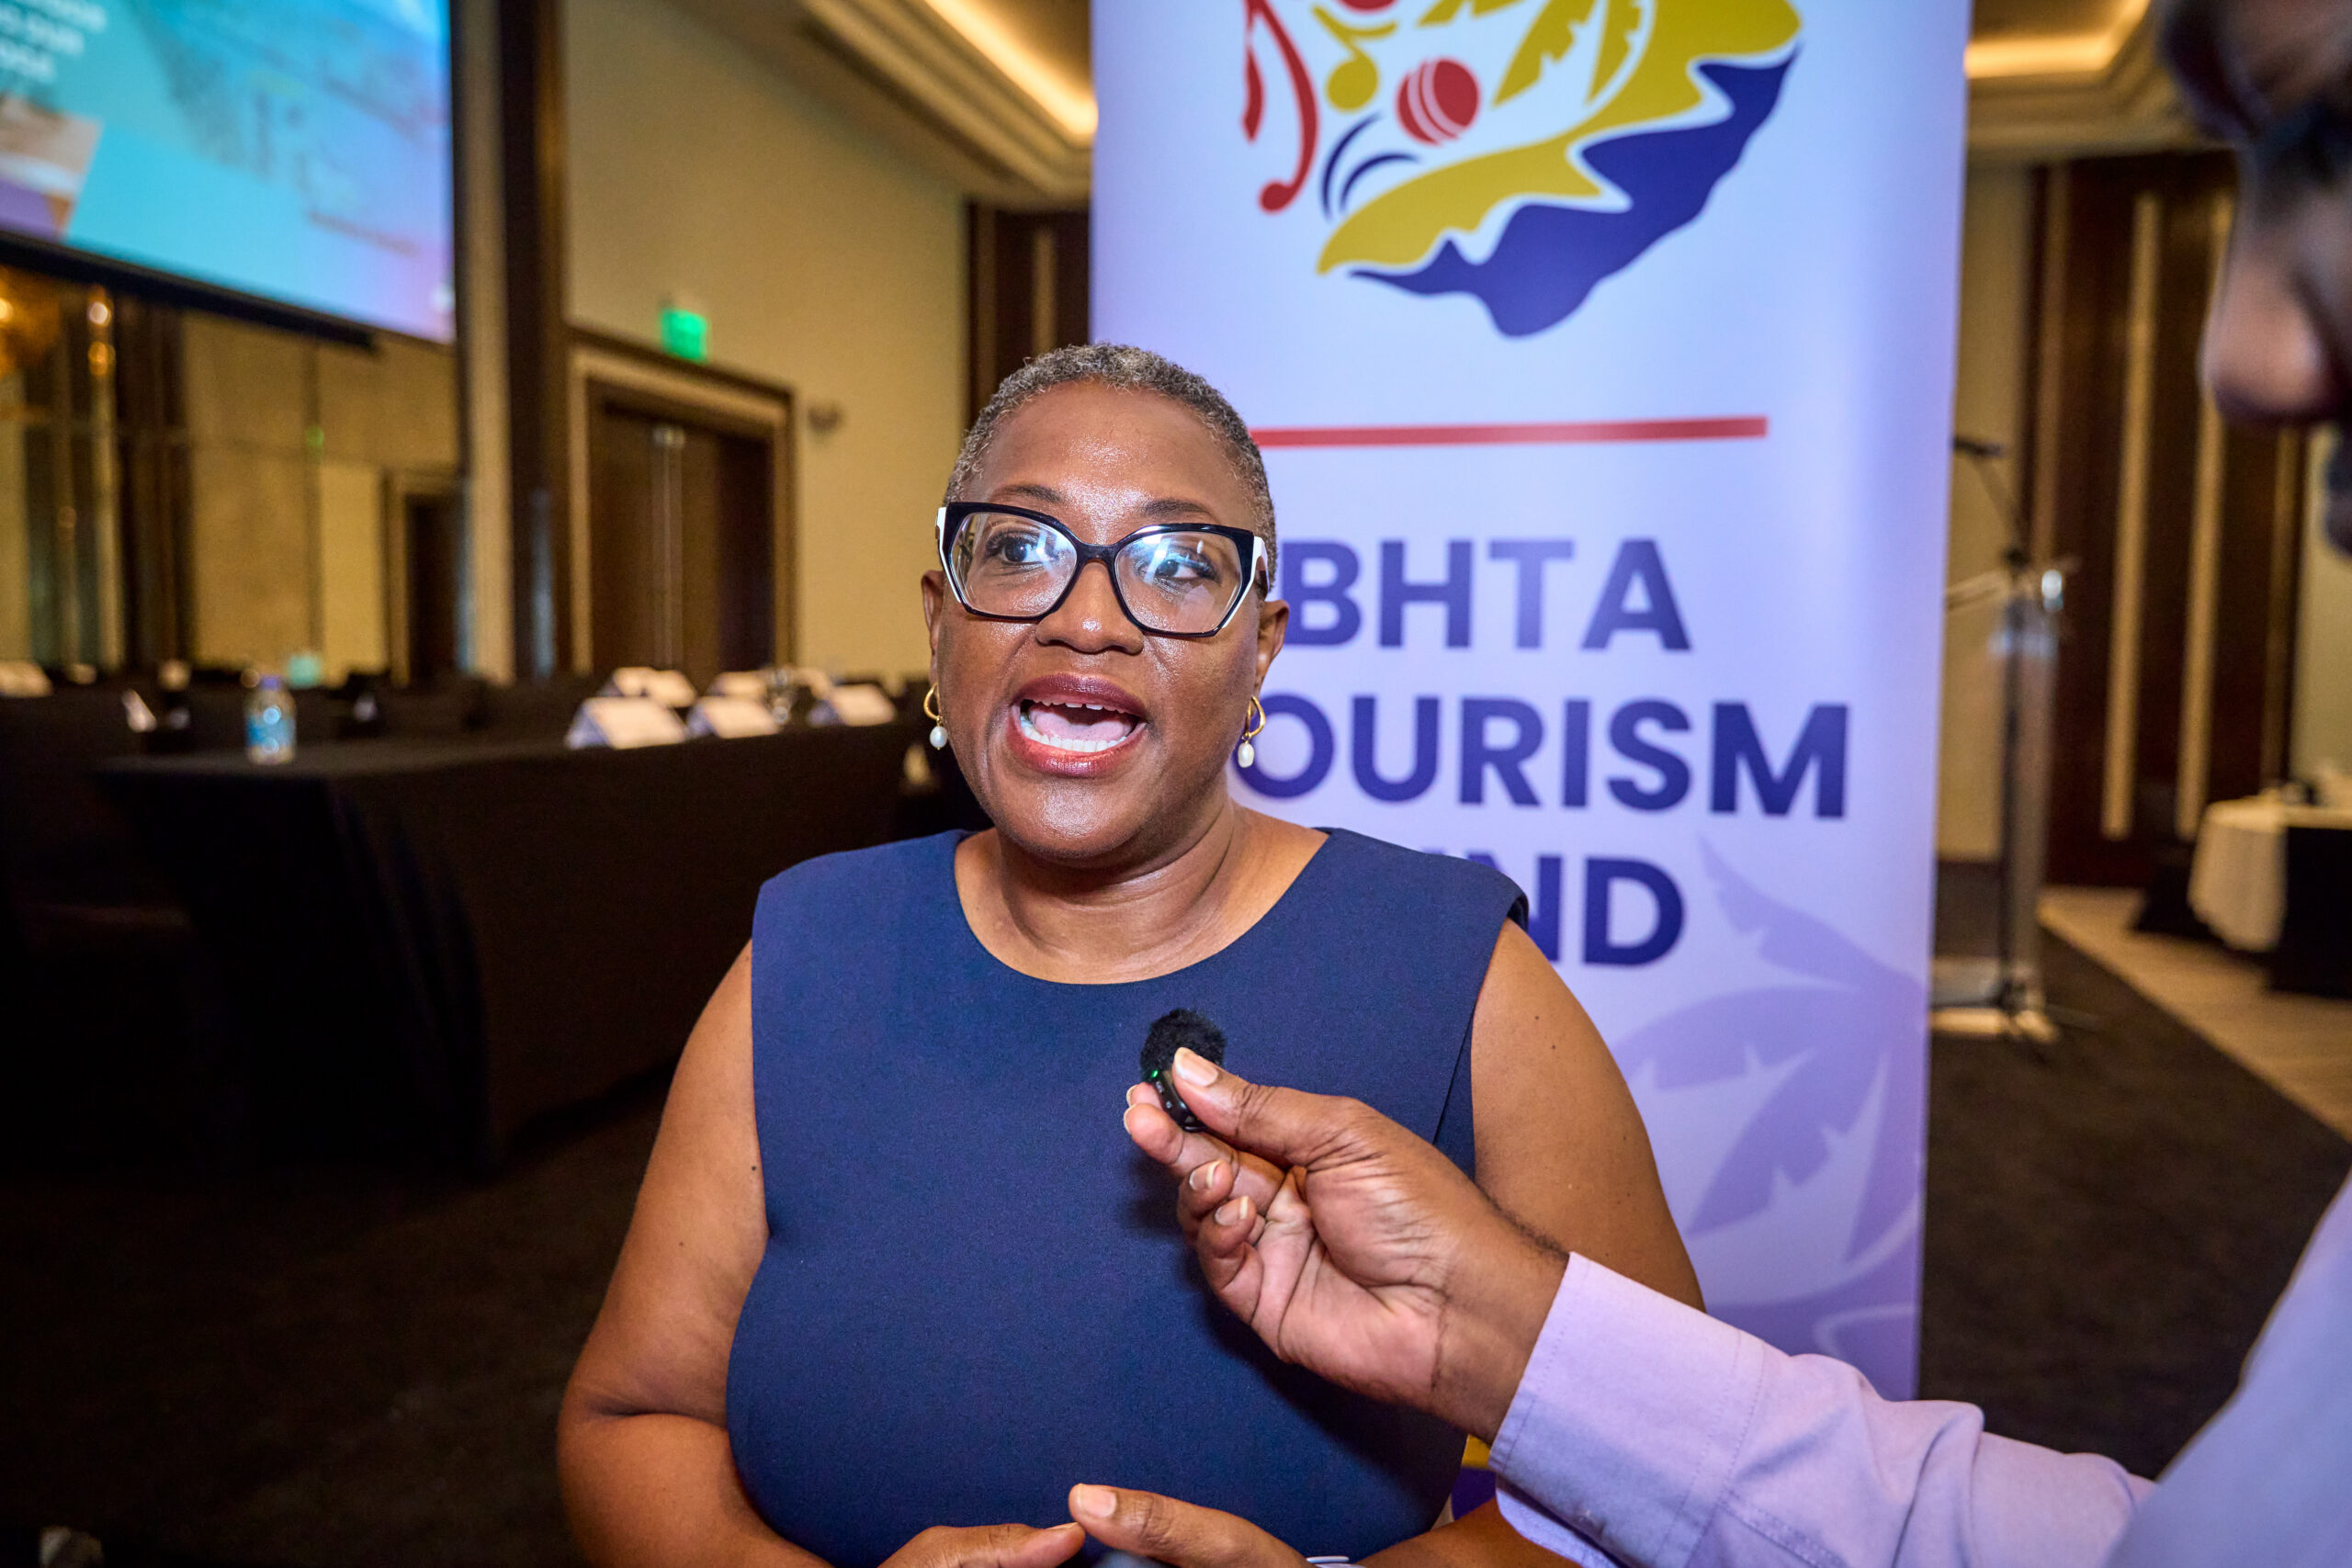
    Barbados’ tourism industry stands at a pivotal crossroads, as the head of the island nation’s leading hospitality industry body pushes for a fundamental rethinking of how the sector measures success. Kelly-Ann Payne, Chairman of the Barbados Hotel and Tourism Association (BHTA), is urging the country’s top tourism stakeholders to move beyond the longstanding metric of counting arriving visitor numbers, and instead prioritize quantifying the tangible value that tourism delivers to local communities and the broader Barbadian economy.

    Despite facing cutthroat global competition in the international leisure and travel space, Payne acknowledged that Barbados has made solid progress in expanding and diversifying its source markets for international visitors. In the first half of 2026, arrivals from Canada jumped 13.7% year-over-year, while visitor numbers from European markets grew an even stronger 20%, signaling that the island’s diversification strategy is gaining traction.

    Even with these positive volume gains, Payne argues that the next era of the industry, which she has labeled Tourism 3.0, must center on delivering shared, long-term benefits to Barbadian citizens rather than chasing ever-increasing visitor counts. “The future of tourism cannot be measured solely by growth in visitor numbers. The future must be measured by growth in value,” Payne stated, emphasizing that deeper integration between tourism and other key domestic sectors—including local agriculture, manufacturing, and the creative economy—will be critical to unlocking that broader value. Stronger cross-sector links would keep more tourism revenue within Barbados, supporting small local businesses and reducing reliance on imported goods and services for the hospitality industry.

    Payne shared these remarks during the BHTA’s most recent third quarterly general meeting, where she also highlighted positive developments in air access to the island. Grantley Adams International Airport, Barbados’ primary international gateway, is projected to have over 1.6 million incoming air seats available to passengers by August 2027. Flagship UK carrier British Airways alone is set to increase its capacity to the island by more than 71%, a boost that will open the door to more visitors from key European markets. That said, Payne warned that translating expanded air access into sustainable, widespread economic gains depends on strategic investment in the sector’s workforce.

    “Tourism cannot thrive without talent and talent cannot thrive without opportunity,” Payne said, calling on industry leaders and policymakers to adopt data-driven, evidence-based workforce planning to tackle persistent recruitment and employee retention challenges that have plagued the Barbadian tourism sector in recent years.

    In other updates from the meeting, Payne celebrated a recent milestone: the signing of a new Memorandum of Agreement with the Barbados Workers’ Union, which is expected to bring greater labor stability to the sector for both hotel employers and frontline workers. On the policy advocacy front, Payne reaffirmed the BHTA’s firm opposition to controversial pricing practices by online travel giant Booking.com, specifically the company’s policy of charging commissions on government-mandated taxes and statutory levies. The BHTA argues that these funds are rightfully public revenue owed to the Barbadian government, and do not qualify as part of hotel revenue that should be subject to third-party commission fees.