分类: business

  • Diaspora-investeringen in Suriname centraal tijdens bijeenkomst in Nederland

    Diaspora-investeringen in Suriname centraal tijdens bijeenkomst in Nederland

    A new collaborative initiative is opening up fresh financing pathways for Surinamese nationals living in the Netherlands who aim to invest in property back home. During the “Building, Renting, Housing and Investing in Suriname” event held Friday in Hoofddorp, the Surinaamse Postspaarbank (SPSB) and Sur Estate Group of Companies signed a formal partnership agreement designed to drive diaspora investment into Suriname’s real estate sector.

    Organized jointly by Sur Estate Group of Companies and the Diaspora Instituut Nederland (DIN), the in-person gathering brought together roughly 50 diaspora entrepreneurs, prospective investors and other stakeholders with an interest in Suriname’s property market. This event served as a follow-up to a well-attended webinar hosted earlier this year, which saw overwhelming interest from the Surinamese diaspora community based in Europe.

    Suriname’s ambassador to the Netherlands Ricardo Panka attended the event, where attendees discussed the wide range of opportunities for investment, entrepreneurship, infrastructure development and residential expansion across Suriname. Through a series of expert presentations and interactive roundtable discussions, participants covered key topics ranging from large-scale real estate development and rental market opportunities to entrepreneurship support, tax regulation and compliance, and modern construction technical standards.

    The highlight of the one-day gathering was the official signing of the partnership between SPSB and Sur Estate Group. The agreement paves the way for the launch of the Diaspora Housing Program, a tailored financing initiative created exclusively for Surinamese people living abroad who want to invest in residential and commercial real estate projects in their home country.

    According to the program’s founders, the initiative is intended to deepen the Surinamese diaspora’s engagement with the country’s ongoing economic development. The program will prioritize support for residential construction and broader real estate projects, with key developments already planned in Suriname’s Wanica District.

    During his opening remarks at the event, Ambassador Panka emphasized that prospective investors must prioritize thorough preparation and market research before committing capital to Suriname. He encouraged all interested members of the diaspora to seek out reliable, up-to-date information and take deliberate, concrete steps to pursue viable investment opportunities.

    Event organizers also announced that a cohort of participating investors and stakeholders will travel to Suriname in June to attend the annual Suriname Energy, Oil & Gas Summit (SEOGS), where they will have the opportunity to evaluate on-the-ground investment opportunities and inspect active projects across the country.

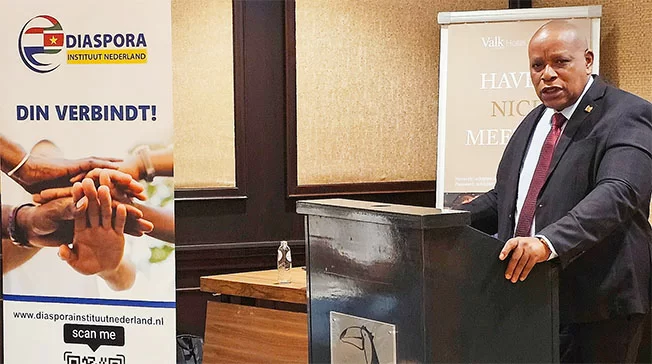
    DIN chair John Brewster noted that the role of the global Surinamese diaspora has undergone a notable shift in recent years, moving away from traditional community-focused engagement toward active, large-scale economic participation. Brewster highlighted that this shifting dynamic creates new openings for sustainable long-term investment that can drive inclusive, continued economic growth across Suriname.
  • Note on Monetary Policy, BRH 2nd Fiscal Quarter 2025-2026

    Note on Monetary Policy, BRH 2nd Fiscal Quarter 2025-2026

    Against a backdrop of soaring global energy costs, intensifying geopolitical friction, persistent inflation, and widening fiscal gaps, the Bank of the Republic of Haiti (BRH) has released its highly anticipated second quarter monetary policy note for fiscal year 2025-2026, laying out a comprehensive snapshot of recent economic performance, key policy interventions to stabilize macroeconomic and financial conditions, and forward-looking projections for the months ahead.

    Global and regional economic projections from the International Monetary Fund, published in April 2026, frame the challenging global context in which Haiti’s economy operates. The IMF estimates global growth will hit 3.1% for the full year 2026. The United States is projected to grow by 2%, with inflation holding at 3.3%, unemployment at 4.3%, and benchmark policy rates ranging between 3.50% and 3.75%. The Eurozone faces far slower growth, penciled in at just 0.1%, with 2.6% inflation, 6.2% unemployment, and a 2% deposit facility rate. Across Latin America and the Caribbean, regional growth is projected at 2.2%, with neighboring Dominican Republic outperforming at 4% annual growth, 4.63% inflation, and a 5.25% policy rate.

    Domestically, Haiti’s economic landscape remains deeply troubled, the report confirms. Economic activity contracted by 1.1% in the first quarter of the current fiscal year, with all three major sectors posting underperformance: the primary sector shrank by 4%, the secondary sector by 2.3%, and the tertiary sector by 0.3%. The ongoing security crisis has driven widespread displacement, with nearly 1.45 million Haitians registered as displaced persons as of February 24, 2026. Between March and June 2026, an estimated 5.83 million Haitians face acute food insecurity. Annual inflation hit 20.6% in March 2026, exacerbated by a government-announced fuel price increase implemented on March 31 of that year.

    On the public finance front, BRH data shows the government collected 54.7 billion Gourdes in tax revenue over the quarter, with total available resources reaching 102.8 billion Gourdes. Net treasury bill issuance hit 40.9 billion Gourdes, while recorded budget expenditures totaled 61.3 billion Gourdes. Overall total disbursements reached 113.7 billion Gourdes, leaving a significant overall budget gap. A portion of this deficit was financed via 19.12 billion Gourdes in advances from the BRH. In the external sector, the country recorded $160.83 million in exports against $1.19 billion in imports, resulting in a trade deficit of $1.03 billion for the quarter.

    Looking ahead, BRH warns that Haiti’s economic trajectory remains vulnerable to a cascade of overlapping shocks, rooted in both the nation’s ongoing precarious security situation and the potential spillover effects from escalating geopolitical conflicts in the Middle East. Against a backdrop of global oil market disruptions, the government’s pump price adjustment—while slightly revised downward in early May 2026, after the end of the quarter under review—still risks further stoking inflationary pressures. Higher fuel costs drive up transportation expenses, which flow directly to higher prices for nearly all other consumer goods and services across the economy. Additionally, ongoing volatility in the Middle East threatens to increase Haiti’s total oil import bill, putting additional downward pressure on the country’s already strained foreign exchange market.

    In response to deepening shocks and persistent economic uncertainty, BRH has committed to rolling out targeted policy measures to preserve core economic activity, aligned with its institutional mandate. The central bank’s policy priorities will focus on restoring macroeconomic balance and safeguarding the stability of Haiti’s financial system. To support these efforts, the International Monetary Fund’s recent extension of the Staff-Monitored Program (SMP) through June 2027 will provide critical institutional backing, creating a credible policy framework and ensuring continuity of disciplined macroeconomic management.

    Beyond short-term stabilization, BRH has reaffirmed its long-term commitment to revitalizing Haiti’s domestic productive sector through targeted support mechanisms for strategic industries. Key initiatives include a restructuring of banking services to expand access to financial inclusion for residents and businesses in provincial cities, and scaled-up support for Haitian small and medium-sized enterprises (SMEs), particularly those owned and led by women. The Booster PME III program stands as a flagship effort to deliver on this commitment.

  • Sea Bridge Ferries Raises Fares Effective June 1

    Sea Bridge Ferries Raises Fares Effective June 1

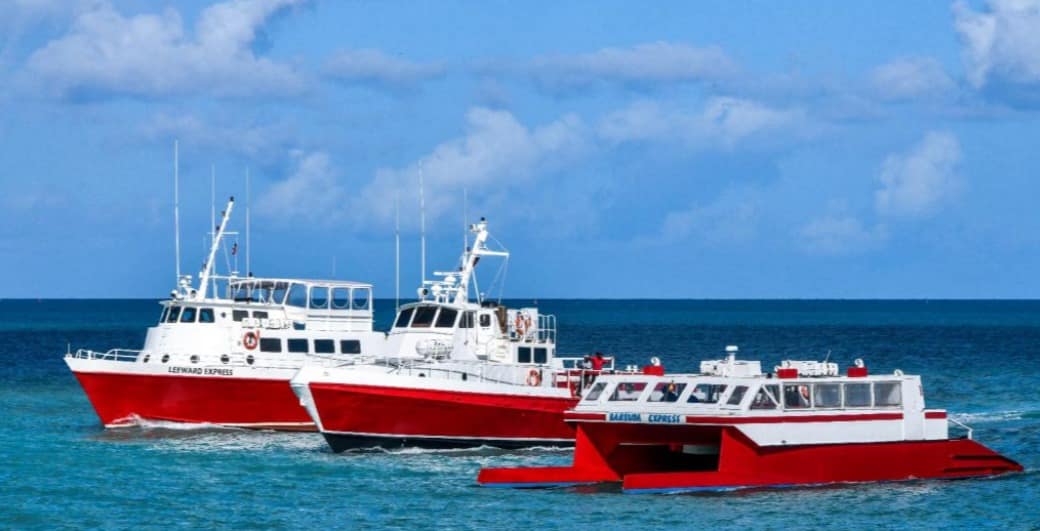
    After holding ticket prices steady for six years, regional ferry operator Sea Bridge Ferries has officially announced that it will implement a fare adjustment starting June 1, 2026, a change driven by unrelenting upward pressure on fuel and general operational expenses.

    In a public statement released to customers this week, the company confirmed that it has not modified its pricing structure since 2020, choosing to absorb the bulk of rising industry costs internally over the past half-decade to keep its cross-water service accessible and affordable for regular commuters, leisure travelers, and commercial clients alike. But according to the announcement, ongoing volatility in global energy markets paired with steady increases in other overhead costs from labor to vessel maintenance have finally made a price adjustment unavoidable.

    Under the newly revised pricing framework, a single one-way passenger ticket will be priced at $155, broken down into a $140 base fare and a separate $15 fuel surcharge to offset energy costs. For passengers opting for round-trip travel, the total cost will come to $275, consisting of a $250 base fare and a $25 fuel surcharge.

    Sea Bridge Ferries emphasized that the decision to raise fares is partially rooted in broad global supply chain disruptions and shifting market conditions that have pushed up costs across fuel production, processing, and distribution networks — impacts that have rippled through nearly every transportation and logistics sector worldwide.

    The company framed the fare hike as a modest adjustment, noting that leadership made a deliberate effort to minimize the increase passed on to customers while still securing the long-term viability of its service. “We recognize that any change to pricing can create inconvenience for our passengers, and we worked diligently to make this adjustment as fair and limited as possible,” the company said in its official announcement.

    Sea Bridge Ferries added that the additional revenue generated by the fare increase will be critical to upholding the high safety standards, operational efficiency, on-time reliability, and passenger comfort that its customers expect, ensuring the service can continue operating consistently into the future. The new pricing structure will go into effect on Monday, June 1, 2026.

  • Prime Minister Says YIDA to Invest Additional US$100M in Antigua and Barbuda

    Prime Minister Says YIDA to Invest Additional US$100M in Antigua and Barbuda

    In a major announcement that promises to boost the economic trajectory of Antigua and Barbuda, the nation’s Prime Minister has confirmed that China-based YIDA is set to inject an additional US$100 million into new development projects across the twin-island Caribbean nation. This fresh capital injection marks the next phase of YIDA’s long-term investment partnership with Antigua and Barbuda, building on previous commitments that have already supported infrastructure, tourism, and job creation initiatives across the country.

    Industry analysts note that the new investment comes at a critical moment for Antigua and Barbuda, which has been working to expand its non-tourism economic sectors and strengthen its resilience following global economic volatility. The Prime Minister highlighted that the $100 million will be allocated across high-priority projects, including upgrades to transportation infrastructure, expansion of hospitality facilities, and development of mixed-use commercial spaces that are expected to draw more international visitors and business activity to the islands.

    Local business leaders have welcomed the commitment, noting that the new investment will create hundreds of temporary construction jobs and dozens of permanent full-time positions across multiple sectors once projects are completed. It also reinforces Antigua and Barbuda’s reputation as an attractive destination for foreign direct investment in the Caribbean, signaling ongoing confidence from international developers in the nation’s long-term economic outlook. Government officials have added that they will work closely with YIDA representatives to ensure transparent project implementation and that all developments align with the country’s national sustainable development goals.

  • Guadeloupe Ferry Brings More Than 360 Visitors to Antigua and Barbuda

    Guadeloupe Ferry Brings More Than 360 Visitors to Antigua and Barbuda

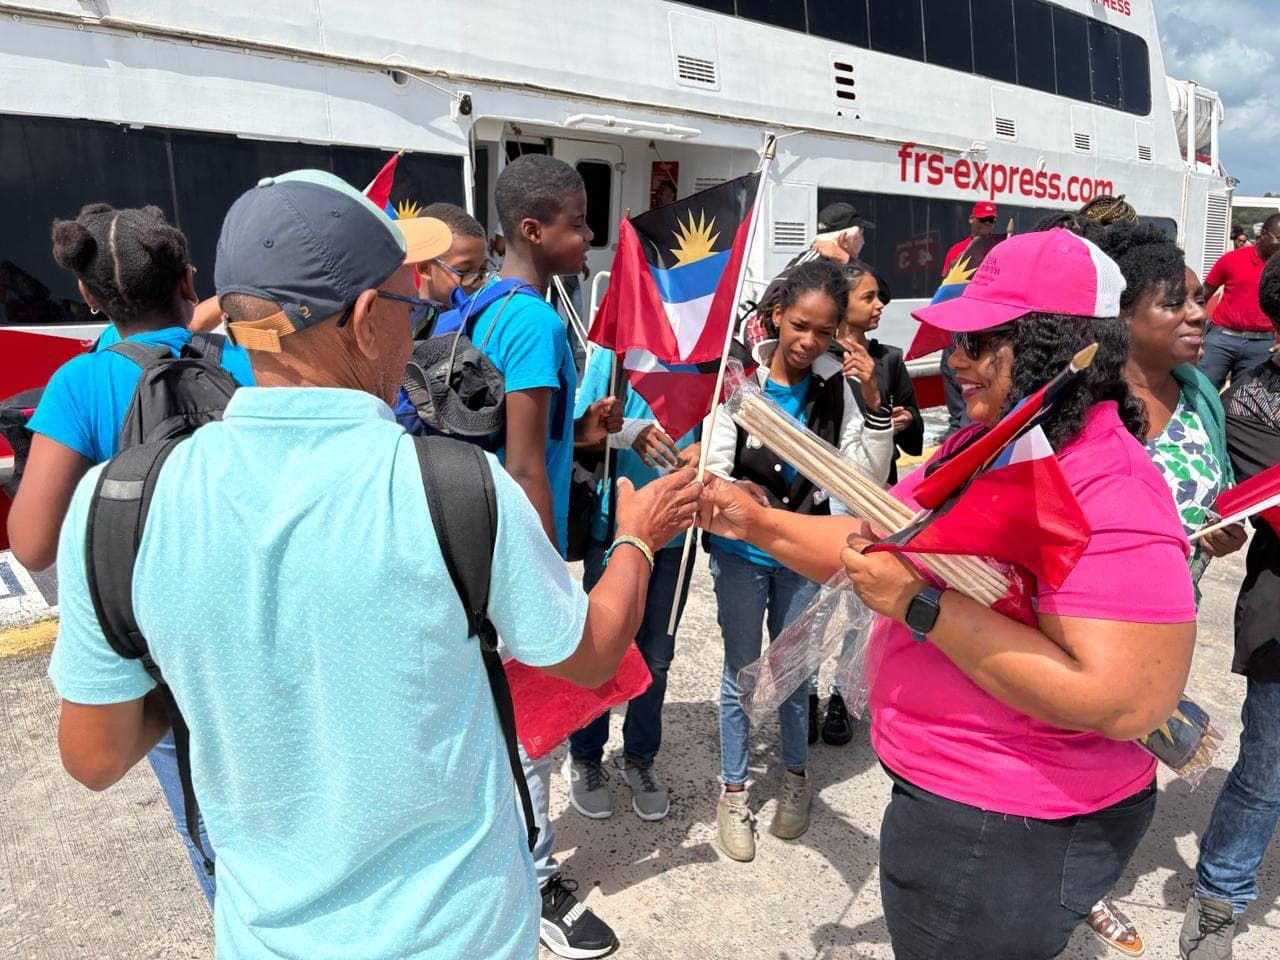
    Antigua and Barbuda has opened its doors to hundreds of travelers from across the Caribbean this month, marking a key milestone in the island nation’s push to revitalize regional tourism. Among the latest arrivals were more than 360 visitors from Guadeloupe, who completed their journey to the twin islands via a direct ferry service earlier this week, officials from the Antigua and Barbuda Tourism Authority confirmed.

    This wave of regional visitors is not a random influx: it is the direct outcome of a sustained, long-term strategy by the destination’s tourism leadership to deepen travel integration across the Caribbean and strengthen transportation and people-to-people connections between neighboring island states. Images released publicly by the tourism authority capture warm, welcoming moments, with local officials greeting incoming guests before they set off to explore island attractions, join cultural activities, and attend curated events across Antigua and Barbuda during their stay.

    For tourism policymakers in the country, growing intra-Caribbean travel has moved to the top of the strategic agenda in recent years. Beyond the initial welcome, officials have reiterated their unwavering commitment to expanding cross-regional transportation networks, developing unique, tailored visitor experiences, and building long-term relationships that encourage regional travelers to return to the islands again and again. The current wave of arrivals comes as the destination continues to ramp up marketing and infrastructure investment to position itself as a top go-to spot for neighboring Caribbean residents looking for a quick getaway or extended vacation.

    Looking ahead, the Antigua and Barbuda Tourism Authority extended its gratitude to all visitors who chose the twin islands as their travel destination, and expressed measured confidence that the upward trend in regional travel will continue through the coming quarters, delivering widespread economic benefits to local communities that rely on tourism.

  • GWM to unveil new South Camp Road showroom on Wednesday

    GWM to unveil new South Camp Road showroom on Wednesday

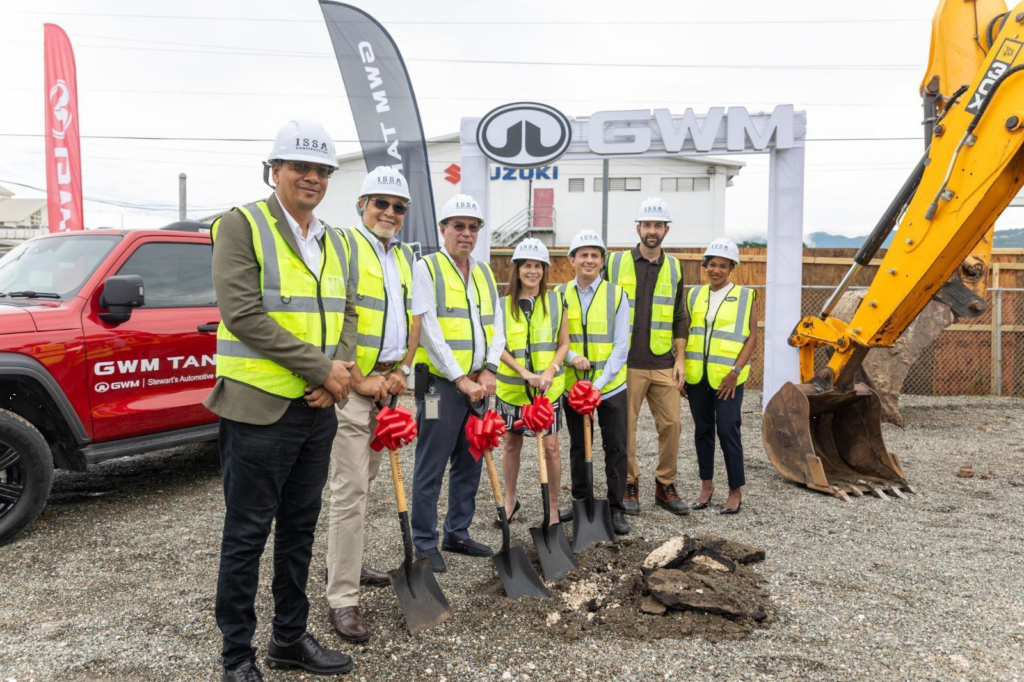
    KINGSTON, Jamaica — A major milestone in Jamaica’s automotive retail sector is set to unfold this week, as China’s Great Wall Motor (GWM) prepares to cut the ribbon on its first purpose-built dedicated showroom on Kingston’s South Camp Road this Wednesday, June 3. The private inaugural opening ceremony will draw key industry and government stakeholders, including Senator Aubyn Hill, Jamaica’s Minister of Industry, Investment and Commerce, who will deliver remarks to attending guests. Joining Hill will be Hankin Zhao, GWM’s Country Manager for the Caribbean and Venezuela, alongside senior leadership from Stewart’s Automotive Group, GWM’s exclusive local partner.

    In an official statement ahead of the launch, GWM confirmed that the new showroom opening comes on the heels of consistent, sustained growth for the brand across Jamaica. To date, roughly 2,000 GWM vehicles are already registered and in operation across the island, a milestone that paved the way for investment in a dedicated retail space. This facility marks the first standalone GWM showroom in Jamaica operated by Stewart’s Automotive Group, a family-run automotive stalwart that has served Jamaican motorists since 1938.

    Jacqueline Lechler, Managing Director of Stewart’s Automotive Group, emphasized that the new showroom investment directly reflects rising consumer confidence in GWM among Jamaican drivers. “Launching a dedicated GWM space demonstrates our long-term commitment to the Jamaican market, and it gives customers a fully immersive authentic GWM experience all in one location,” Lechler explained. “With our customer base growing to the point that 2,000 GWM vehicles are already on local roads, it only makes sense that we provide a dedicated home for both our current and future customers.”

    Lechler detailed that the decision to add GWM to Stewart’s brand portfolio followed a rigorous multi-stage assessment of automotive brands tailored to the unique driving conditions across the Caribbean, with evaluation criteria heavily weighted toward durability, long-term reliability, and overall consumer value. “Stewart’s has deep expertise in the needs of Jamaican motorists. After decades serving drivers across the island, we know what designs and features hold up to our local roads and what doesn’t,” Lechler noted. “When we set out to add a new automotive brand to our offerings, we only wanted one we could endorse with full confidence. GWM’s strategic focus on pick-up trucks and SUVs is perfectly aligned with local demand, and these vehicles are specifically engineered to navigate uneven road surfaces, the island’s mountainous terrain, and our tropical climate. This is a Chinese brand that fits exceptionally well with daily life in the Caribbean.”

    Lechler also pointed out that selecting South Camp Road as the showroom location was a deliberate choice, as the corridor has evolved into Kingston’s central automotive hub. “South Camp Road is already Stewart’s core corridor here in Kingston, so we wanted GWM to grow right at the center of our existing operations,” she added. “This wasn’t the easiest choice when we were evaluating brands, but it was the right choice for Jamaica. GWM vehicles have already been road-tested in some of the most demanding markets across the globe, and we have seen firsthand how well they adapt to local driving conditions. When Stewart’s backs a brand, it’s because we are ready to support it for the long haul.”

    The new showroom features a sleek, modern minimalist design, and will display the entire GWM Caribbean product line in a single open space, allowing customers to explore the brand’s latest in-vehicle technology, industry-leading safety features, and refined interior designs firsthand. Titanya Clarke, Brand Sales Manager for GWM Jamaica, outlined the brand’s unique value proposition for local consumers. “GWM stands at its core for innovation, cutting-edge technology, uncompromising quality, and accessible value,” Clarke explained. “What sets us apart from competing brands is our ability to offer premium features, contemporary design, and advanced automotive technology at a far more accessible price point than many of our rivals. Great Wall Motor’s promise to Jamaican drivers is simple: go with more. More innovation, more technology, more quality, and more value for your investment.”

    Clarke also emphasized that customer relationship building is a core priority for the local GWM operation. “We center our approach on listening to our customers. From a customer’s first visit to their first routine service appointment, we want every person to feel that this is their brand and their local automotive home. Basic customer service is just our starting point; what we’re building is long-term relationships. When a GWM customer reaches out, whether it’s days or months after their purchase, we are ready to listen and respond promptly,” she added.

    The full GWM line-up available at the new showroom includes the HAVAL range, headlined by the Jolion and H6 SUV models, the premium TANK off-road vehicle series, and the P-Series pickup truck, a popular workhorse that already sees widespread use in major markets including China, South Africa, and Australia. Every GWM vehicle sold in Jamaica carries a five-star global safety rating and comes with a comprehensive six-year/200,000 km warranty, giving local buyers added peace of mind.

    Lechler framed the showroom opening as more than just a new retail expansion, describing it as the start of a long-term aligned partnership. “This isn’t simply opening another dealership or adding a new brand badge to a showroom wall. It’s the beginning of a long-term partnership between two companies that share core values: a commitment to durability, a focus on innovation, and a dedication to earning the trust of our customers every single day,” Lechler said. “We know GWM has the products, the technology, and the vision to thrive in Jamaica, and we’re incredibly proud to be the team bringing that future to Jamaican drivers.”

    Following Wednesday’s private launch event, the new South Camp Road GWM showroom will open its doors to the general public starting Thursday, June 4. From opening day, customers are welcome to visit the facility, explore the entire GWM product range, and book test drives to experience the brand’s vehicles firsthand.

  • Coffee industry needs urgent recovery support after billions in losses, says Dr Grant

    Coffee industry needs urgent recovery support after billions in losses, says Dr Grant

    KINGSTON, Jamaica — Jamaica’s iconic Blue Mountain coffee sector, long a cornerstone of the country’s agricultural export economy, is facing an unprecedented crisis following consecutive devastating weather events and soaring global production costs. In a public statement released this week, Dr. Norman Grant, president of the Jamaica Coffee Exporters Association (JCEA), has issued an urgent call for targeted investment in infrastructure and expanded mental health support for thousands of small-scale coffee farmers reeling from repeated catastrophic losses.

    The industry’s current struggles stem from a perfect storm of overlapping shocks that have hit production over the past two years. First, Hurricane Beryl made landfall in July 2024, destroying significant swathes of growing land across the Blue Mountain region. Barely 16 months later, Hurricane Melissa struck in October 2025, delivering an even more severe blow to the already vulnerable 2025/2026 mature coffee crop. Compounding these climate-driven disasters are skyrocketing input and logistics costs, driven in large part by ongoing geopolitical conflict in the Middle East, which has sent global fuel and shipping prices surging to multi-year highs.

    The scale of the damage is staggering. Grant confirmed that Hurricane Melissa alone wiped out nearly 40 percent of the current season’s mature harvest, eliminating approximately 100,000 boxes of coffee and causing an estimated JMD $1 billion in direct on-farm losses. Across the entire two-year crisis period, overall coffee production has plummeted dramatically: output fell from 288,000 boxes in the 2023/2024 crop year to a projected 150,000 boxes for the 2025/2026 season. This 48 percent production drop has translated to a total estimated loss of around JMD $1.5 billion for more than 5,000 independent coffee farmers across the island, with export earnings projected to fall by roughly US$15 million this year.

    Beyond the tangible financial damage, Grant emphasizes that repeated crop failures have inflicted severe emotional and psychological strain on tight-knit farming communities that have relied on Blue Mountain coffee for generations. Many smallholder farmers have lost their primary source of income for two consecutive seasons, leaving many facing uncertainty about their ability to remain in the industry. For this reason, Grant stresses that psychosocial and mental health support must be paired with traditional agricultural recovery programs to address the full scope of the crisis.

    “While the Blue Mountain coffee industry has always shown remarkable resilience in the face of past challenges, the cumulative impact of back-to-back hurricanes and runaway costs means we can’t afford to wait for recovery to happen on its own,” Grant said. “Urgent, coordinated action from both public and private stakeholders is required to restore production levels and build long-term resilience for farming communities.”

    The JCEA is currently advocating for a suite of targeted policy and investment initiatives to reboot the sector, including the formal implementation of the Coffee Crop Resuscitation and Establishment Programme (CREP), critical rehabilitation of crumbling farm access roads that have been left impassable by storm damage, and targeted grants to help smallholders rebuild their production capacity from the ground up.

    Despite the grave current challenges, Grant reaffirmed that Jamaica Blue Mountain coffee retains its status as one of the country’s most valuable and internationally recognized agricultural brands, supporting tens of thousands of jobs across the production and export supply chain and maintaining a premium reputation among specialty coffee consumers around the globe. He also expressed gratitude for the ongoing recovery support already provided by the Jamaican government, the Jamaica Agricultural Commodities Regulatory Authority (JACRA), and international partners, which has included funding for critical farm inputs and donations of thousands of coffee seedlings to help farmers replant damaged fields.

  • New real estate dealer different reports J$3.5B in accepted offers within first five months

    New real estate dealer different reports J$3.5B in accepted offers within first five months

    A freshly launched Caribbean real estate brokerage firm, Different Capital Limited, has announced an impressive early operational milestone, revealing it has secured roughly J$3.5 billion in accepted property offers across the Jamaican and Cayman Islands markets within just five months of opening its doors. In an official press statement shared this week, the company framed the strong early performance as a validation of its client-centric, quality-focused operating model, which centers on curating high-value real estate assets, delivering industry-leading investment property analysis, and nurturing long-term, trust-based relationships with all stakeholders. Beyond core brokerage services, Different Capital highlighted its specialized expertise in real estate investment trust (REIT) structuring, coordination and management as a key competitive differentiator that has allowed it to tap into fast-growing demand for accessible, professionally managed, institutional-grade real estate investment opportunities in the region. According to Chris Williams, the firm’s chairman and chief executive officer, Different Capital remains unwavering in its commitment to generating tangible value for both property owners and investors, who consistently prioritize aggressive opportunity sourcing, granular due diligence and transparent, consistent communication. Looking ahead, the company says it will continue growing its property pipeline while working toward its long-term strategic goal of claiming the top position as the leading broker for investment properties and REITs across the Caribbean market. The solid early performance points to unmet demand for specialized, client-focused real estate investment services in the region, as both local and international investors seek out structured, low-barrier access to commercial and residential property assets in Jamaica and the Cayman Islands, two of the Caribbean’s most attractive real estate markets.

  • Stable Central Bank maintains interest rate at 5.25% per year

    Stable Central Bank maintains interest rate at 5.25% per year

    At its May 2026 monetary policy gathering, the Central Bank of the Dominican Republic (BCRD) has opted to maintain its benchmark reference interest rate at an annual 5.25%, leaving two other key monetary rates unchanged as well: the 1-day Repos permanent liquidity expansion facility stays at 5.75%, and the Overnight remunerated deposit rate remains fixed at 4.50%.

    This policy decision comes on the heels of a careful assessment of both domestic economic trends and shifting global monetary conditions. BCRD policymakers anchored their call on two key observations: the Dominican Republic’s economy is continuing a gradual, steady rebound, and the latest uptick in inflation can be traced directly to a supply-side shock driven by spiking global crude oil prices. Crucially, the central bank emphasized that medium-term inflation expectations remain firmly anchored around its official target of 4.0%, with a tolerance band of plus or minus 1.0%.

    To contextualize the decision, BCRD outlined the current mixed global economic landscape. The United States logged a solid 2.6% year-over-year expansion in the first quarter of 2026, with unemployment holding near full employment levels. But rising energy costs pushed U.S. inflation up to 3.8% in April, erasing recent progress on price cooling. Across the Atlantic, the Eurozone is seeing a marked slowdown in economic activity, with inflation resting at 3.0% as of the latest readings. For Latin America as a whole, regional average growth holds steady at 2.0%, and a majority of regional central banks have joined the Dominican Republic in keeping interest rates unchanged in recent meetings.

    On the domestic front, year-over-year inflation in the Dominican Republic hit 5.11% in April, a rise that can be almost entirely attributed to recent fuel price adjustments. Encouragingly, core inflation— which strips out volatile food and energy prices—remained within the central bank’s target range at 4.87%. To buffer households and businesses from the impact of rising energy costs, the national government has rolled out targeted measures, including partial fuel subsidies and expanded social assistance programs.

    Looking ahead, BCRD’s proprietary forecasting models project that inflation will fall back within the official target range by the fourth quarter of 2026, once the temporary effects of the global oil price shock fade. In positive news for broader economic performance, the country’s monthly economic activity indicator (IMAE) grew 4.0% year-over-year across the first four months of 2026, with strong gains led by the construction sector, manufacturing for free trade zones, and the key tourism industry.

    Financial metrics also paint a picture of resilience: as of the end of May 2026, the Dominican peso has appreciated by 8.0% against major currencies, while the country’s international reserves have climbed to US$15.9 billion. This reserve level is equivalent to six months of national imports, exceeding the adequacy metrics recommended by the International Monetary Fund.

    In closing, the central bank reaffirmed that the Dominican economy boasts solid underlying fundamentals and a stable, well-regulated financial system. Against a turbulent international backdrop marked by ongoing geopolitical crisis in the Middle East, BCRD reiterated its commitment to take prompt, targeted action whenever necessary to keep inflation on track toward target and preserve long-term macroeconomic stability for the nation.

  • Guyana ziet met enorme oliewinsten van Iran-oorlog de groeidruk toenemen

    Guyana ziet met enorme oliewinsten van Iran-oorlog de groeidruk toenemen

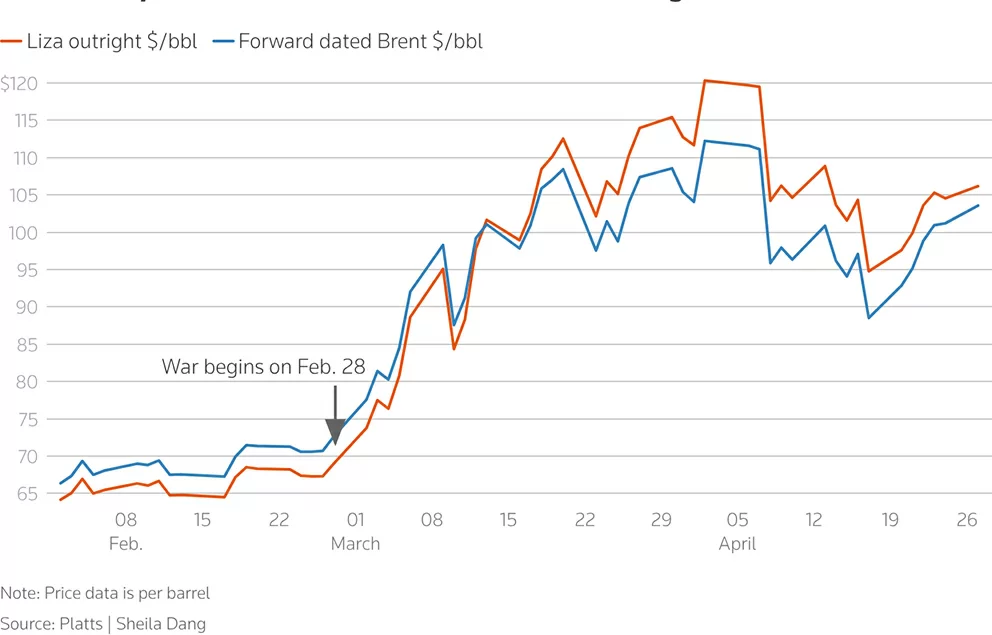
    Geopolitical tensions ignited by the Iran conflict have sent global oil prices surging in recent months, and one small South American nation is positioned to reap disproportionate benefits — while facing uniquely modern challenges tied to its sudden oil wealth. Guyana, a neighboring country to Venezuela with just under 1 million residents, was already the world’s fastest-growing economy before the outbreak of heightened conflict in the Middle East pushed crude prices sharply upward. Today, shifting global energy markets are set to deliver a windfall to the nation, but this unexpected fortune also brings new risks that threaten its long-term stability.