Released in September 2026 by the U.S. Department of State, the 35-page annual Investment Climate Statement for Belize characterizes the Central American nation’s business landscape as a mixed, slowly evolving environment that has made incremental progress to court foreign capital, even as deep-seated systemic challenges continue to erode investor trust. The assessment, published 11 months into the calendar year, arrives on the heels of five consecutive years of economic expansion for Belize, which posted 2.7% GDP growth in 2025 following a 3.5% rise the prior year, paired with a measurable uptick in incoming foreign direct investment. Recent targeted reforms have laid the groundwork for a more streamlined operating environment: the launch of a national Online Business Registry System now allows entrepreneurs to reserve company names, complete registration, and submit required filings entirely digitally, cutting down on historic administrative delays for new ventures. Commercial banks no longer require pre-approval from Belize’s Central Bank for most foreign currency purchases under $50,000, drastically accelerating payments to international suppliers. The 2025 launch of the country’s first official credit bureau has expanded lenders’ access to verifiable borrower track records, while a new modernized insolvency framework gives financially distressed firms the option to restructure operations instead of facing immediate mandatory liquidation, reducing unnecessary market churn. For all these gains, however, the report outlines a litany of longstanding, unresolved frictions that continue to make both domestic and international investors cautious. Top cited pain points include glacial bureaucratic processing, inconsistent enforcement of regulatory rules, widespread land tenure insecurity, pervasive public sector corruption, and a total lack of transparency around government contract awards and commercial dispute resolution processes. While Belize has formal anti-corruption statutes on the books, enforcement remains highly ineffective: the national Financial Intelligence Unit closed out 17 corruption-related cases in 2025 but secured only a single conviction, and mandatory annual public official asset disclosure rules see negligible levels of compliance. Multiple business representatives interviewed for the report confirmed that leaders from both of Belize’s major political parties regularly engage in patronage practices, awarding lucrative operating licences, state contracts, and public land parcels to political allies rather than qualified independent bidders. The country’s land administration system is particularly fraught, with multiple overlapping, uncoordinated title databases, outdated and inaccurate land surveys, and no formal regulatory framework governing real estate agents, leaving a well-documented history of fraud and corrupt practices at the national Lands and Survey Department that requires all prospective land buyers to conduct extensive, independent due diligence to verify ownership. State dominance of key utility and infrastructure sectors further distorts market competition: the national government maintains controlling stakes in the national electricity provider, water utility, primary seaport, and largest telecommunications firm. When a U.S.-based satellite internet provider recently applied for a full national operating licence, incumbent providers including the state-owned telecom mounted successful opposition that restricted the new entrant to a limited, partial service permit. Additional investor grievances include exorbitant electricity and international shipping costs, the constraints of Belize’s small domestic consumer market, skilled labour shortages, and multi-month backlogs for foreign worker permit approvals. The report also flags critical institutional gaps that undermine public accountability: the national Ombudsman role, tasked with investigating public sector misconduct, has remained vacant since December 2025 after the government declined to renew the contract of retired Major Herman Gilbert Swaso, and the Office of the Auditor General’s routine public spending audits are running years behind schedule, with the only active ongoing high-profile investigation focused on the Ministry of Defence and the high-stakes Mira Millions corruption scandal. For ordinary Belizeans, the stakes of these unaddressed frictions are tangible: total public sector debt stands at BZ$4.68 billion, equivalent to 70.2% of national GDP, translating to roughly $7 of government debt for every $10 of economic output generated in the country. While headline unemployment sits at a deceptively low 1.9%, official government data confirms more than one third of the national workforce is employed in the informal sector with no labour protections, and a significant share of formal workers earn less than the legal BZ$5 minimum wage. The report’s concluding assessment notes that while Belize’s government has demonstrated clear willingness to implement pro-investment reforms, decades-old structural barriers will continue to suppress investor confidence and prevent the country from unlocking its full economic potential without targeted, sustained enforcement and institutional overhaul.
分类: business
-
US pinpoints hurdles to partnerships with Guyanese businesses
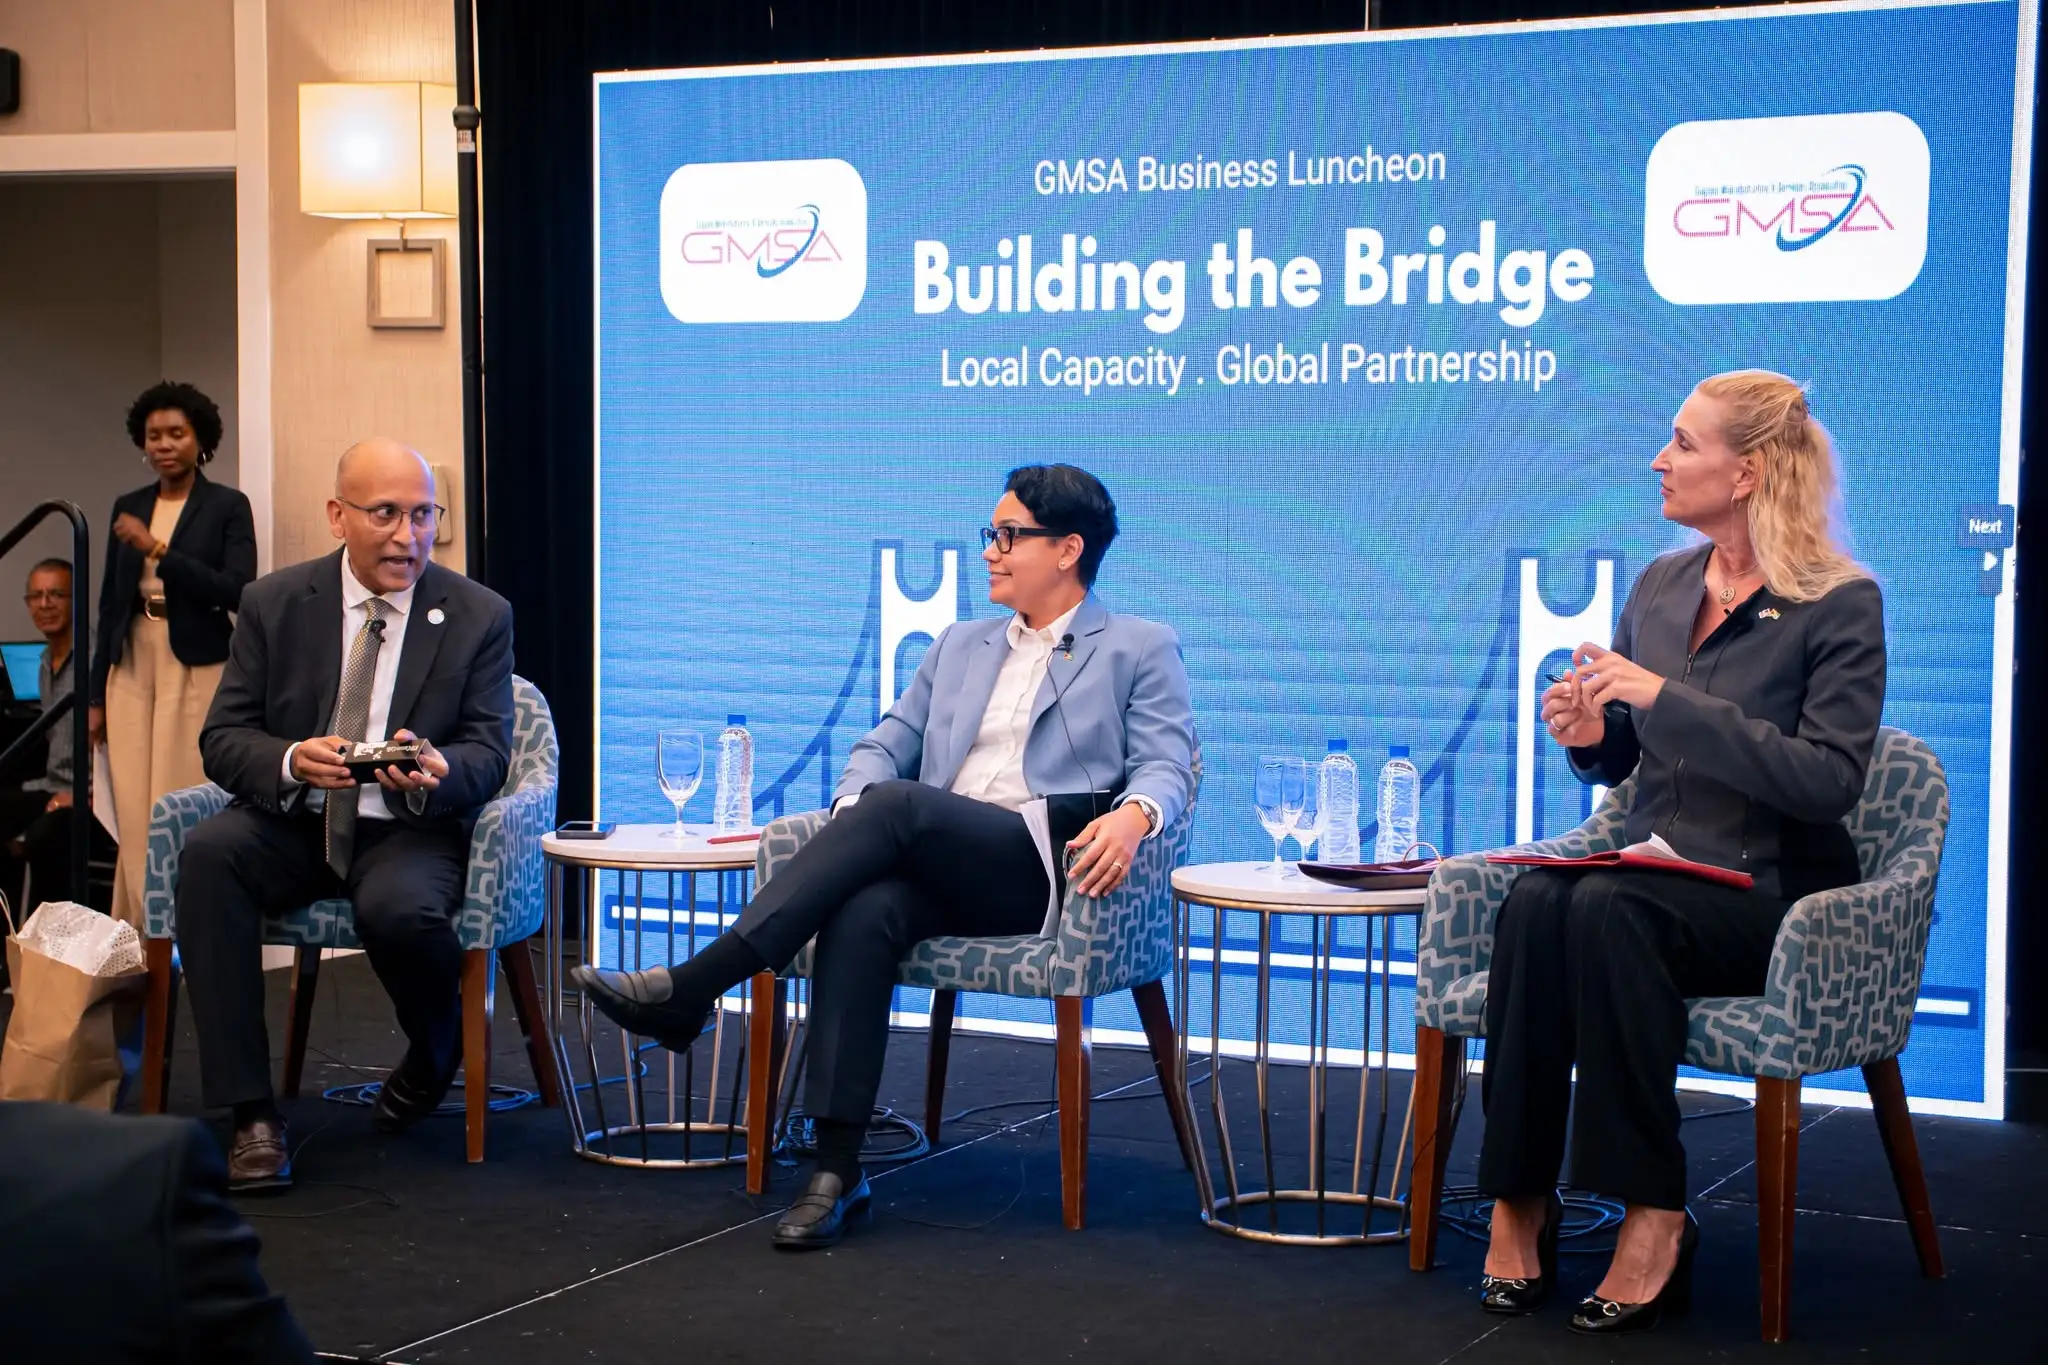
Against the backdrop of Guyana’s rapidly expanding economy, fueled by a booming oil sector and growing interest from international investors, top government officials and U.S. diplomatic representatives gathered at a recent Guyana Manufacturing and Services Association (GMSA) business luncheon themed “Building The Bridge- Local Capacity, Global Partnership” to chart a path for mutually beneficial cross-border commercial collaboration.
U.S. Ambassador to Guyana Nicole Theriot opened her address by noting that her embassy has been flooded with inquiries from American firms eager to enter the Guyanese market, drawn by the country’s promising investment landscape that has already attracted major U.S. commitments in oil and gas, food franchises, branded hospitality, and offshore shorebase operations. However, Theriot emphasized that significant gaps remain for local enterprises to position themselves as reliable, scalable partners for U.S. buyers and investors. She outlined persistent pain points cited repeatedly by U.S. companies exploring Guyana: limited access to local partners capable of delivering goods and services at consistent, large-scale volumes, underdeveloped logistics networks, soaring energy costs, a burdensome and unpredictable tax framework, and shortages of accessible land and skilled labor.
Theriot framed targeted, collaborative progress on these fronts as the foundation for long-term, transformative economic growth in Guyana, noting that targeted foreign capital inflows could unlock stronger domestic firms, upskill local workforces, introduce cutting-edge operational technologies, and drive widespread adoption of internationally recognized production standards. She also highlighted that three key U.S. federal agencies — the U.S. International Development Finance Corporation, the U.S. Trade and Development Agency, and the U.S. Department of Commerce — offer dedicated support programs for Guyanese enterprises looking to establish formal commercial ties with U.S. counterparts. Theriot added that U.S. firms prioritize three core benchmarks when vetting local partners: the ability to produce goods to exact, consistent specifications, unwavering quality control and safety protocols, and the operational flexibility to scale output to meet rising demand. She expressed optimism that Guyana’s recently introduced tax incentives and business support schemes for domestic firms would help clear existing frictions, and reaffirmed her commitment to working with local stakeholders to resolve remaining market access barriers through structured global partnerships.
For her part, Guyana’s Minister of Industry and Commerce Susan Rodrigues delivered a direct call to local business owners to reframe third-party certification and compliance not as a costly administrative burden, but as a high-return strategic investment, urging them to leverage resources offered by the Guyana National Bureau of Standards (GNBS) to align their operations with global benchmarks. Rodrigues clarified that meeting only local Guyanese standards is insufficient to gain entry to overseas markets across the Caribbean, North America, Europe and other key trade blocs, all of which enforce their own strict import requirements for quality, safety and consistency. She laid out the full set of criteria for export readiness: consistent production quality, reliable supply chain capacity, deep familiarity with target market regulatory rules, competitive pricing, and a proven track record of fulfilling large orders on schedule. The minister also pledged full government support to domestic enterprises navigating the process of meeting international export specifications, encouraging them to prioritize global quality benchmarks from the earliest stages of product development rather than only working to meet local domestic requirements as an initial goal. -
West Indies Oil Seeks Coordination on Fuel Deliveries During CHOGM
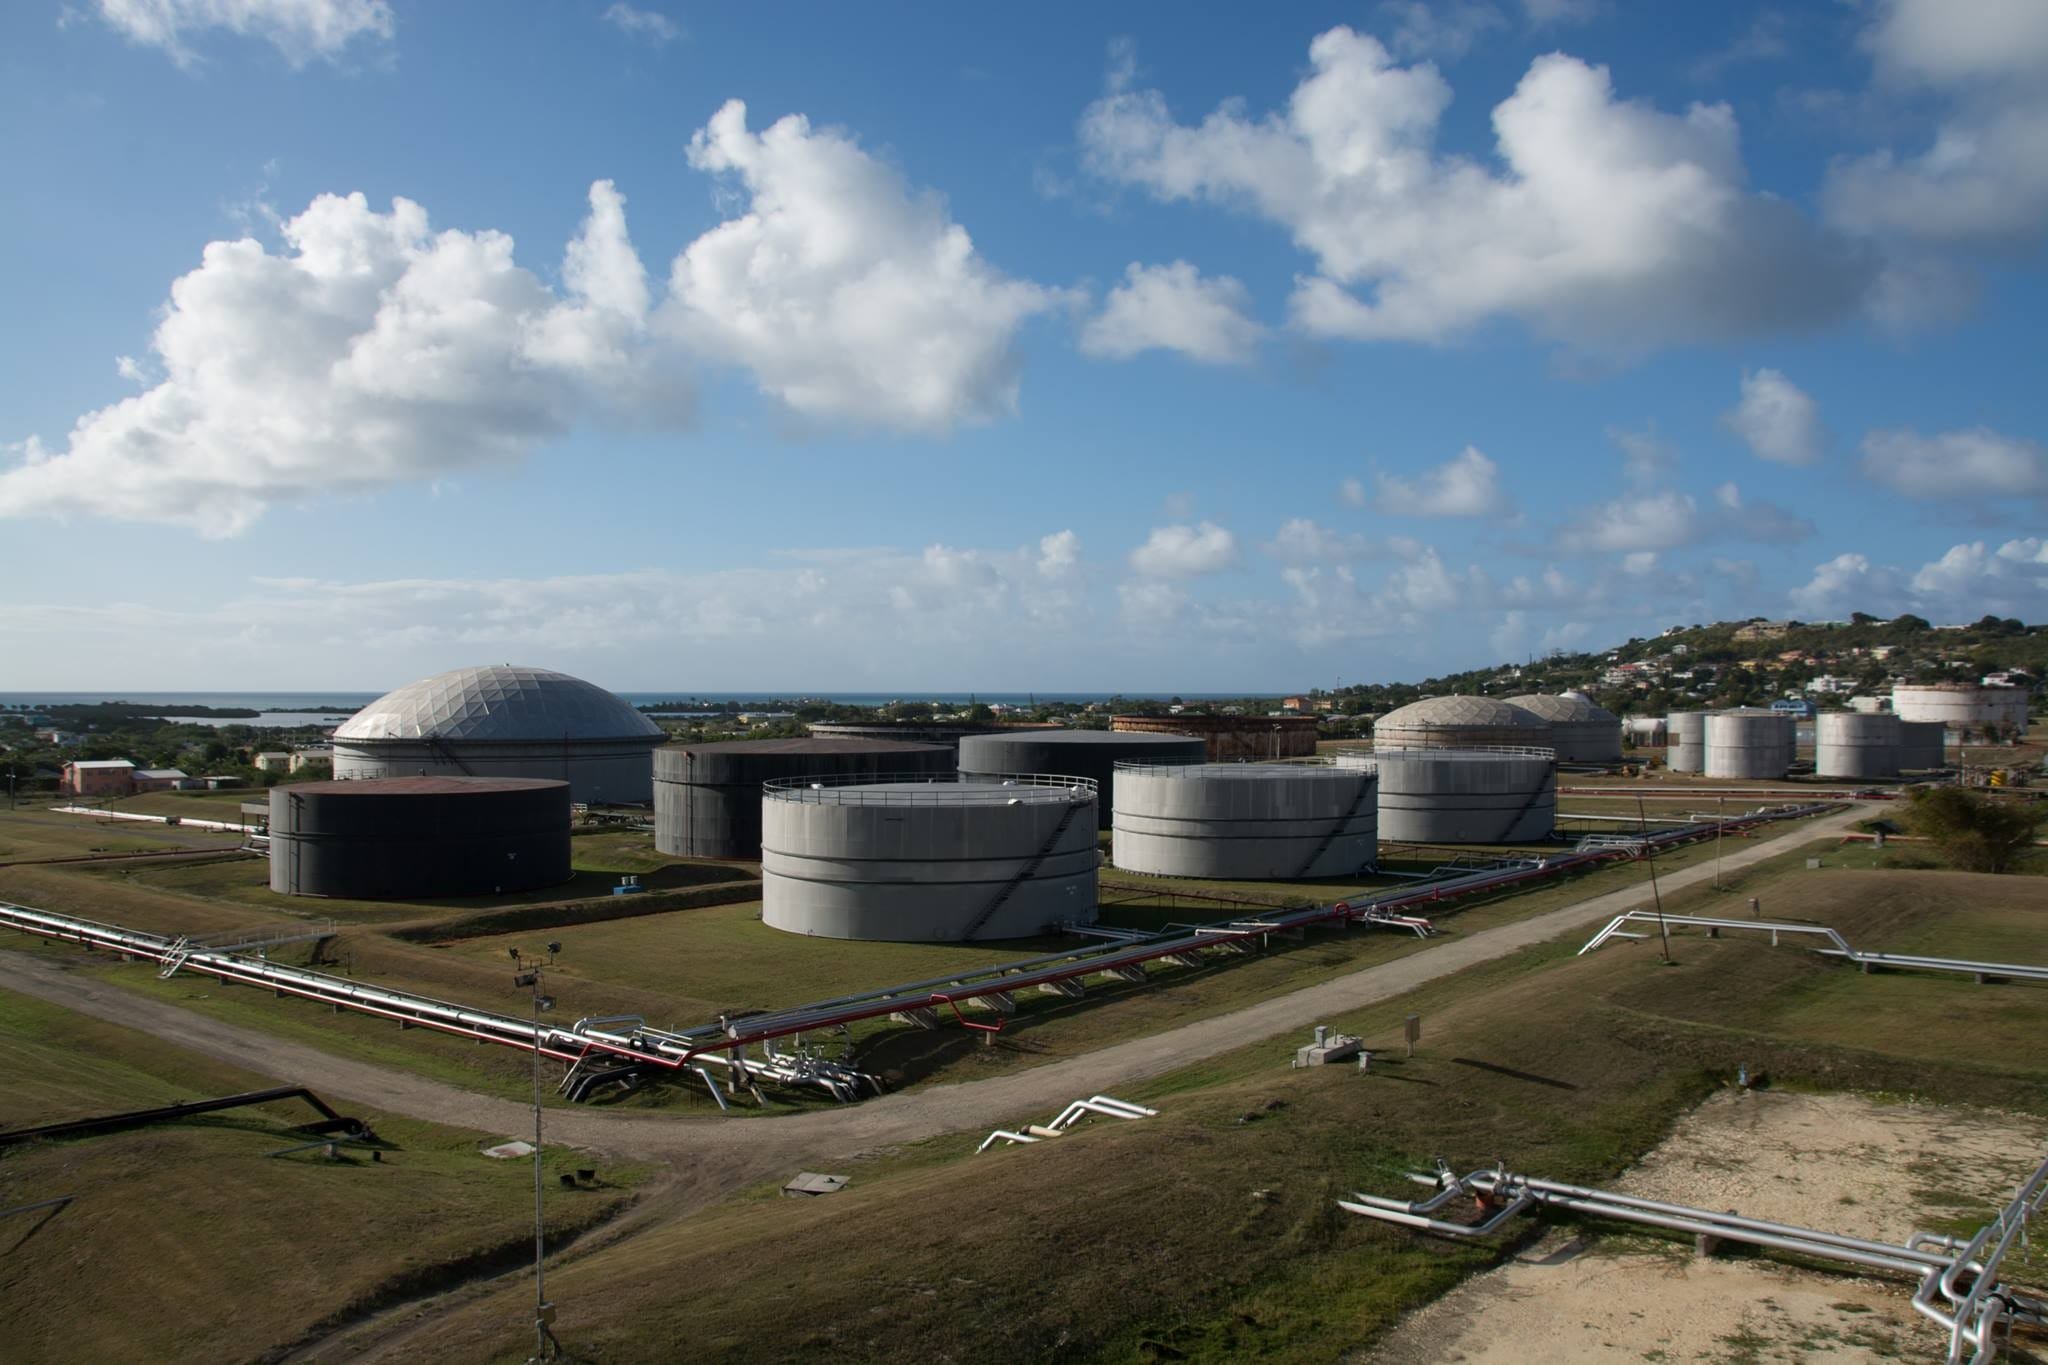
As the Caribbean region prepares to host the highly anticipated Commonwealth Heads of Government Meeting (CHOGM), regional energy major West Indies Oil has formally reached out to local transportation authorities, event organizing committees, and fuel distribution partners to establish a coordinated, streamlined framework for fuel deliveries across the host territory. The company’s leadership noted in an official statement that the large influx of international diplomatic delegations, support staff, and media personnel for the summit will trigger temporary road access restrictions, rerouted traffic corridors, and heightened security protocols in high-traffic zones around the main event venues. Without pre-arranged synchronization between all relevant parties, routine fuel shipments to residential neighborhoods, commercial filling stations, and critical public service sites including hospitals and emergency response hubs face significant risk of unplanned delays. West Indies Oil has proposed a dedicated pre-clearance lane for authorized fuel delivery vehicles, shared real-time updates on temporary road closure schedules, and a staggered delivery window arrangement that routes supply trucks away from peak event transit times. The firm emphasized that the coordinated plan is designed to ensure uninterrupted fuel access for all end users, while also eliminating the possibility of supply shortages that could disrupt the smooth operation of the high-profile diplomatic gathering. Local government representatives have acknowledged the proposal and confirmed they are scheduled to convene a multi-stakeholder working group in the coming week to finalize the coordinated delivery roadmap ahead of CHOGM’s official launch.
-
Chile and Dominican Republic explore irrigation and agricultural cooperation
A high-level delegation representing Chile’s Irrigation and Drainage Association (Agryd) has wrapped up a four-day official working tour of the Dominican Republic, centered on unlocking mutually beneficial commercial partnerships, elevating technical collaboration frameworks, and sharing industry-leading expertise to advance widespread modernization of the Caribbean nation’s agricultural ecosystem.
Over the course of the mission, Chilean delegation members held a series of structured high-level meetings with senior leadership from key Dominican public sector bodies, including the National Irrigation Technology Agency (TNR), the Ministry of Agriculture, and the National Institute of Hydraulic Resources (INDRHI). The bilateral dialogues covered a broad range of priority topics spanning cutting-edge irrigation deployment, streamlined agricultural policy design, accessible financing mechanisms, cross-border agri-trade pathways, and targeted foreign investment openings in the Dominican agricultural space.
Beyond public sector engagements, the Chilean group also connected with leading private and non-profit Dominican agricultural stakeholders, such as the Dominican Agribusiness Board (JAD), the state-owned Agricultural Bank (Bagrícola), and the Institute for Cooperative Development and Credit (Idecoop). During these sessions, participants explored the feasibility of long-term strategic alliances, structured knowledge-sharing programs for irrigation technology, and the potential negotiation of a partial bilateral trade agreement tailored to agri-sector priorities between Chile and the Dominican Republic.
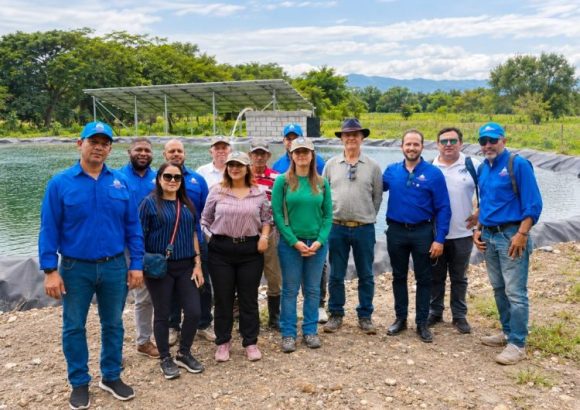
The delegation also traveled outside the capital to San Juan province, where they conducted on-site field visits to review locally implemented technified irrigation systems in operation, before holding targeted discussions with TNR-vetted commercial suppliers to map out joint technical and commercial cooperation projects focused on the adoption of high-efficiency pressurized irrigation solutions.
TNR Executive Director Claudio Caamaño Vélez emphasized that the carefully curated mission delivered a tailored, first-hand experience for Chilean agricultural producers, technical specialists, and prospective investors to gain granular insight into under-explored investment and innovation pipelines across the Dominican Republic’s fast-growing agri-tech landscape. Agryd Executive Director José Miguel Morán publicly lauded the Dominican government’s ongoing policy push to overhaul national irrigation infrastructure, noting that these targeted modernization efforts are poised to drive significant gains in on-farm productivity while accelerating progress toward more ecologically sustainable agricultural operations.
This cross-border mission is formally integrated into TNR’s broader multi-year international cooperation strategy, which is designed to strengthen domestic institutional technical capacity, accelerate the rollout of water-smart agricultural innovation, and build durable cross-national partnerships centered on optimized water resource use and low-carbon, sustainable agricultural production. Additional local coverage of this development is available via DominicanScope. -
PM Browne criticises landowners for leaving tourism development sites idle
In a targeted address to domestic business stakeholders and landowners, Prime Minister Gaston Browne revealed that parcels of high-value coastal real estate at Pensioners Beach, Shell Beach, and a string of adjacent scenic locations have been successfully secured for tourism-focused accommodation developments, yet construction across all these sites has stalled far below initial projected timelines. Browne emphasized that holding undeveloped coastal land as a static asset delivers almost no tangible economic returns for local communities, generates no new jobs in the hospitality sector, and fails to capitalize on the destination’s surging global tourist demand. He laid out a clear call to action for local investors to prioritize the development of boutique villas and licensed short-term rental properties, segments of the tourism market that have posted double-digit revenue growth in regional peer markets over the past three years. The prime minister also extended complementary guidance to residents holding significant liquid savings in local commercial banks, noting that leaving large cash deposits idle leaves their purchasing power steadily eroded by persistent global inflationary pressures, and that redirecting a portion of those funds toward income-generating real estate and tourism assets would deliver far more resilient long-term wealth gains. Browne reaffirmed that his administration stands ready to roll out targeted support frameworks – including streamlined permitting pathways, tax incentives for eligible small-scale local developers, and targeted marketing support for new accommodation properties – for all viable, community-focused tourism projects led by domestic investors. At the same time, he issued a firm reminder to all landowners holding earmarked coastal parcels that they will be expected to take immediate, verifiable practical steps to advance construction, rather than continuing to hold land for speculative resale without productive use.
-
Parliament approves SVG’s membership of CAF
On a recent Thursday, the House of Assembly of St. Vincent and the Grenadines formally passed legislation to secure the country’s membership in the Development Bank of Latin America and the Caribbean (CAF), following a rigorous, extended parliamentary debate focused on the potential economic benefits and prudent risk management of joining the regional multilateral financial institution.
Leading the legislative push, Prime Minister and Minister of Finance Godwin Friday framed CAF accession as a strategic move to diversify the island nation’s development funding ecosystem, ease persistent fiscal pressures, and unlock targeted support for long-term growth — while repeatedly clarifying that membership would not automatically grant SVG access to pre-approved loans. Friday emphasized that the new institutional partnership would deliver both supplementary financing streams and specialized technical cooperation, aligned with the administration’s overarching policy goals of stabilizing public finances, shielding marginalized vulnerable populations, and catalyzing inclusive economic expansion.
The newly passed bill codifies two formal bilateral agreements SVG signed with CAF on October 8: a share subscription pact, and a separate framework outlining legal immunities, tax exemptions, and procedural privileges for the multilateral body operating on Vincentian soil. The legislation grants full domestic legal standing to both agreements, formalizing SVG’s entry into the regional lender’s membership structure.
Under the terms of the share subscription deal, St. Vincent and the Grenadines will acquire 141 Series C CAF shares, each valued at US$14,200, for a total one-time investment of US$2,002,200, payable within 30 days of the agreement’s official effective date. Friday stressed that this allocation is a capital investment in the multilateral institution, not a targeted disbursement for any single public project, and that no future financing would be extended to SVG without independent, case-by-case review aligned with national legal requirements. The prime minister noted that this initial share purchase would unlock an estimated US$8 million in potential borrowing capacity, equivalent to four times the value of SVG’s subscribed capital.
Friday positioned CAF as a complementary addition to the country’s existing roster of international development partners, with eligibility for support spanning critical priority areas including climate-resilient infrastructure upgrades, disaster risk reduction initiatives, and UN-aligned sustainable development projects. He contextualized the membership push against SVG’s current fiscal landscape, noting that national public debt currently hovers at approximately EC$3.6 billion, or 113% of gross domestic product, with high debt servicing costs siphoning public funds away from frontline social services and growth-focused investment. The prime minister underscored that fiscal stabilization efforts would not roll back protections for the country’s most vulnerable communities, and that all future CAF-aligned programming would be co-designed with input from the private sector, labor unions, civil society groups, and local communities, with full regular reporting to the House of Assembly on all related borrowing and expenditure. All future CAF loans will be embedded into SVG’s existing medium-term debt management strategy, and vetted against upcoming fiscal responsibility legislation, with Friday noting that CAF financing could offer longer tenures, lower interest rates, and strict project earmarking tied to initiatives that deliver measurable gains in economic growth and climate resilience — though he reaffirmed these outcomes are prospective, not guaranteed, pending full negotiation of individual financing deals.
Across the aisle, opposition legislators voted in support of the membership bill while raising targeted oversight concerns to mitigate potential fiscal risk. Opposition Senator Carlos James pushed back against framing CAF financing as concessional, noting that its interest rates are often tied to global market benchmarks and could rise above 5%, classifying the funding as competitive rather than preferential. He urged the administration to restrict all future CAF borrowing exclusively to revenue-generating, growth-focused capital projects, rather than drawing down funds to cover routine recurrent government costs. Fellow Opposition Senator Keisal Peters echoed these concerns, pressing the government to disclose a clear pipeline of pre-vetted eligible projects before pursuing future CAF disbursements, and noting that the membership legislation should never be interpreted as a blank cheque for unvetted public spending. Friday responded by confirming that every future financing request to CAF will undergo full independent assessment to confirm it serves the national public interest before receiving government approval.
-
The Grenadian Economy: A 50-year snapshot
This analysis, authored by Kari Grenade, PhD, a Caribbean economist and macroeconomic advisor, traces Grenada’s half-century journey of economic evolution, marked by landmark wins, devastating setbacks, and persistent, targeted efforts to build a shock-proof national economy.
The early 1970s emerged as a period of widespread upheaval across economic, social, and political spheres. Years of systemic political repression paired with cascading economic and social crises between 1974 and 1975 paved the way for the People’s Revolutionary Government (PRG) to assume power in March 1979. Inheriting a deeply strained economic landscape, the new administration launched an International Monetary Fund (IMF) support program that November, rolling out an ambitious state-led development agenda focused on boosting national self-sufficiency and lifting living standards for all Grenadians. Following the collapse of the PRG in 1983, policymakers rolled out critical fiscal reforms, including a 1986 Value Added Tax (VAT) rollout that was later repealed. Even so, runaway public spending during the revolutionary era pushed the average overall fiscal deficit to 3.2% of GDP and average public debt to 42.3% of GDP over the 10-year period ending 1989 — the highest such metrics across the entire Eastern Caribbean Currency Union at the time. While headline economic growth averaged 5% across the decade, performance was highly inconsistent across years. The core takeaway from that era remains deeply relevant today: public investment can drive inclusive growth, but unmoored spending that far outstrips revenue and poorly managed borrowing will inevitably create fiscal bottlenecks that stifle long-term progress.
The 1990s saw targeted economic reforms and a vibrant private sector sustain steady growth and employment, with average annual GDP expansion hitting 3.5%. Yet sustained fiscal expansion created new strains, pushing average public debt for the decade to 48% of GDP. The defining policy challenge of balancing robust growth with sustainable debt and deficit levels ultimately went unaddressed, setting the stage for deeper instability in the years that followed.
The 2000s stand as one of Grenada’s most economically punishing decades. The country opened the decade in recession in 2001, triggered by a collapse in tourism demand in the wake of the 9/11 terrorist attacks in the United States. Two successive catastrophic storms — Hurricane Ivan in 2004 and the less severe Hurricane Emily in 2005 — then laid waste to large swathes of national infrastructure. Just as reconstruction efforts began to gain traction, Grenada was hit by the 2007 global food and fuel price shock, followed by the 2008 worldwide financial crisis, which further eroded growth and put unprecedented pressure on public finances. While the decade had bright spots, including economic activity spurred by post-hurricane rebuilding, construction of two national stadiums and a new cruise terminal, and hosting duties for select 2007 Cricket World Cup matches, these gains were nowhere near large enough to offset the cumulative impact of successive external shocks. The end result was a years-long stretch of economic stagnation marked by rising joblessness and a deepening fiscal crisis. Grenada posted a fiscal deficit every year between 2000 and 2009 save for 2005, averaging 4.6% of GDP across the decade. As a result, public debt surged to 93% of GDP by 2009, nearly double its level at the start of the 2000s, while average annual economic growth crawled to just 2.2%.
The 2010s represented a historic turning point for Grenada’s economic governance. A suite of sweeping fiscal reforms was rolled out, including the reintroduction of VAT in 2010, a landmark national debt restructuring in 2013, and the adoption of a legally binding, rules-based fiscal framework in 2015. Implemented as part of consecutive IMF-supported structural adjustment programs, these measures were designed to place public finances on a long-term sustainable footing and reverse the cycle of chronic deficits and runaway debt that defined the prior decade. Paired with strong broad-based economic growth, the reforms created critical new fiscal breathing room and drove a dramatic reduction in national debt. The outcomes were transformative: in 2015, GDP growth hit 6.4%, making Grenada the fastest-growing economy across the Caribbean Community (CARICOM) that year, with average growth for the full 2010s landing at 2.8%. Improved economic conditions drove a steep drop in unemployment, which plummeted from 30% in 2013 to 15.1% by 2019. Fiscal consolidation delivered equally striking results: the string of persistent deficits recorded from 2006 through 2015 was fully reversed, and public debt fell sharply from its 2013 peak of 104% of GDP to 57.9% by 2019.
This strengthened fiscal position meant Grenada entered the 2020 COVID-19 pandemic with far more policy flexibility than it had possessed a decade prior. Though the near-total collapse of the tourism sector triggered a 13.8% economic contraction in 2020, recovery began in 2021 and accelerated sharply in 2022 as tourist arrivals rebounded and construction activity picked up steam.
The 2021 to 2025 period underscored the tangible value of the prior decade’s structural reforms. Grenada was able to mount effective responses to overlapping crises: the lingering COVID-19 public health and economic fallout, the 2022 global food and energy price shock, and the catastrophic passage of Hurricane Beryl, without slipping back into the unsustainable debt trajectories of the past. Average economic growth hit a robust 5.1% across the five-year window, and labour market conditions improved dramatically. The latest National Labour Force Survey data shows total employed persons reached 49,258 in the third quarter of 2025, a jump of 5,323 compared to the same quarter in 2024, pushing national unemployment down to a historic low of 7.5%. Employment remains concentrated in key sectors including construction, wholesale and retail trade, motor vehicle repair, accommodation and food services, education, and health and social work.
The 2025 fiscal deficit, driven largely by high-priority, long-overdue public investments, remains fully manageable, and has been financed primarily by drawing down the government’s accumulated deposits held in the domestic banking system. Data published by the Eastern Caribbean Central Bank shows government deposits fell from EC$1.0 billion in 2024 to EC$814.3 million in 2025. With remaining deposit buffers still substantial, the 2026 projected fiscal deficit is also expected to be funded mostly from accumulated savings, with only a small share covered by new borrowing. The legislated fiscal rules are scheduled to be reinstated starting in 2027, requiring the government to run a primary surplus (total revenue and grants minus non-interest expenditure) of at least 1.5% of GDP annually, unless the rules are formally suspended under legally defined crisis conditions. As a result, the national public debt target of 60% of GDP is now on track to be met by 2033, two full years ahead of the original timeline.
Returning to consistent fiscal surpluses after two consecutive years of deficits will require targeted efforts to boost revenue collection. Full implementation of the already legislated Digital Services Tax will be a critical step, alongside measures to strengthen revenue administration, improve tax compliance and enforcement, close unproductive tax loopholes, and tighten controls on public spending.
Against a backdrop of growing global economic volatility, Grenada must move deliberately to protect its hard-won fiscal stability. Policy proposals that would weaken the national fiscal position — such as unfunded tax cuts or hikes to tax-free income thresholds with no offsetting revenue measures — are fiscally reckless and strongly ill-advised. While tax reductions are not inherently poor economic policy, their risks become acute when projected costs are underestimated, benefits are assumed rather than empirically verified, and no credible plan exists to close the resulting fiscal gap. Grenada’s fiscal rules are explicitly designed to enforce expenditure discipline and ensure sufficient revenue is generated to fund core government operations while keeping public debt on a sustainable path. Any proposed tax cut must be paired with offsetting spending reductions, alternative revenue streams, or other credible financing mechanisms to ensure full compliance with the legislated fiscal framework. More fundamentally, tax policy should be embedded in a broader national economic strategy focused on lifting productivity, incentivizing domestic and foreign investment, expanding quality employment, and strengthening overall economic resilience. In small, highly open economies like Grenada, poorly designed tax cuts tend to deepen import dependence by driving higher consumption of imported goods and services, fuel inflationary pressures, and perpetuate a high cost of living. Furthermore, tax reductions in isolation cannot stimulate broad economic activity if local businesses continue to face binding constraints including underdeveloped critical infrastructure, skilled labour shortages, high operating costs, and limited access to affordable financing.
Looking ahead, headline economic growth is projected to moderate to roughly 2.7% by 2029, and significant downside risks to the outlook remain. Grenada must therefore continue to build larger fiscal buffers, upgrade tax administration and compliance systems, refine public expenditure management, and scale up strategic investments in climate-resilient infrastructure, digital transformation, and human capital development. Sustained investment in training and upskilling public sector employees is also required to boost productivity, professionalism, and service delivery across all government agencies. In parallel, ongoing efforts to streamline the business environment will support greater innovation, entrepreneurship, and new job creation.
These are unprecedented times, and incremental, conventional policy solutions will not be sufficient to navigate coming challenges. In a global landscape defined by rising uncertainty and growing systemic vulnerabilities, Grenada cannot afford complacency. The economic progress delivered over the past decade is substantial, but preserving and building on those gains will require unwavering commitment to sound, evidence-based economic and fiscal management. It will demand discipline, strategic foresight, competent implementation, and strong leadership, alongside expanded social and environmental security, a fundamental shift in national mindset from focusing on limitations to unlocking new opportunities, and a shared cross-societal commitment to collective responsibility for Grenada’s future development. -
TSTT seeks relief from financial pressures
Trinidad and Tobago’s state-owned incumbent telecommunications provider, Telecommunications Services of Trinidad and Tobago Ltd (TSTT), has rolled out a landmark liability management initiative that targets raising up to TTD $1.156 billion from domestic investors as part of a broader US$500 million (equivalent to TTD $3.4 billion) senior secured bond issuance, designed to restructure its existing debt obligations and alleviate near-term financial strain. Global credit rating agency S&P Global Ratings has assigned the forthcoming 10-year notes a “BB-” rating, aligned with TSTT’s standalone issuer credit rating, confirming no meaningful shift in the firm’s underlying credit risk profile post-transaction. Structured as a 10-year soft bullet instrument, the new notes will feature equal semi-annual principal amortization payments spread across the final three years of their tenor, and will be split into two tranches denominated in US dollars and local Trinidad and Tobago dollars, with the final allocation between the two currencies calibrated in line with real-time market demand and execution feasibility. Preliminary offering documents for the local currency tranche indicate an estimated 8.8% coupon rate and a projected 8% yield to maturity for domestic investors. All net proceeds from the issuance will be directed toward refinancing TSTT’s outstanding legacy debt, as well as covering associated transaction fees, legal costs, and administrative expenses tied to the refinancing exercise. S&P’s analysis of TSTT’s debt profile as of March 31, 2026, outlines the firm’s current obligations include US$300 million in 8.875% interest senior secured notes, TTD-denominated notes carrying 8.3% interest, an additional TTD $476 million in outstanding notes, and a $100 million commercial paper facility. The existing senior secured notes are currently set to mature in October 2029, with principal repayments scheduled to kick off in six semi-annual instalments starting April 18, 2027. The newly proposed notes will carry identical senior secured status to the 2029 legacy notes, using the exact same collateral package that backs the existing secured bond stack, and S&P projects TSTT will fully retire all of the 2029 notes without retaining any residual holdout balances. This refinancing operation will extend TSTT’s overall debt maturity profile to an average life of nine years, a move that effectively eliminates looming short-term liquidity pressures that could have emerged as the 2027 repayment start date for the legacy notes approaches. S&P has classified the entire transaction as “100% debt neutral”, meaning no material net increase in TSTT’s total outstanding debt will occur as a result of the issuance. The rating agency forecasts TSTT’s adjusted debt-to-EBITDA ratio, a core metric for measuring corporate debt servicing capacity, will hold steady at roughly 4 times earnings or fall lower over the 12-month outlook. The matching “BB-” rating for the new notes and TSTT’s core issuer credit rating also confirms there will be no meaningful subordination risk across the company’s capital structure once the refinancing is completed.
-
Luxury, culture and sunshine fuel Barbados’ winter appeal
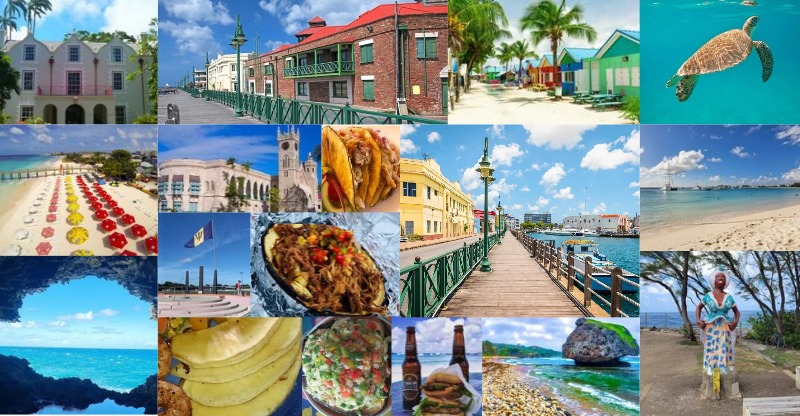
Barbados, the gem of the southern Caribbean, is emerging as a leading top-tier destination for the 2026 winter travel season, according to a new analysis from global travel industry publication Travel And Tour World. The island’s diverse geographic offerings span the serene, turquoise sheltered bays of Carlisle Bay, famed for its gentle swimming conditions and frequent sea turtle sightings, to the rugged, wind-swept Atlantic coast of Bathsheba, a world-renowned hub for surfers and nature photographers alike. Adding a rich cultural layer to its natural allure, the capital city of Bridgetown and its adjacent Historic Garrison hold prestigious UNESCO World Heritage Site status, granting visitors immersive access to Barbados’ layered colonial and post-independence history, and a tangible connection to the island’s distinct national identity. As the globally recognized birthplace of rum, Barbados leverages its decades-long legacy of distillation to curate a one-of-a-kind culinary and beverage landscape, ranging from no-frills, community-focused local rum shops serving generations of residents and visitors, vibrant street food stalls dishing out Bajan classics like flying fish and cou-cou, to award-winning fine-dining establishments that blend local flavors with international gastronomic techniques. The island’s robust, purpose-built tourism ecosystem is cited as a core competitive edge: its accommodation portfolio spans ultra-luxury five-star resorts, intimate boutique beachfront properties, dedicated wellness retreats focused on holistic health and tropical healing, and a wide array of family-friendly attractions designed to cater to travelers of all age groups. This diverse offering is further supported by well-established, frequent international airlift routes from North America, Europe and neighboring Caribbean islands, plus a mature network of visitor services that ensure smooth, hassle-free travel experiences for arriving guests. Anup Kumar Keshan, Founder, Chief Executive Officer and Editor-in-Chief of Travel And Tour World, emphasized that Barbados’ unmatched market advantage stems from its ability to deliver a fully integrated, end-to-end holiday experience that no competing regional destination can match. “The island’s unique strength comes from its seamless fusion of upscale luxury, living cultural heritage, outdoor adventure opportunities, and unfiltered, authentic local interactions, all packaged into one cohesive, unforgettable travel journey,” Keshan explained. He noted that the broader Caribbean winter travel segment has grown increasingly crowded and competitive in recent years, with peer destinations including Saint Lucia, Aruba, Curaçao, the Dominican Republic and Jamaica all vying for a larger share of global tourist arrivals. Even amid this intense landscape, destinations that prioritize crafting distinct, memorable experiences rather than generic sun-and-sand packages will continue to capture the lion’s share of traveler attention. “Barbados’ rare ability to balance laid-back, restorative relaxation with meaningful, discovery-driven exploration makes it a clear standout choice for travelers planning their 2026 winter getaways,” Keshan added. “This trend makes clear that the future of island tourism is no longer defined solely by the location a visitor travels to, but by the lasting, personal memories they get to take home with them.” The report also highlights iconic local landmarks that anchor Barbados’ tourism appeal, including the limestone formations of Animal Flower Cave and Harrison’s Cave, the historic Old Spirit Bond Mall in central Bridgetown, the vibrantly colored traditional residential homes scattered across the island’s countryside, and the well-preserved colonial architecture of St Nicholas Abbey Great House, one of the oldest surviving sugar plantation estates in the Caribbean.
-
Private conflict resolution takes less than two years
Santo Domingo – Alejandra Vanessa Díaz Reyes, General Secretary of the Court and Alternative Conflict Resolution body at the Santo Domingo Chamber of Commerce and Production (CCPSD), has laid out the transformative impact of sweeping new arbitration regulations set to take effect across the Dominican Republic on November 2, 2026. The revised framework replaces the chamber’s outdated 2011 arbitration rules, which have not kept pace with the dramatic evolution of global and local business practices over the past 15 years, and aligns local dispute resolution standards with leading international arbitration norms.
Díaz Reyes explained that the independent CCPSD arbitration body, governed by a 14-member cross-sector board of lawyers, industry experts, and business leaders under the leadership of chair Ramón Ortega, was driven to update its rules in response to surging demand for alternative dispute resolution that avoids the systemic backlogs, multi-layered appeals processes, and unpredictable timelines that plague the country’s overstretched ordinary judicial system. Data from the chamber shows that arbitration caseloads administered by the Santo Domingo Court of Arbitration have skyrocketed 86% between 2015 and 2025, with 41% of these cases classified as cross-border international disputes. Over the past decade, case volumes have risen sharply across high-priority economic sectors including manufacturing, telecommunications, banking and finance, construction, and trusts, alongside a growing share of disputes between private citizens, commercial entities, and state institutions.
The new regulatory package introduces a suite of targeted upgrades: full end-to-end digitalization of case workflows, the formal introduction of the emergency arbitrator role to deliver rapid interim relief for time-sensitive disputes, and structural adjustments to enhance overall procedural efficiency, transparency, and enforceability. Unlike ordinary court proceedings, which can drag on for years as cases move through lower courts, appeals, cassation reviews, the Supreme Court of Justice, and even the Constitutional Court, arbitration awards under the updated framework are final and binding with no further right of appeal, with nearly all cases reaching a definitive resolution in under 24 months.
Díaz Reyes emphasized that the system delivers unmatched predictability for users: all administrative and arbitrator fees are fully calculable via a public online tool on the CCPSD website, with costs scaled directly to the value of the dispute at hand. The chamber’s curated roster of pre-vetted arbitrators spans specialized fields beyond legal practice, including civil engineering, economics, and technology, ensuring that dispute panels have targeted industry expertise relevant to the specific controversy. Parties can opt into arbitration either by including a CCPSD arbitration clause in their commercial contracts before a dispute arises, or by mutual agreement after a conflict emerges to bypass the public court system entirely. Beyond commercial disputes, the arbitration service also supports resolution of condominium ownership conflicts and non-payment claims, as long as all involved parties consent to the process.
With 42% of current CCPSD active cases involving cross-border stakeholders, the updated rules are positioned to strengthen the Dominican Republic’s profile as a reliable, investor-friendly jurisdiction by reinforcing legal certainty for both domestic and international business communities.