分类: business

  • Starlink raises Jamaica’s monthly internet price by 6.4 per cent

    Starlink raises Jamaica’s monthly internet price by 6.4 per cent

    KINGSTON, Jamaica — Elon Musk’s SpaceX-operated satellite internet firm Starlink has implemented a 6.4% monthly price hike for its residential internet subscriptions in Jamaica, raising the standard rate from $7,000 Jamaican dollars to $7,450 Jamaican dollars. The new pricing structure is scheduled to go into effect starting June 18, with the adjustment applying to all customer billing cycles that fall on or after that date.

    The price change was formally announced to existing subscribers via a company email notification, which clarified when users would begin seeing the updated charge on their monthly bills. According to the statement shared with customers, the price increase is directly tied to Starlink’s ongoing efforts to scale up its network capacity, extend geographic coverage, and boost service reliability across the island. These upgrades are being rolled out to keep pace with rapidly growing consumer demand for high-speed internet access in Jamaica.

    “Robust consumer demand for Starlink services is a testament to the value we deliver through continuous investment in affordable, high-performance connectivity. At the same time, global operating costs have continued an upward trajectory across the industry,” the company explained in the customer notice.

    Starlink also emphasized that despite the price adjustment, subscribers will retain their unlimited data access, a key selling point that supports common high-bandwidth activities including 4K media streaming, online gaming, remote work video conferencing, and consistent high-speed connectivity for daily digital needs.

    This price adjustment arrives at a moment when demand for alternative internet solutions is surging across Jamaica and the broader Caribbean region. Many rural and underserved communities across the area still lack robust fiber-optic broadband infrastructure, leaving residents with limited options for reliable high-speed connectivity. Starlink’s low-Earth orbit satellite network has filled this critical gap, quickly gaining traction by delivering service to areas long ignored by traditional terrestrial internet providers.

    As a global operator, Starlink’s pricing change also mirrors broader industry trends. Inflationary pressures have hit telecommunications and digital infrastructure providers worldwide over the past several years, with most companies facing sharp increases in the cost of manufacturing equipment, launching satellites, and maintaining day-to-day operations. Starlink is far from alone in passing a portion of these increased costs onto consumers as it continues its aggressive global expansion push.

    Since its commercial launch, Starlink has grown into one of the world’s largest satellite internet providers, deploying thousands of low-Earth orbit satellites to deliver broadband connectivity to underserved markets across every inhabited continent. Its expansion in the Caribbean has been particularly rapid, as regional governments and consumers look for options to close the digital divide between urban centers and isolated rural communities.

  • OP-ED: Beyond the boom -The ECCU’s decade of decision

    OP-ED: Beyond the boom -The ECCU’s decade of decision

    Six years after a 2020 analysis warned that the Eastern Caribbean Currency Union (ECCU)’s overreliance on tourism exposed the bloc to dangerous, unaddressed concentration risk, new economic data confirms the original thesis while revealing a shifting landscape of threats and underdeveloped growth opportunities for the small island bloc. In this updated commentary, veteran Caribbean finance executive Fletcher St. Jean revisits his 2020 framework, incorporating half a decade of new data, systemic global shocks, and unprecedented institutional shifts to offer a refreshed strategic roadmap for the region’s leaders.

    The 2020 prediction that tourism would retain its position as the ECCU’s primary economic engine has been fully vindicated, per the Eastern Caribbean Central Bank (ECCB)’s 2024-2025 Annual Report. Visitor arrivals across most member states have surpassed pre-pandemic peaks, expanded construction activity has lifted fixed investment, and the bloc’s average debt-to-GDP ratio has edged down from 77% to 76% — marking the first sustained improvement in the metric since 2008. But this impressive recovery has come at a cost: it has deepened, rather than relieved, the concentration risk the 2020 analysis flagged. Before COVID-19, tourism contributed 30% to 40% of total GDP across the ECCU, and accounted for more than half of foreign exchange earnings in several member states. Today, that reliance is even greater, leaving the bloc just one global shock away from systemic economic collapse. The ECCB itself has acknowledged that its ambitious “Big Push” goal — doubling the size of the ECCU economy over the next 10 years — cannot be achieved by expanding tourism alone. After decades of discussing economic diversification as a theoretical priority, the bloc must now move from policy communiques to tangible implementation.

    Of all the shifts that have reshaped the ECCU’s economic landscape since 2020, the transformation of the bloc’s Citizenship by Investment (CBI) programs is the most rapid and high-stakes. Where the 2020 analysis only noted growing external pressure on CBI from major global powers, the question in 2026 is whether existing CBI models will survive to the end of the decade. Three landmark developments have altered the operating environment permanently: the United Kingdom revoked visa-free access for Dominican passport holders in 2023 over CBI due diligence concerns; the European Court of Justice ruled Malta’s investor citizenship program illegal in 2025, establishing a precedent that bans transactional citizenship schemes; and the European Commission’s 2025 Visa Suspension Mechanism report confirmed that operating CBI programs alone qualifies as grounds for revoking Schengen visa-free access.

    In response, ECCU member states have carried out the most sweeping institutional reform of CBI in the program’s 40-year history. A 92-article draft agreement signed in July 2025 established the Eastern Caribbean Citizenship by Investment Regulatory Authority (ECCIRA), a supranational regulator headquartered in Grenada that will launch operations in early 2026. The new regime introduces a harmonized $200,000 minimum investment floor, mandatory biometric due diligence, required applicant interviews, annual application caps, a 30-day in-country residency requirement, and five-year initial passport validity tied to ongoing compliance. While the reforms address international credibility concerns, they have already delivered significant fiscal headwinds: St. Kitts and Nevis recorded a 60% drop in CBI revenue in 2024 alone, pushing its budget deficit to an estimated 11% of GDP. For member states that have long relied on CBI inflows to fund capital projects, the new regime means a structurally lower revenue ceiling, forcing leaders to rethink how they deploy the capital CBI still generates. For St. Jean, this shifting landscape opens a clear path to pivot toward the ECCU’s most underexploited high-growth sector: medical tourism.

    The global medical tourism industry is one of the fastest-growing service sectors worldwide, valued at an estimated $76 billion in 2025 and projected to hit $174 billion by 2035, with an 8.4% compound annual growth rate. Regional peers have already capitalized on this boom: Barbados built a $538 million medical tourism sector by 2024, projected to reach nearly $950 billion by 2034, while the Cayman Islands’ Health City has proven that a single well-capitalized, internationally accredited tertiary facility can transform a small island’s healthcare and economic profile. The ECCU, by contrast, has negligible market share, despite holding natural advantages including ideal geography, climate, and proximity to major source markets in North America. The gap stems not from a lack of potential, but from a failure to allocate sufficient capital to upgrade local tertiary facilities to meet international accreditation standards, leaving the multi-hundred-million-dollar opportunity to regional competitors.

    St. Jean argues that redirecting a portion of declining CBI revenue into medical tourism delivers three simultaneous strategic benefits: it creates a durable new export sector to generate foreign exchange, it lifts the quality of domestic healthcare for ECCU citizens, and it demonstrates to international partners that CBI capital is deployed for genuine, sustainable development. His concrete proposal calls for member states to earmark a minimum 25% of net CBI inflows to a dedicated Regional Medical Excellence Fund (RMEF). The fund would be used to build or upgrade one internationally accredited tertiary specialty center per member state, with distributed specialty focuses across the bloc to avoid redundant competition. High-demand specialties including cardiology, orthopaedics, oncology, fertility treatment, renal care, and rehabilitation medicine all play to the ECCU’s competitive advantage on cost, quality, and climate, the key drivers of patient choice in medical tourism. St. Jean projects that a single mid-sized specialty center attracting 700 to 1,000 international patients annually would generate $17 million to $25 million in gross revenue per year. Across the bloc’s seven member states, properly specialized medical tourism could generate $150 million to $250 million in annual revenue within a decade — a total that compares favorably to declining CBI revenues, and is far more economically durable. Every year of delayed action only makes capturing market share more difficult, St. Jean warns.

    Beyond shifts in CBI and medical tourism, the ECCU now faces a historic global energy supply shock triggered by the February 2026 closure of the Strait of Hormuz following armed hostilities. The International Energy Agency has called this the greatest threat to global energy security in history, with daily ship transits falling from 130 in February to just 6 in March. Brent crude prices, which averaged $67.74 in 2025, spiked 65% at the peak of the crisis and remain above $100 per barrel even after an April ceasefire. For the ECCU, which imports nearly 100% of its energy as refined petroleum products, the impacts are immediate: higher energy costs push up electricity prices, transportation fares, and food prices (driven by spiking fertilizer costs, as more than 30% of global urea trade passes through the Strait of Hormuz), while eroding tourism operating margins. While the Eastern Caribbean dollar’s peg to the U.S. dollar protects the bloc from currency-driven import inflation, it does not offset underlying global price increases already visible in 2026 early data.

    The crisis has also accelerated a hemispheric energy realignment that has been unfolding since Guyana began commercial oil production in 2019. By February 2026, Guyana was producing 926,550 barrels of oil per day from the Stabroek Block, overtaking Venezuela to become South America’s second-largest oil producer, with output projected to hit 1.7 million barrels per day by 2030. The Guyanese economy grew 19.3% in real terms in 2025, with a further 16.2% growth projected for 2026. Critically for the ECCU, Guyana is now transitioning from a pure oil producer to a potential regional energy supplier. Its Liza gas-to-energy project, on track to launch by the end of 2026, will supply natural gas to a 300-megawatt domestic power plant, displacing expensive fuel oil. ExxonMobil’s proposed Longtail development could eventually deliver up to 1.5 billion cubic feet of natural gas per day through a dedicated LNG export facility. With many Caribbean countries spending up to 15% of GDP on fuel imports for power generation, and traditional regional supplier Trinidad and Tobago seeing LNG exports fall 40% since the pandemic, a regional energy partnership with Guyana is no longer a hypothetical. ECCU member states that position themselves as anchor offtake partners between 2026 and 2028 will lock in far better long-term energy prices than those that delay action, St. Jean argues.

    On the food security front, the 2020 analysis called for greater public investment in commercial agriculture and fisheries, lower borrowing costs for farmers, and a fully functional internal market for regional agricultural goods. CARICOM responded with the “25 by 2025” initiative, which aimed to cut the bloc’s $6 billion annual food import bill by 25% by the end of 2025. The target was not met, and the initiative was extended to 2030 and rebranded “25 by 2025+5” at the 48th CARICOM Heads of Government Meeting in February 2025. The extension reflects both significant headwinds — including Hurricane Beryl in 2024, global commodity price spikes, and the 2026 Hormuz crisis driving up fertilizer costs — and genuine progress: regional food production rose 23.1% between 2020 and 2024, with production achievement rates climbing from 57% in 2022 to 82% in 2024. CARICOM’s new target calls for 4.3 million tons of regional food production by 2030.

    For the ECCU specifically, which does not benefit from Guyana’s massive agricultural capacity that skews the CARICOM aggregate, achieving meaningful food security requires a targeted, four-pronged strategy, per St. Jean: first, establish a regional Agricultural Credit Guarantee Facility capitalized by the ECCB, Caribbean Development Bank (CDB), and member governments to cut borrowing costs for qualified commercial farmers from the current 10% to 12% range to a globally competitive 4% to 6% — eliminating the cost gap that is the primary barrier to agricultural competitiveness. Second, mandate that a minimum 35% of food served in ECCU hotels, hospitals, schools, and government facilities be sourced from regional producers by 2030, creating guaranteed offtake that mobilizes private investment at no cost to public budgets. Third, treat the ECCU’s 600,000+ square kilometer exclusive economic zone as the strategic economic asset it is, unlocking revenue from commercial fisheries, aquaculture, sustainable mariculture, and sargassum valorization, which are currently treated as environmental liabilities in national budgets. Fourth, remove remaining internal barriers to intra-regional agricultural trade within the ECCU and CARICOM, closing the longstanding anomaly of free labor movement without free movement of goods that can be addressed at zero fiscal cost.

    In February 2026, the CDB approved its 2026-2035 Strategic Plan, themed “Innovate. Transform. Thrive.” CDB President Daniel M. Best has framed this period as the Caribbean’s “decade of decision,” estimating the region will need $65.2 billion between 2024 and 2033 just to avoid economic stagnation, with that figure doubling if the bloc pursues meaningful climate adaptation, infrastructure upgrades, and fiscal buffer building. The plan is built around three interconnected pillars: Social Resilience, Economic Resilience, and Environmental Resilience, anchored by a core commitment to poverty reduction. All the priorities St. Jean outlines in this commentary — economic diversification, food security, healthcare modernization, energy transition, and climate adaptation — align directly with the CDB’s framework. Critically, the CDB retains its AA+ credit rating, has secured new capital through multiple global issuances, and now holds more lending capacity than at any point in its history. St. Jean urges ECCU member states and the ECCB to use 2026 and 2027 to align national development plans, the ECCB’s “Big Push,” the OECS Development Strategy, and national budget cycles with the CDB’s three pillars. Member states that come with credible, aligned project pipelines will capture a disproportionate share of the bank’s available capital, he notes.

    Drawing on six years of new data and shifting conditions, St. Jean offers eight updated core priorities for ECCU leaders, regional institutions, and the private sector: translate the ECCB’s “Big Push” doubling target into measurable, country-level diversification milestones; establish the Regional Medical Excellence Fund funded by 25% of net CBI inflows to build accredited tertiary medical centers across the bloc; treat the CBI revenue decline as a structural fiscal challenge rather than a temporary cyclical shift and require high-dependency member states to publish formal transition plans; negotiate a regional energy partnership with Guyana before 2029 to reduce dependence on imported fuel oil; establish a regional agricultural credit guarantee facility to cut farmer borrowing costs to globally competitive levels; use the ECCIRA supranational regulatory model for CBI as a template for other sectors including digital assets, agricultural standards, healthcare accreditation, and financial services; align all major national investment plans with the CDB’s three resilience pillars to access available financing; and create a coordinated ECCU implementation framework for the Bridgetown Initiative, the global reform agenda for climate-vulnerable small island states, to unlock climate finance and align international advocacy with regional priorities.

    In conclusion, St. Jean reaffirms that six years after the 2020 analysis, tourism remains the ECCU’s economic backbone, but concentration risk has been deepened rather than resolved, compounded by existential pressure on CBI, an unpredictable global energy crisis, and a once-in-a-generation opportunity in medical tourism that the region has yet to seize. Today, the ECCU holds more institutional capacity than at any point in three decades, from the ECCB’s “Big Push” and ECCIRA to the CDB’s expanded financing capacity and the Bridgetown Initiative’s global climate finance framework. Turning these platforms into tangible, diversified, resilient economic growth depends entirely on whether member states choose to act in concert, rather than in parallel. As the CDB’s Best has labeled this the Caribbean’s decade of decision, decisive action in 2026 and 2027 will leave the bloc far stronger, more resilient, and more prosperous by 2035, while delay will leave the region playing catch-up to global shifts, as happened when preferential agricultural trade collapsed in the 1990s. As the 2020 analysis concluded, economic diversification is the difference between proactive strategy and reactive crisis management — a truth that remains urgent for the ECCU’s defining decade.
  • Salt+Sand freshens up Negril’s 7-mile beach

    Salt+Sand freshens up Negril’s 7-mile beach

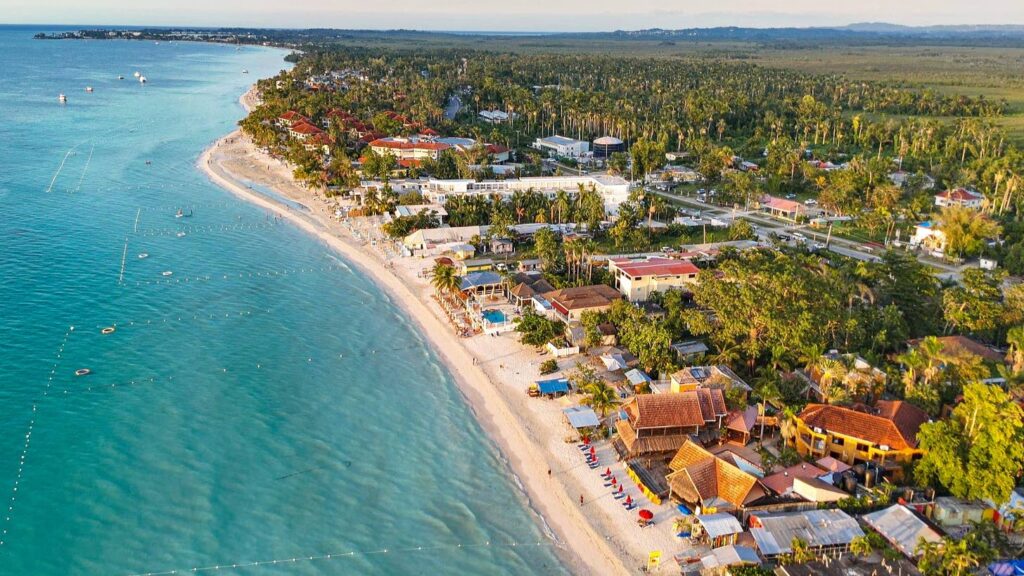
    Nestled along Jamaica’s world-famous Negril Seven-Mile Beach, a piece of local vacation history is undergoing a dramatic rebirth as a new boutique beachfront development that balances modern luxury with authentic Jamaican culture. Spearheaded by Canadian investment and redevelopment collective Salt+Sand, the Salt+Sand Deh Yah project will convert the long-vacant former resort site into 22 high-end condo-hotels, with construction on track to wrap by the end of 2025.

    The prime beachfront parcel carries decades of legacy as a go-to spot for low-stress Jamaican getaways. First developed as the three-star Sea Splash Resort, it gained widespread acclaim for its on-site eatery Norma’s, which drew visitors from across the island with its signature local cuisine. After original owner Patrick Lawe sold the property, it reopened as the VickiTini Beach Resort, which operated until permanently closing its doors in July 2025. For the Salt+Sand leadership team—led by 28-year-old Canadian real estate investor Sutton McKay, alongside co-founders Lena Langille and Negril-based veteran realtor Maura Watson—the vacant property represented far more than a typical real estate acquisition.

    The team had been in negotiations with the property’s sellers since 2024, and when the site became available full-time, they jumped at the chance to revitalize the space without erasing its unique cultural identity. “We’ve been in talks with the sellers since 2024. When the property sat vacant, we saw a huge opportunity — not just to purchase a beachfront asset, but to bring it back to life and optimise it to its full potential. We didn’t want to erase the soul of the property; we wanted to modernise it while still staying true to the authentic Jamaican energy and culture that makes Negril so special,” McKay told Jamaica Observer’s Real Estate on the Rock.

    Watson, who has built an extensive portfolio of Negril-based properties and calls the town home, explained the meaning behind the project’s distinctive name, which reflects the team’s commitment to embracing local culture. “Jamaica is more than a place — it’s a feeling. The people, the food, the music, the laid-back lifestyle, and the culture are what made all of us fall in love with Negril in the first place. That’s why we named the property Salt+Sand Deh Yah,” she said. “‘Deh Yah’ in Jamaican Patois means ‘I’m here’ and, for us, it represents being present, slowing down, and truly experiencing the vibe and culture of Negril. Our goal is for every investor and future guest to feel the same connection to Jamaica and Negril that we do: peace, love, and reggae music.”

    Langille, who brings extensive Canadian real estate experience from Nova Scotia to the project, oversees branding, marketing, design, and redevelopment strategy for the team. She noted that early buyer interest has already exceeded expectations, with roughly half of all units sold within the first two weeks of listing earlier this year. Units officially went on the market between late January and early February 2025, priced from $249,000 to $550,000 USD. The strong early sales, Langille added, reflect growing global investor confidence in Jamaica’s booming tourism economy. “As a team, we saw a tremendous amount of opportunity in Jamaica. We genuinely love real estate, design, hospitality, and working with investors who also see long-term opportunity and potential. We’ve also been incredibly impressed with the strength of Jamaica’s tourism economy and the level of interest from foreign investors — selling approximately 50 per cent of the project within the first two weeks alone,” she said. Beyond the current development, Langille confirmed that Salt+Sand is positioned as a growing hospitality and investment brand, with additional Jamaican projects already in early exploration.

    Unlike the site’s previous iteration as a traditional full-service resort, Salt+Sand Deh Yah will operate under a flexible condo-hotel model that benefits private unit owners. When owners are not using their personal beachfront retreat, they can generate rental income by making the space available to short-term guests. Local luxury hospitality firm South Coast Villas will handle all property management, short-term rental operations, and concierge services for owners who choose this option. The original 20 units from the former VickiTini resort will be expanded by two additional condos to reach the final count of 22, with three unit tiers available: 240-square-foot standard units, 450-square-foot deluxe units that include private balcony space, and 700-square-foot loft suites.

    The $18.1 million USD total redevelopment investment is split between equity and financing, with a phased renovation plan designed to deliver a strong long-term foundation for the property. The first round of upgrades focuses entirely on critical infrastructure and operational improvements, including brand-new plumbing lines, full solar panel installation, a modern backup generator system, and a sub-metered RUBS utility allocation system that fairly splits utility costs between owners based on unit size and occupancy. The second major construction phase is scheduled to kick off in mid-June 2025, and will focus on cosmetic and guest-focused lifestyle upgrades. This phase includes exterior repainting and refinishing, new perimeter fencing, updated tile work, pool refurbishment, new furnishings across all units, a full upgrade of the property’s bar and restaurant spaces, and the addition of a new wellness and fitness area. The team will also rebuild the original lobby, gift shop and excursion area—originally converted to storage under previous ownership—upgrade landscaping and common areas, and reconfigure underused space to accommodate the two additional condo units.

    To avoid common construction delays that often plague coastal developments, the team has implemented multiple contingency plans. All core materials are sourced locally to eliminate shipping hold-ups, and key materials have already been ordered ahead of the mid-June construction start. A pre-vetted local contractor will lead on-site construction management, with pre-approved backup contractors and subcontractors on call if needed. After months of pre-planning, the team will also use dedicated project tracking software to stay on schedule and on budget.

    Addressing common buyer concerns about regional infrastructure challenges, including periodic water shortages and power outages that impact many growing Jamaican tourism destinations, the Salt+Sand team has proactively upgraded on-site systems to boost self-sufficiency. Large backup water tanks are already in place to guarantee continuous water access, the new backup generator will ensure reliable power, and the expanded solar installation will allow the property to operate independently when regional utility service is interrupted.

    The project’s pre-existing strata zoning—granted in the 1990s—has been a major draw for international buyers, as it streamlines the legal ownership process and adds a layer of transparency that is rare for beachfront properties in the region. With extremely limited availability of titled beachfront condos on Seven-Mile Beach, remaining unsold units are expected to see a 15-20% price increase following the completion of renovations at the end of the year. Beyond the valuable zoning and prime location, buyers have also responded strongly to the project’s core mission: honoring Negril’s iconic laid-back, authentic vibe while adding modern upgrades that make relaxation easier than ever. For the Salt+Sand team, the development is perfectly positioned to grow alongside Negril’s rapid tourism evolution, delivering strong long-term returns for investors while giving guests and owners the iconic Jamaican beach experience they seek.

  • Why inflation is falling but Jamaicans still feel squeezed?

    Why inflation is falling but Jamaicans still feel squeezed?

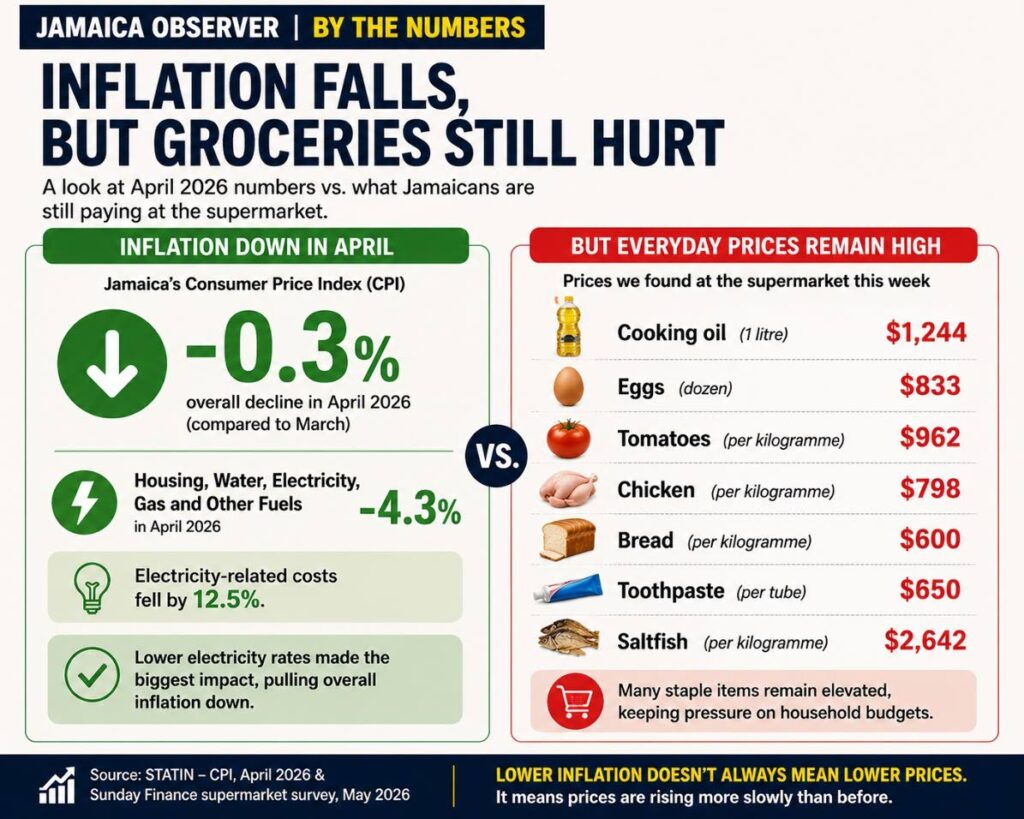
    Jamaica’s national inflation rate recorded another downward shift in April, with official data pointing to sharp drops in electricity costs as the primary driver. The Statistical Institute of Jamaica (Statin) announced that the country’s Consumer Price Index (CPI) fell by 0.3% for the month, a move that looks encouraging on paper but has failed to translate into tangible relief for the majority of Jamaican households.

    The reality on the ground tells a more complicated story: grocery costs remain elevated, petrol prices have climbed once again, rent stays at historically high levels, school fees are increasing, and dining out has grown more expensive. After years of consecutive price hikes triggered by the COVID-19 pandemic, global supply chain disruptions, and repeated hurricane damage to local infrastructure and agriculture, most families are still adjusting to a permanently higher cost of living that shows little sign of reversing.

    This gap between falling official inflation figures and widespread persistent financial pressure has emerged as one of the most widely misunderstood features of Jamaica’s current economy. The confusion stems from a common misinterpretation: lower inflation does not mean prices are decreasing across the board. Instead, it simply means that prices are rising at a slower pace than they were previously. In April’s case, the overall decline was only made possible by a single large category — electricity — dropping enough to cancel out price increases across every other major sector.

    Statin’s breakdown confirms this disparity: food prices rose by 0.6% in April, led by a dramatic 6.2% jump in the cost of fruits and nuts including ripe bananas, oranges, and watermelon. Higher petrol prices also pushed up overall transport costs for consumers and businesses alike. That means while the headline inflation number moved downward, most of the goods and services Jamaicans purchase on a regular basis continued to get more expensive.

    This mismatch explains why so many households still feel financially squeezed even though headline inflation now sits squarely within the Bank of Jamaica (BOJ)’s official target range, a development policymakers frame as a sign of economic stability.

    Clearing Up the Inflation Misconception

    A core source of public confusion is the frequent mixing up of inflation and general price levels. Inflation does not measure how cheap or expensive goods are — it measures the rate at which prices are changing over time. For example, if inflation falls from 8% to 4%, prices are still going up; they are just increasing at half the speed they were previously.

    After several years of sustained high inflation across the global economy, most prices remain far higher than they were in the pre-pandemic period. A family that once spent JMD 15,000 a week on groceries may now pay JMD 23,000 or more for the same basket of goods. Even if inflation slows sharply, prices almost never drop back to their previous levels, leaving families permanently adjusting to higher costs. This is the key reason official inflation statistics and everyday lived experience so often feel out of alignment: official numbers may show stabilizing price growth, but consumers are still dealing with long-term financial fatigue from cumulative increases.

    Electricity Carries the Weight of April’s Decline

    April’s drop in inflation was driven almost entirely by a single factor: falling electricity costs. Statin reports that the “Housing, Water, Electricity, Gas and Other Fuels” category fell by 4.3% in April, after electricity costs themselves dropped by 12.5%. This shift is economically significant, because electricity touches nearly every part of the national economy. Lower electricity costs can reduce pressure on businesses, transport operators, manufacturers, distribution networks, and household budgets all at the same time.

    Over the past year, Jamaica’s inflation trends have increasingly been shaped by movements in global energy prices, paired with weather-related disruptions to local food production. When global oil prices ease and fuel-related utility charges fall, inflation tends to soften quickly. Food prices, by contrast, follow a much more volatile pattern.

    Agricultural prices remain extremely vulnerable to droughts, hurricanes, supply chain breakdowns, and seasonal shortages, and this volatility consistently shows up in monthly inflation data. Over the 12 months leading up to April, prices for fruits and nuts jumped 26.3%, while fish and seafood costs rose 11.4%, both adding steady upward pressure to household grocery budgets. This explains why consumers feel the impact of inflation most acutely at supermarkets and local markets, even when the overall headline inflation rate is moderating.

    What This Means for the Bank of Jamaica’s Policy

    The Bank of Jamaica does not aim to drive prices down across the entire economy — its core mandate is to prevent inflation from becoming unstable and eroding purchasing power too quickly. Sustained high inflation creates widespread economic uncertainty: businesses struggle to set accurate prices for goods and services, borrowing becomes riskier for all parties, savings lose value more quickly, consumers delay major discretionary purchases, and long-term investment decisions become far harder to make.

    To avoid these outcomes, the BOJ targets an inflation range of 4% to 6%. April’s 4.3% year-over-year inflation rate falls comfortably within that target, a reading that is widely expected to reinforce the central bank’s plan to keep interest rates relatively stable when the Monetary Policy Committee meets later this month.

    Stable interest rates have direct benefits for consumers: higher rates push up the cost of mortgages, car loans, credit cards, and business borrowing, so holding rates steady eliminates the risk of even higher debt repayments for households and enterprises. But stable, moderate inflation does not immediately solve widespread affordability problems — it primarily prevents economic conditions from worsening more quickly than they otherwise would.

    The Long-Term Structural Shift in Living Costs

    What Jamaica appears to be entering right now is not a return to the era of cheap living many consumers remember, but rather a period of slower, more stable price growth after years of rapid increases. These are two very different outcomes.

    For decades before the pandemic, the global economy saw unusually low inflation, and consumers grew accustomed to gradual, barely noticeable price increases. The post-pandemic world upended that reality entirely. Global shipping disruptions, geopolitical conflicts, climate-related extreme weather, widespread labor shortages, and energy market volatility pushed costs higher across dozens of sectors at the same time.

    Many economists now believe the global economy is entering a structurally more inflationary era than the period that existed before 2020. If that prediction holds, consumers will need to adjust their expectations of what counts as a “normal” price level. This does not mean inflation will spin out of control, but it does mean households will likely continue facing elevated costs even when headline inflation appears statistically stable.

    Broader Social and Political Implications

    Inflation is never just an economic metric — it is a major driver of public mood and political sentiment. When workers find their salaries do not stretch far enough to cover basic needs, public frustration grows regardless of what official statistics report. This dynamic has left governments around the world struggling politically even as inflation rates have moderated from their post-pandemic peaks.

    Consumers experience prices through deeply personal, repeated encounters: the weekly grocery checkout total, the daily taxi fare, the monthly electricity bill, school lunch costs, and the quarterly rent payment. Food inflation in particular hits harder psychologically, because consumers encounter price increases at the grocery store every week, making the pressure impossible to ignore.

    In Jamaica’s context, this pressure is especially acute because wages in most sectors have not kept pace with cumulative price increases over the past five years. Even with inflation slowing, many households are still working to recover financial ground after years of eroding purchasing power.

    The real question facing Jamaican policymakers and households right now is not whether inflation is falling. Instead, the more critical question is whether incomes will rise fast enough to rebuild consumers’ purchasing power after several years of economic hardship. For most families, the only economic statistic that matters ultimately comes down to one simple, practical question: when will it be affordable to live comfortably again?

  • Rare earth reserves could be larger; Paliza says studies will conclude by the end of the year

    Rare earth reserves could be larger; Paliza says studies will conclude by the end of the year

    As global demand for critical rare earth minerals surges amid a sweeping reorganization of global supply chains, the Dominican Republic’s ongoing exploration of large rare earth deposits has emerged as a potential game-changing development for the Caribbean nation’s economy, a senior government official has confirmed.

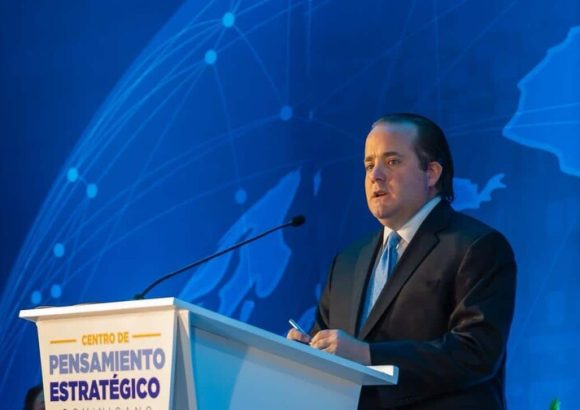
    Speaking at the inaugural International Congress of Geopolitics this week, Minister of the Presidency José Ignacio Paliza shared key updates on the exploration project, revealing that a full assessment of the quantity and grade of the country’s rare earth reserves will be completed by the end of 2024. Early estimates already point to far larger deposits than initially discussed: while President Luis Abinader previously referenced a preliminary figure of 60 million gross tons, Paliza confirmed the actual reserve could be as much as double that volume.

    The project remains in its active exploration phase as of the time of the announcement. To date, exploration teams have completed 3,527 meters of borehole drilling and 3,100 meters of small-to-medium test pit excavations, and are on track to collect 10,000 geological samples for analysis by the end of the year.

    Paliza emphasized that the rare earth development opportunity comes at a pivotal moment for global markets. Global demand for rare earth elements — critical inputs for the energy transition, artificial intelligence, national defense systems, electric vehicle batteries, and consumer electronic components — is projected to double by 2030. If the Dominican Republic can bring its reserves into commercial production, it will secure a place at the center of one of the 21st century’s most strategically important global supply chains.

    When compared to existing major mining operations in the country, the scale of potential rare earth production is staggering. As Paliza noted, even a large established operator like Barrick Gold would be considered relatively small next to the economic footprint a fully developed domestic rare earth industry could create for the nation.

    A key advantage of the Dominican Republic’s deposits, located in the Ávila Fiscal Mining Reserve in Pedernales, is their favorable geological characteristics that would allow for extraction with minimal environmental harm. Paliza pointed out that many known rare earth deposits around the world are not commercially viable because processing generates toxic waste that makes exploitation environmentally and economically unsustainable. “In our case, it seems that we have them in very healthy, very favorable conditions, to put it plainly,” he said.

    Due to the lengthy timeline and high level of technical specialization required to develop a full rare earth industry from exploration to commercial production, Paliza noted the project will likely span multiple future Dominican government administrations, requiring long-term commitment and institutional continuity.

    The rare earth potential extends beyond the Dominican Republic’s borders, Paliza added. Since the deposits are located in a mountain range that crosses into neighboring Haiti, the shared geological formation means Haiti is also likely to hold significant rare earth reserves, putting both Caribbean nations on the global strategic minerals map.

    Currently, more than 80% of global rare earth production is concentrated in China, a supply dynamic that has sparked growing concern among the United States and other Western powers that rely on a single source for these critical strategic materials. Paliza argued that nations that can develop reliable supplies of strategic minerals including lithium, cobalt, copper, and rare earth elements will hold outsized economic, technological, and military competitive advantages in the coming decades.

    To fully capitalize on this once-in-a-generation opportunity amid the ongoing reshaping of the global economy, Paliza stressed that the Dominican Republic must first upgrade its energy, logistics, and technological infrastructure. He tied the Pedernales mining potential to a broader national strategy to boost the country’s regional standing, anchored by ongoing high-impact projects including the development of the Port of Manzanillo, the expansion of utility-scale renewable energy generation, and Google’s major investments in national digital infrastructure.

    “The Dominican Republic has all the underlying conditions to become a regional hub for logistics, energy, and technology,” Paliza said. “To achieve this, we just need to consolidate institutional stability, invest in growing our human capital, and strengthen the state’s capacity to deliver on large-scale strategic projects.”

  • Inflation stands at 5.11% above the target range at the end of April

    Inflation stands at 5.11% above the target range at the end of April

    For nearly three years starting in May 2023, the Dominican Republic’s Consumer Price Index (CPI) has consistently held above the Central Bank’s official target range of 3% to 5%. In its latest monthly economic report released this week, the monetary authority confirmed that annual inflation measured from April 2025 to April 2026 reached 5.11% — a modest overshoot of the target’s upper bound, a result directly tied to broad-based instability across global commodity markets. On a monthly basis alone, the CPI rose by 0.49% in April 2026, with the bulk of this increase traced to upward price adjustments for regular gasoline, premium gasoline, and diesel. These domestic fuel price shifts follow rising crude oil costs on international exchanges, which have been amplified by ongoing geopolitical tensions in the Middle East, the Central Bank explained. The report also unpacked offsetting factors that kept monthly inflation from climbing higher than the recorded 0.49%. A modest -0.07% deflation in the Food and Non-Alcoholic Beverages group, paired with the recent appreciation of the Dominican peso against the U.S. dollar, acted as key counterweights to energy-driven price gains. The stronger local currency has pulled down prices for imported goods including automobiles, while also reducing costs for air travel and several products and services in the communications sector, the institution noted. Digging into food price trends specifically, the Central Bank highlighted that large declines were recorded for two high-consumption staples: fresh chicken and all varieties of plantain. Both goods saw dramatic price spikes in previous months after extreme weather events disrupted domestic agricultural production, so the current price pullback represents a partial correction of that earlier volatility. At the same time, a range of other food products posted notable price increases in April, including coffee, purified water, carbonated soft drinks, avocados, chili peppers, cod, oranges, cassava, limes, and tomatoes. Encouragingly, core inflation — a closely watched metric that strips out volatile, policy-insensitive price components — remained firmly within the official target range last month. Core monthly inflation clocked in at 0.43% in April, pushing the 12-month core inflation rate to 4.87%, which falls comfortably between the 3% and 5% target band. The Central Bank emphasized that core inflation provides a more reliable signal for guiding monetary policy decisions, as it excludes items whose prices are not driven by broader economic liquidity conditions. This includes highly volatile food goods, fossil fuels, price-regulated services such as electricity rates and public transportation, as well as alcohol and tobacco products. A breakdown of monthly CPI shifts by expenditure groups shows that six categories drove the overall April inflation result: Transportation, Miscellaneous Goods and Services, Restaurants and Hotels, Recreation and Culture, Housing, and Health. Three key groups — Food and Non-Alcoholic Beverages, Communications, and Clothing — actually recorded negative monthly price changes, which softened the overall inflation reading for the month. The Transportation group alone posted a 1.78% monthly inflation rate, making it far and away the largest single contributor to April’s overall CPI gain, accounting for 61.94% of the total monthly increase. As noted earlier, this surge is primarily the result of government-approved adjustments to domestic fuel prices. Additional upward pressure came from price hikes for private intercity bus fares and motorcycle taxi services, though the group’s overall increase was partially offset by seasonal price drops for air travel and new motor vehicles. When sorted by household socioeconomic status, inflation rates varied noticeably across income quintiles in April. The lowest-income group (quintile 1) recorded a 0.36% monthly inflation rate, followed by 0.40% for quintile 2, 0.47% for quintile 3, 0.52% for quintile 4, and 0.65% for the highest-income quintile (quintile 5). The Central Bank attributes the steeper inflation faced by highest-income households to two key factors: this group sees smaller benefit from falling food prices, and feels a larger impact from the price increases that drove April’s overall inflation. The report reinforces that while headline inflation has edged slightly above target due to external geopolitical and commodity market pressures, underlying inflation trends remain anchored within the central bank’s desired range, providing a stable foundation for ongoing monetary policy management.

  • Treasure this

    Treasure this

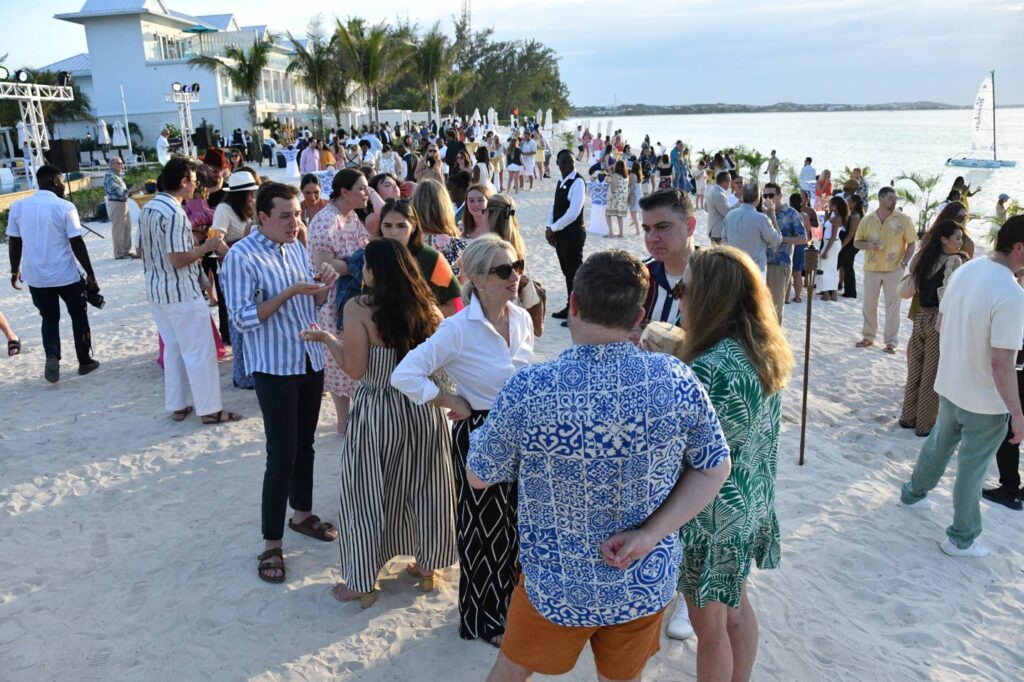
    For years, travelers have associated the name Treasure Beach with a quiet, scenic collection of fishing villages along Jamaica’s untouched southern coast. But that is no longer the only spot holding that iconic moniker, as a new luxury resort destination by the same name has officially debuted in the Turks and Caicos Islands, becoming the latest standout addition to the Beaches Turks and Caicos resort portfolio. Nestled on a stunning stretch of coastline that locals have cherished for decades under the Treasure Beach name, the new resort village caters explicitly to the fast-growing trend of multigenerational family travel, offering guests high-end oceanfront accommodations complete with private pools, private rooftop viewing decks, and sprawling family-friendly suites designed to accommodate large groups.

    The official launch celebration kicked off last Thursday with a Regatta Golden Hour welcome event, a nod to longstanding maritime traditions shared by the Turks and Caicos Islands and neighboring The Bahamas. More than 500 invited guests gathered for the weekend festivities, including top travel advisors, local and regional government leaders, tourism authority officials, A-list celebrities, and early vacation guests eager to preview the new property. Deryk Meany, general manager of both Treasure Beach Village and Beaches Turks and Caicos, delivered an energetic opening address to welcome attendees to the one-of-a-kind new destination.

    The weekend of celebration reached its climax on Saturday night with a high-energy Treasure Beach Village Bash, which featured Jamaica’s Prime Minister Dr. Andrew Holness as a special guest of honor. Adam Stewart, Executive Chairman of Sandals Resorts International, which owns the Beaches brand, hosted the official opening ceremony marking the completion of the $50-million development. The property first welcomed guests during a soft opening phase back in March 2024, and its official launch now signals the start of a major new growth push for the brand’s Beaches 2.0 initiative.

    Under Beaches 2.0, Sandals Resorts International plans to invest an estimated $1-billion to expand the Beaches footprint across the Caribbean, with new planned destinations in Exuma, The Bahamas, as well as additional sites in Jamaica, Barbados, and St. Vincent and the Grenadines. The launch of Treasure Beach Village marks the first major milestone in this ambitious regional expansion strategy, which aims to meet rising demand for luxury family-friendly vacation experiences across the Caribbean’s most coveted coastal locations. Industry insiders note that the new development and broader expansion plan signal the brand’s confidence in a continuing post-pandemic boom in Caribbean travel, particularly among multi-generational groups seeking custom, spacious accommodations.

  • ECCB Holds Regional Attorneys General and Financial Secretaries Meeting in Antigua and Barbuda

    ECCB Holds Regional Attorneys General and Financial Secretaries Meeting in Antigua and Barbuda

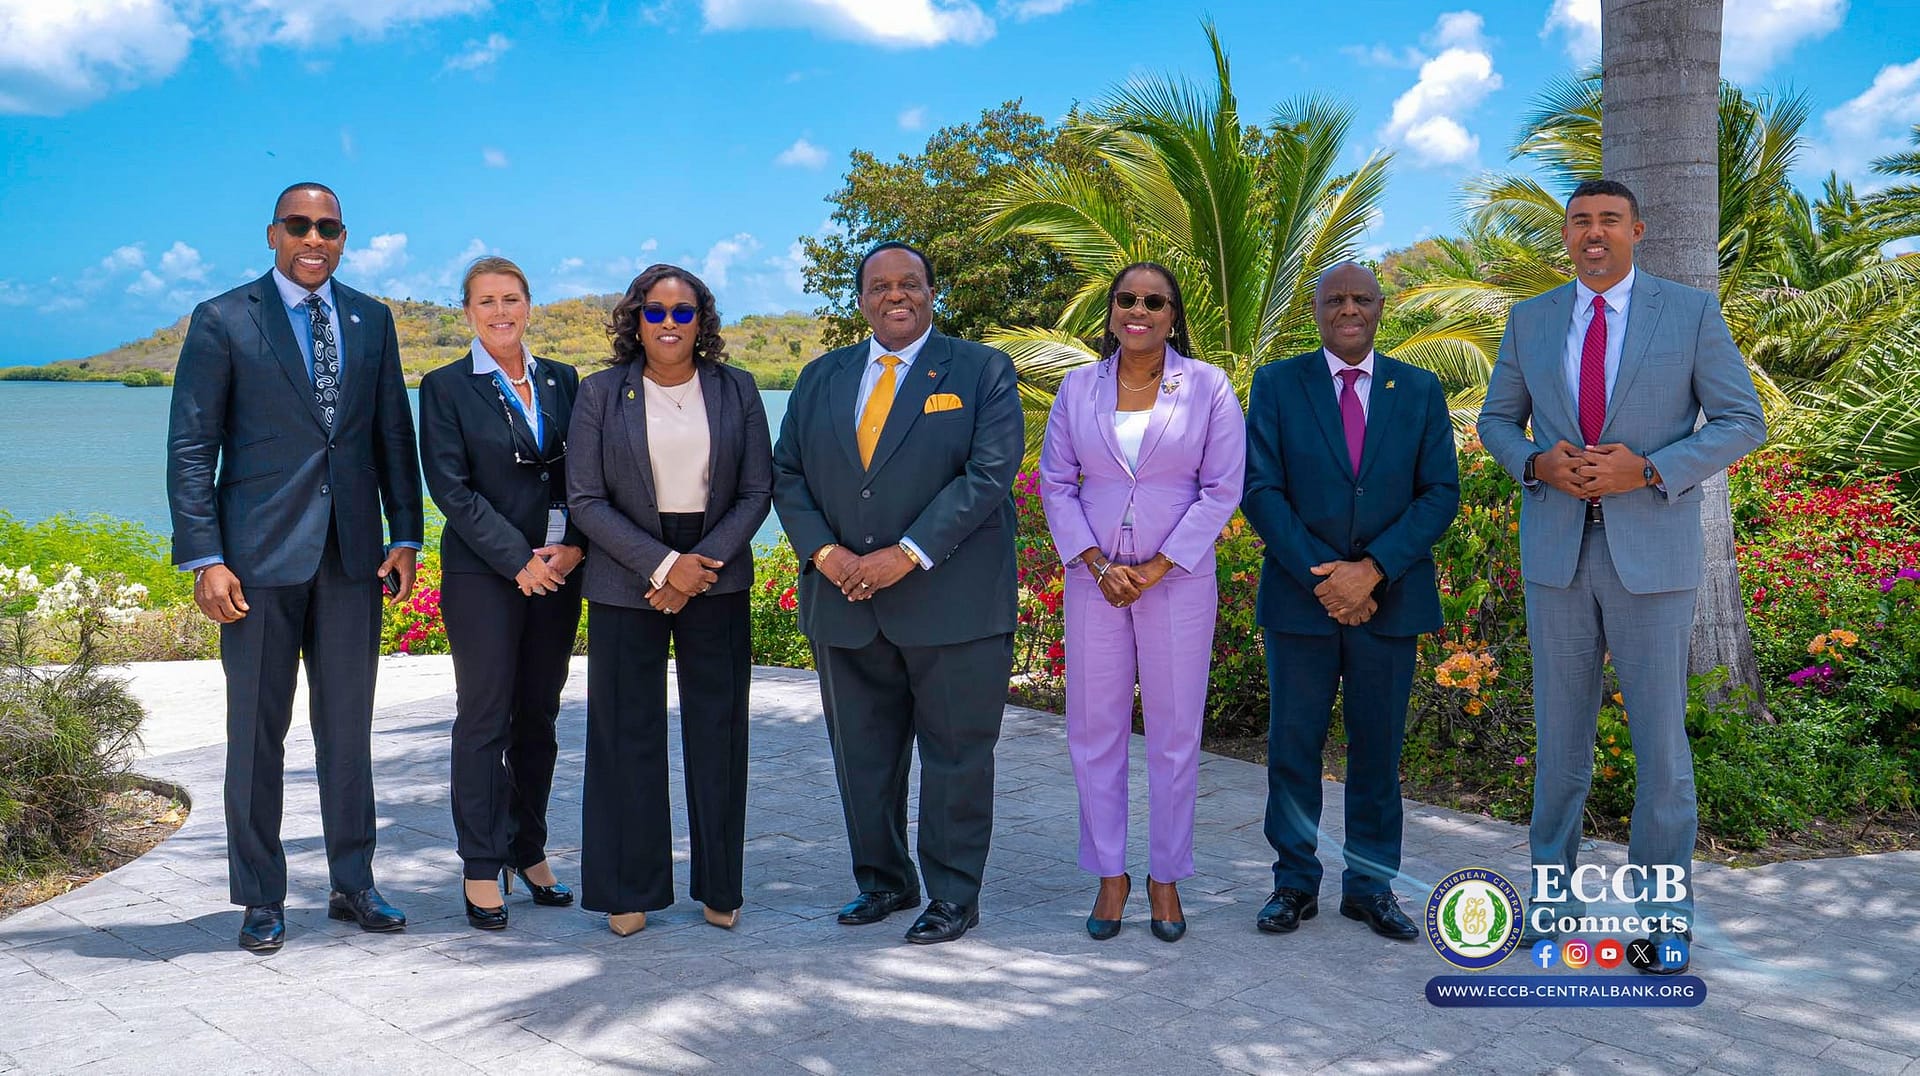
    Top legal and finance leaders from all member states of the Eastern Caribbean Currency Union (ECCU) have converged on Antigua and Barbuda this week for the eighth annual joint gathering of Attorneys General, Chief Parliamentary Counsel, and Financial Secretaries.

    Hosted by the Eastern Caribbean Central Bank (ECCB), the two-day policy conference ran from May 14 to 15, centered on advancing coordinated legislative and financial industry reforms across the entire Eastern Caribbean region. Throughout the meeting, delegates delved into a wide range of priority policy initiatives designed to reinforce financial governance and oversight across the currency union. These included draft updates to regional insurance and pension regulations, new licensing frameworks for digital and traditional payment systems, updated data protection governance standards, and enhanced cross-border crisis management protocols to mitigate systemic financial risk.

    In addition to general regional policy discussions, the meeting featured dedicated presentations on country-specific and institution-focused modernization projects. Attendees were briefed on Grenada’s upcoming Cooperative Societies Bill, which aims to update regulation of the island’s cooperative sector, as well as Saint Vincent and the Grenadines’ progress rolling out its new Single Window for Land and Property Transactions, a digital initiative designed to cut red tape and speed up real estate processing across the country. Delegates also reviewed proposed legislative changes to update the Eastern Caribbean Home Mortgage Bank (ECHMB), centered on a new draft agreement that would formalize changes to ECHMB’s capital structure to support its modernization and expansion.

    Per statements from the ECCB, this week’s gathering is a core component of the central bank’s long-term strategic agenda laid out in its 2026-2031 Strategic Plan, which identifies strengthening regional regulatory and supervisory systems as a key priority to support sustained financial stability and economic growth across the ECCU. The annual cross-sector meeting has long been one of the ECCB’s flagship collaborative events, creating a structured space for regional legal leaders and financial regulators to align on shared legislative priorities that shape the future of the Eastern Caribbean’s financial sector.

  • ABWU Officials Attend Caribbean Travel Marketplace 2026

    ABWU Officials Attend Caribbean Travel Marketplace 2026

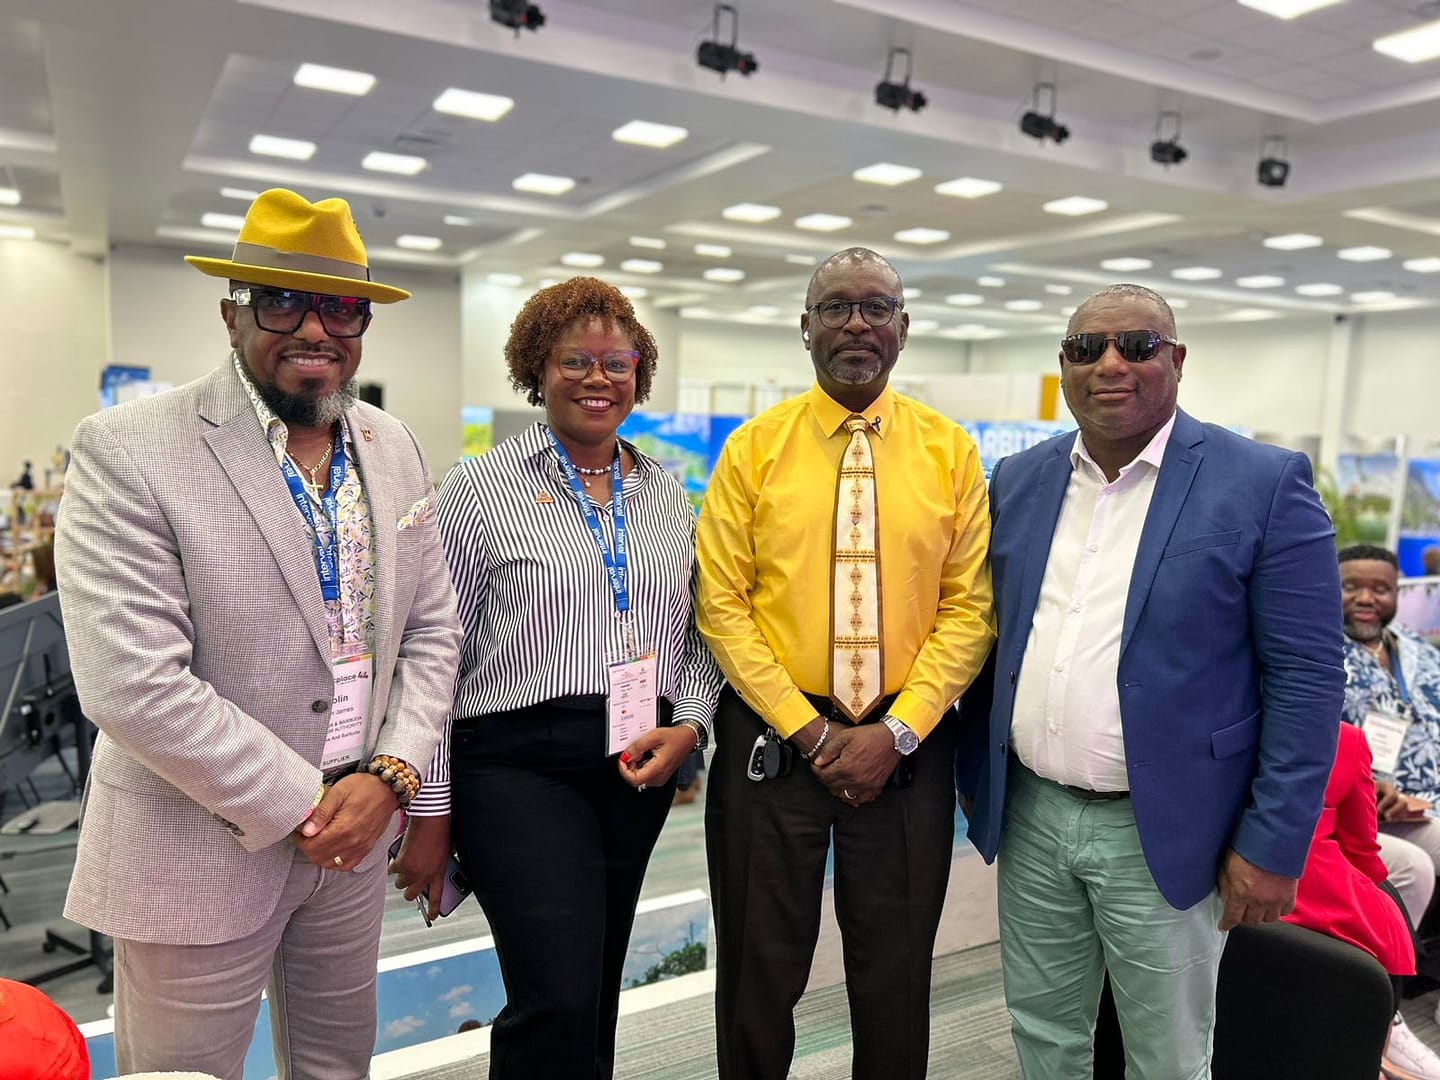
    On Thursday, top leadership from the Antigua and Barbuda Workers’ Union (ABWU) marked a notable appearance at the 2026 iteration of the Caribbean Travel Marketplace, one of the Caribbean’s most high-profile and industry-defining annual tourism gatherings. David Massiah, ABWU’s General Secretary, joined by Deputy General Senator Chester Hughes, toured the event’s proceedings and engaged with cross-sector stakeholders gathered for the landmark conference.

    Hosted to catalyze collaboration, investment, and innovation across the Caribbean’s tourism ecosystem, the 2026 Marketplace drew over 500 attendees spanning international tourism buyers, global media outlets, industry operators, and regional stakeholders from every corner of the travel and hospitality sector. The event has long cemented its reputation as the premier business gathering for tourism leaders across the Caribbean, setting the agenda for growth and development in the sector for the coming years.

    As the primary labor representative for the majority of hotel employees across Antigua and Barbuda, the ABWU used its attendance at the event to reaffirm its open stance toward initiatives that advance the quality of the nation’s tourism offerings. Critically, the union emphasized that any progress in the sector must go hand in hand with tangible improvements to working conditions and quality of life for the frontline workers that power the industry.

    Union leadership also issued formal praise for organizers and participating stakeholders who pulled off the large-scale regional gathering. In their remarks, ABWU leadership reiterated the non-negotiable role tourism plays as a foundational pillar of Antigua and Barbuda’s national economy, noting that the sector remains the single largest source of steady employment for hundreds of local workers across the two-island nation. The event’s hosting, union leaders added, represents a positive step forward for positioning Antigua and Barbuda as a top global travel destination, while also creating space to address the needs of the workforce that underpins that success.

  • 80 Years Later: HRCU Thrives on Loyalty of Longtime and New Members

    80 Years Later: HRCU Thrives on Loyalty of Longtime and New Members

    It is not every small financial cooperative that can claim eight decades of steady growth, community trust, and transformative impact on the lives of generations of members. But for Belize’s iconic Holy Redeemer Credit Union (HRCU), that milestone is not just a historical footnote—it is a living, breathing legacy celebrated this May 2026 alongside the thousands of member-owners who built the institution from its humble origins.

    The story of HRCU begins with a humble start that few could have predicted would grow into one of Belize’s most enduring member-owned financial institutions. Eighty-two years ago, Catholic Father Suti worked for months to lay the groundwork for the credit union before three local women—June Bolton, Carmen Canton, and Hazel Anderson—stepped forward to launch the initiative. Together, they opened the cooperative with just 75 cents in starting capital, laying the first brick of what would become a cornerstone of Belizean community finance.

    Eight decades on, that tiny founding group has swelled to more than 65,000 active member-owners, spanning generations of Belizeans who turn to HRCU for everything from their first childhood savings accounts to mortgages for family homes and startup capital for local business ventures. For long-time members like Corine Robinson-Fuller, who joined the credit union back in 1980, the loyalty that keeps HRCU at the center of so many Belizeans’ financial lives comes down to one simple factor: consistent, member-first service. “I stayed because the service to me as a member is phenomenal,” Robinson-Fuller explained in an interview at HRCU’s Belize City headquarters. She pointed to the annual dividend payouts that reward member ownership, and the accessible lending that allowed her to build a home for her mother as just two examples of the cooperative’s outsized positive impact. “Getting a loan here was easy for me, when I built my mom’s house… that was a very good experience.”

    To mark 82 years of service and thank the member-owners that drive its mission, HRCU decked out all three of its nationwide branches in celebratory decorations, distributed complimentary goodies to visitors, and held grocery basket raffles as a small gesture of appreciation for the community. Frontline staff spent the day greeting members, echoing the cooperative’s core philosophy that members are the heart of the institution. “After all, the member owners are our bosses and they are the ones that have us here. So, without them we would not have been here eighty-two years later,” explained Nigel Alvarado, HRCU’s Compliance Officer. Alejandra Velasquez, a Finance Officer at the credit union, added that working for an institution trusted by generations of members is a point of deep professional pride. “I feel really good. I feel really honored because I know we have done a great job serving them. And like they say, the customer service is always on point, so I am happy to hear that.”

    Mark Menzies, HRCU’s Human Resource Manager, emphasized that the cooperative’s headquarters is far more than a branch with teller lines and deposit counters—it is a space where personal financial goals become reality, and lives are changed for the better. “We have a lot of stalwarts who love this credit union and so we at the helm have to do everything right and take care of our member owners,” Menzies said. “They are very important to us.”

    For many members, the cooperative’s democratic structure keeps that focus on member needs front and center. As Robinson-Fuller noted, “At every AGM you will be reminded that you are an owner. And when you see the progress made you realize that you are a part of it.” Looking ahead, HRCU has scheduled its 2026 Annual General Meeting for May 30 to continue that transparent, member-led tradition. Reporting for Belize’s News Five from HRCU’s Belize City headquarters, Paul Lopez delivered this on-the-ground account of the 82nd anniversary celebration.