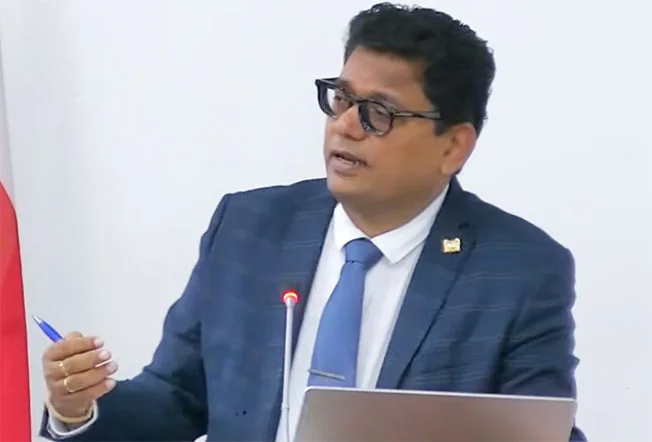
On November 7, senior legislator and co-initiator of the Tax Justice Act Asis Gajadien laid out sweeping reform proposals during a parliamentary session in De Nationale Assemblee, designed to streamline tax dispute resolution and strengthen legal safeguards for both individual citizens and business owners in Suriname. At the core of the proposed changes is a plan to slash the mandatory waiting period for taxpayers to appeal an unresolved tax objection from 12 months down to just six. Under current rules, residents and enterprises that submit formal objections to the tax service over disputed assessments or penalties are forced to wait a full year before they can escalate their case to a judicial review, even if the tax agency fails to issue a formal ruling on their appeal. Gajadien emphasized that a truly modern, fair tax system cannot function if taxpayers lack accessible, independent avenues to challenge decisions made by the national tax authority. While the state holds the legitimate power to levy and collect public taxes, he noted, that authority must be balanced with robust protections against erroneous, unfair, or unlawful administrative actions that can derail livelihoods or business operations. The proposed six-month ruling deadline will be aligned with the General Tax Act to eliminate conflicting provisions across existing financial legislation, Gajadien confirmed. He acknowledged that the tighter timeline will place higher operational demands on the national tax service, warning that understaffing or rushed case processing could lead to a surge in new appeals filed over the agency’s failure to meet the new six-month deadline, if the body is not given adequate resources to adjust. The reform package also introduces a critical new provision for urgent judicial relief: taxpayers facing drastic, high-stakes tax enforcement actions, such as asset seizures that would freeze a company’s operational resources and put its entire ability to run at risk, will be able to file an emergency petition for immediate judicial intervention before a specialized tax judge. Gajadien pointed out that under current rules, a business can be forced to cease operations entirely due to a seizure order, even before a court has confirmed whether the underlying tax assessment that triggered the enforcement action was legally valid. The new provision would allow judges to step in quickly to prevent irreversible, hard-to-remediate harm to businesses or individual livelihoods. Crucially, the proposed rules do not automatically pause enforcement actions when a taxpayer files an appeal. Instead, judges will be granted explicit authority to conduct a balanced assessment of competing public and private interests on a case-by-case basis to decide whether a temporary suspension of enforcement is warranted. Gajadien also defended the provision that removes any mandatory requirement for taxpayers to hire a licensed lawyer to file a tax appeal, noting that legal service costs in Suriname are prohibitively high for large segments of the population. Access to tax justice, he argued, must never be restricted based on a person’s or small business’s financial means. The draft law sets nominal court filing fees of SRD 250 for individual citizens and SRD 1,500 for corporate entities, but Gajadien warned that even these relatively low fees can create unnecessary barriers for people contesting multiple linked tax decisions, such as a disputed assessment and an accompanying penalty. He has proposed a carve-out to ensure taxpayers are not forced to pay duplicate filing fees for connected, related tax cases that stem from the same original dispute. Placing the legal reform in a broader national economic context, Gajadien added that the tax overhaul is part of a wider push to review Suriname’s overall tax burden on businesses, noting that the current combined corporate tax rate of 36%, paired with value-added tax, import duties, and dividend levies, creates a heavy load that can deter new investment and job creation. While the new tax justice framework will not resolve broader structural economic challenges on its own, he explained, it will deliver far greater legal certainty for ordinary residents and entrepreneurs, laying a more stable foundation for sustainable economic growth.