分类: business

  • Vacancy: Operations Manager – Zirachi Group Airbnb properties

    Vacancy: Operations Manager – Zirachi Group Airbnb properties

    As the short-term vacation rental market continues to grow across the Caribbean, Grenada-based Zirachi Group has opened a new full-time position for an experienced Operations Manager to lead the daily oversight and strategic management of its expanding portfolio of Airbnb and other short-term rental properties.

    The successful candidate will take ownership of every core operational function across the property network. Primary duties include end-to-end management of day-to-day property activities, seamless coordination of guest arrival and departure processes, and maintaining consistent, clear communication with guests throughout their stay. The role also requires supervising all housekeeping workflows, scheduling proactive and reactive property maintenance, and conducting routine property inspections to uphold brand standards. A key performance target for the position will be maintaining the highest possible benchmarks for cleanliness, property presentation, and overall guest satisfaction to drive positive reviews and repeat bookings.

    Additional responsibilities include managing all listings across major booking platforms, implementing data-driven strategies to optimize occupancy rates and maximize revenue, addressing guest inquiries in a timely fashion, resolving any on-site or pre-arrival issues, and mediating feedback from customer reviews. The Operations Manager will also be tasked with liaising closely with third-party vendors, contractors, and local service providers to ensure all outsourced work is completed on time and to specification, as well as compiling regular operational reports and tracking key performance metrics to assess individual property and overall portfolio performance.

    To be considered for the role, candidates must demonstrate prior hands-on experience in one of the following sectors: hospitality management, residential or vacation property management, or the short-term rental industry. Required soft skills include strong leadership capabilities to coordinate cross-functional work, exceptional organizational skills to manage multiple properties simultaneously, and top-tier communication and customer service abilities to engage with both guests and external partners. While not mandatory, prior experience working directly with Airbnb and other major short-term booking platforms is considered a significant advantage. Candidates must also be comfortable working independently, managing competing priorities in a fast-paced environment, and have working proficiency with Microsoft Office and standard basic reporting tools.

    Ziraachi Group highlights several key benefits for the successful applicant, including clear pathways for professional career growth within a dynamic organization that is actively expanding its footprint in Grenada’s tourism and short-term rental sector, as well as a supportive, collaborative, and professional work culture. The position is based on-location in Grenada, and all candidates must be able to work locally in the country.

    Applicants interested in joining the team and helping the company deliver standout, memorable guest experiences to visitors to Grenada are invited to submit a updated professional resume and a tailored cover letter to the company’s dedicated recruitment email at [email protected].

    This recruitment posting is provided by contributor Zirachi Group, per the statement of local publication NOW Grenada, which does not take responsibility for the content, opinions, or statements included in contributor-provided content. Users can report abusive content through the publication’s official reporting channel.

  • IMF: Mondiale economie vertraagt naar 3 procent groei

    IMF: Mondiale economie vertraagt naar 3 procent groei

    The International Monetary Fund (IMF) has downgraded its 2026 global economic growth forecast for the second time in 2026, as persistent volatility from the energy crisis sparked by escalating conflict between the United States, Iran and regional allies continues to weigh on global economic activity. The latest projection puts 2026 global gross domestic product growth at 3%, a 0.1 percentage point downward revision from the IMF’s April forecast.

    This mild slowdown in aggregate global growth is partially buffered by a surging investment boom centered on artificial intelligence, which is driving new consumer and enterprise demand and accelerating cross-sector innovation, according to the IMF’s latest World Economic Outlook update. The fund projects global growth will rebound to 3.4% in 2027, a figure that remains just slightly below the 3.5% average growth rate recorded across 2024 and 2025.

    The most acute economic shock from the recent conflict escalation has landed on global energy markets. The Strait of Hormuz, a strategic chokepoint that typically handles daily transits of roughly 130 oil tankers before the latest conflict outbreak, has seen shipping volumes drop sharply to just 41 transits per day, due to ongoing risks of attacks targeting commercial vessels by Iranian forces.

    Tensions escalated further this week after the U.S. resumed airstrikes on Iranian targets, following attacks on three commercial ships transiting the Strait of Hormuz. This resumption of direct military action has amplified policy and market uncertainty across global financial and commodity markets. On Wednesday, U.S. President Donald Trump stated that the ceasefire between the U.S. and Iran is “over”, just hours before the Pentagon conducted its second consecutive day of airstrikes on Iranian targets.

    These developments have triggered a sharp jump in global crude oil prices: benchmark Brent crude briefly climbed above $79 per barrel, marking an approximately 7% price increase from pre-escalation levels.

    Higher energy prices are already filtering through to push up global inflation, the IMF confirmed. The fund now projects average global inflation will reach 4.7% in 2026, up from 4.1% recorded in 2025, before easing back to 3.9% in 2027.
    Petya Koeva Brooks, head of the IMF’s research department, noted that the global economy is currently being pulled in two opposing directions: by the lingering drag of the energy crisis triggered by Middle East conflict, and by the growth tailwind from a technology-driven investment surge. She emphasized that the current geopolitical environment carries unusually high levels of uncertainty and downside risk for global economic outcomes.
    The IMF’s baseline projections are built on the assumption that the Strait of Hormuz will reopen to full commercial shipping traffic by mid-July, with conditions returning to pre-conflict levels by March 2027. However, the fund stressed that this optimistic baseline remains highly contingent on future political and military developments in the region, with significant room for worse outcomes if conflict expands.
    Looking at regional growth breakdowns, the United States is projected to lead all major advanced economies in 2026 growth, with an expected GDP expansion of 2.3%. By comparison, the Eurozone is forecast to grow by 0.9%, the United Kingdom by 1%, Canada by 1.1%, and Japan by 0.6%. China, the world’s largest emerging market economy, is expected to post robust 4.6% growth in 2026 even amid mounting global geopolitical tensions.

  • COMMENTARY: The Citizenship Crossroads

    COMMENTARY: The Citizenship Crossroads

    In late June 2026, a formal request from the European Commission landed on the desks of five Eastern Caribbean governments: Antigua and Barbuda, Dominica, Grenica, St Kitts and Nevis, and St Lucia. The demand was clear: phase out their long-running Citizenship by Investment (CBI) programs by June 1, 2028. Backed by the EU’s revised visa-suspension framework, continued operation of these schemes now qualifies as grounds for reviewing the island nations’ visa-free access to the Schengen Area, making the 2028 deadline non-negotiable. For these small, trade-reliant open economies, the stakes could not be higher.

    While initial framing has painted this as a David-and-Goliath standoff between a powerful European bloc and vulnerable small island states, this narrative overlooks a far more nuanced reality. Both sides hold legitimate, mutually aligned interests in resolving the impasse, and a collaborative negotiated transition remains the most promising path forward.

    ### Why CBI is a Cornerstone of Eastern Caribbean Development
    For the Eastern Caribbean, CBI is far more than a marginal policy or the simple passport-selling scheme it is often caricatured as. It is a foundational pillar of public finance for nations that lack large domestic tax bases, extensive natural resources, and face repeated, intensifying climate shocks.

    St Kitts and Nevis hosts the world’s longest-running CBI program, launched in 1984. Across the five states, CBI contributes between 15% of government revenue (St Lucia) and more than 50% (Dominica and St Kitts and Nevis). In the 2022–2023 fiscal year alone, Dominica drew 37% of its total GDP from CBI revenue, equal to roughly $232 million. These funds have delivered tangible, transformative development across the region: new hospitals and clinics, upgraded road and bridge infrastructure, climate-resilient housing post-hurricane, expanded tourism infrastructure, and Dominica’s new international airport. For St Kitts and Nevis, consistent CBI revenue delivered years of budget surpluses that cut public debt below regional targets. For these small states, CBI has been an engine of both development and climate resilience, a reality any productive negotiation must acknowledge upfront.

    Even so, overreliance on a single externally driven revenue stream carries growing, already visible risks. When global scrutiny tightened and investor demand softened in 2024, St Kitts and Nevis saw CBI revenue plummet, pushing its fiscal deficit to 11% of GDP. Prudent long-term planning has long required these states to diversify away from CBI, a reality regional leaders have increasingly acknowledged.

    ### The EU’s Legitimate Security Concerns
    The European Union’s position is not arbitrary or unfair; it stems from concrete regulatory and security concerns that deserve a fair hearing. Visa-free Schengen access is a valuable shared asset that underpins much of the value of Eastern Caribbean CBI passports, and the EU bears a responsibility to protect the integrity of its visa system.

    Brussels’ concerns are specific: across the five programs, roughly 107,000 passports have been issued to date, with high application volumes and low rejection rates that raise questions about the rigor of due diligence checks. The Financial Action Task Force has repeatedly warned that poorly regulated CBI schemes can be exploited for identity fraud and money laundering. A 2025 ruling by the European Court of Justice further cemented the EU’s legal position, finding that Malta’s similar CBI program violated EU law. While the 2028 timeline remains open to negotiation, the underlying concerns held by EU regulators are reasonable and made in good faith.

    ### Shared Interests That Outweigh Public Rhetoric
    The simplistic Brussels-versus-Caribbean framing obscures a critical truth: on core governance issues, the two sides are far more aligned than headlines suggest. Rigorous due diligence is not merely a European demand—it is directly in the Eastern Caribbean’s own self-interest. Weak vetting and opaque ownership structures that trouble Brussels also erode confidence among international correspondent banks, and lost correspondent banking access is an existential threat the region has already faced. A CBI program held to the highest global standards is not a concession to Europe; it is a defense of the Caribbean’s own financial stability.

    The real disagreement is narrow: it is not whether CBI programs should be well-run—both sides agree they should. It is about the pace of phase-out and how to replace the lost revenue. These are issues for negotiation, not confrontation.

    ### The Region Has Already Taken Unilateral Action to Strengthen Regulation
    The Eastern Caribbean has already made significant progress toward addressing EU concerns, a fact often overlooked in public discourse. In September 2025, after two years of negotiations with the EU, United States, and United Kingdom, the five states signed a 92-article agreement establishing the Eastern Caribbean Citizenship by Investment Regulatory Authority (ECCIRA). Headquartered in Grenada (selected for its strong compliance track record) with national offices in each member state, ECCIRA will become fully operational in 2026.

    ECCIRA is no symbolic gesture: it enforces binding, uniform standards across all five programs, including mandatory due diligence, applicant interviews, biometric data collection, genuine residency requirements, shorter passport validity terms, uniform investment minimums, and a centralized shared registry of rejected applicants, agents, and developers. It also has the power to compel audits, impose sanctions, and revoke operating licenses. In short, the Eastern Caribbean has already proactively built most of the regulatory architecture Brussels has demanded. This progress demonstrates that the region is a willing partner that deserves to be met halfway.

    Even so, ECCIRA is a starting point, not a final solution. The authority was designed solely to make existing CBI programs compliant with European and North American standards—but the EU’s June 2026 letter makes clear that even perfectly run programs must be phased out. The EU’s objection is now one of principle, not just regulation. ECCIRA’s greatest achievement is not saving CBI, but proving that the five Eastern Caribbean states can collaborate effectively on critical regional issues, ceding limited sovereignty to a shared regulator for the collective good. This capacity for collective action is the region’s most durable asset, far more valuable than any single revenue stream.

    ### What a Constructive Path Forward Looks Like
    A successful outcome requires two core priorities: first, a managed transition, not an abrupt fiscal cliff. A firm 2028 deadline does not require an immediate hard stop. A phased, negotiated redesign that shifts toward longer-term residency-based investment models aligned with EU security demands, while maintaining an orderly flow of investment during the transition, benefits both sides. The EU protects its visa regime integrity, while the region gains time to adjust its fiscal and economic models.

    Second, and most critically, the region needs support to replace lost CBI revenue. The Caribbean has already laid out an ambitious growth agenda for the next decade: the Eastern Caribbean Central Bank’s (ECCB) “Big Push” strategy targets doubling the regional currency union’s economy by 2031, requiring 7% annual growth, while the Caribbean Development Bank (CDB) labels the 2020s a “decade of decision” requiring $65 billion in financing by 2033 to avoid economic stagnation. Abruptly losing CBI revenue—which contributes 5% of the currency union’s total GDP, and 37% of Dominica’s GDP—would derail these plans, eliminating the core capital source for critical infrastructure that underpins long-term growth.

    Regional leaders have already outlined the core of a path forward: CBI revenue generated during the transition can be reinvested to seed economic diversification across priority sectors, including renewable energy, food security, medical tourism, the creative economy, and special economic zones. The existing framework for diversification already includes clear, actionable priorities:
    – Publish annual Diversification Indexes alongside national budgets, tracking shifts in GDP, employment, and revenue across core sectors with five-year targets
    – Establish a regional Regional Medical Excellence Fund, funded by a share of CBI revenue, to build one accredited specialty medical center per state to grow high-margin, climate-resilient medical tourism
    – Require states with high CBI dependence to publish formal fiscal transition plans outlining how revenue losses will be absorbed without unsustainable new debt
    – Negotiate a regional energy partnership with Guyana to replace costly imported fuel oil, the largest structural cost for most Eastern Caribbean economies
    – Launch a regional agricultural credit guarantee facility in partnership with the ECCB and CDB to lower borrowing costs for smallholder farmers
    – Extend the ECCIRA collaborative regulatory model to other sectors including healthcare accreditation, agricultural standards, and digital asset regulation

    ### A Unified Regional Negotiating Strategy Is Key
    To advance these goals, Eastern Caribbean governments should convene a permanent standing panel under the Organization of Eastern Caribbean States (OECS), drawing representatives from ECCIRA, the ECCB, the CDB, and regional trade negotiators. This panel will carry a unified regional position into direct diplomatic talks with the EU and United States, with a mandate to secure a binding, mutually beneficial agreement.

    Negotiations should proceed on two tracks. First, test at the highest level whether a CBI regime rebuilt to ECCIRA’s strict standards can address the EU’s security concerns. Second, and more importantly, plan for a phase-out by framing the transition as a reciprocal negotiation, not a request for charity. If the EU gains its goal of eliminating CBI to protect Schengen integrity, the region should gain expanded, guaranteed market access for its exports under existing frameworks including the CARIFORUM-EU Economic Partnership Agreement and U.S. Caribbean Basin trade preferences.

    Agriculture is the logical starting point for this agreement: Europe can provide long-term guaranteed access for Caribbean agricultural and value-added produce, while the region commits to building the infrastructure—packing facilities, cold chains, port capacity, phytosanitary certification—needed to meet export demand. This shifts revenue from passport fees to earnings from goods and services, creating a more sustainable, dignified foundation for long-term growth that benefits both sides.

    ### A Moment for Regional Unity
    This challenge also offers an unexpected opportunity. For decades, Eastern Caribbean states have competed against one another for CBI investment, fragmenting their negotiating power. ECCIRA has already proven that collective action delivers stronger results. The 2028 deadline is the strongest argument for regional integration the Caribbean has seen in a generation. No single small island can negotiate favorable terms with Brussels or Washington, but a unified Eastern Caribbean has leverage, shared interests, and a legitimate claim to reciprocal partnership.

    This is not a contest between a powerful Europe and a vulnerable Caribbean. It is a shared governance challenge between partners who both want a clean, secure CBI regime and a prosperous Eastern Caribbean. The EU’s commitment to regulatory integrity is legitimate, and the region’s need for time to replace lost revenue is equally legitimate. The 2028 deadline is real, but so is the opportunity to build a more diversified, sustainable regional economy. The Caribbean has navigated far greater challenges, and it will succeed if it negotiates as one, in good faith with its partners, to build a transition that works for everyone.
  • T&T secures US$800m bond issue

    T&T secures US$800m bond issue

    Trinidad and Tobago has closed a landmark $800 million sovereign bond issuance on the United States capital market, marking one of the most successful debt offerings in the country’s recent history, the Ministry of Finance announced in an official statement this week. The offering saw a roughly 400% oversubscription – the highest level of investor demand the Caribbean nation has recorded since it launched its first benchmark-sized sovereign bond back in 2013.

    The new 10-year notes were priced at a 6.20% coupon, and achieved a rare negative new issue concession, an outcome the ministry described as exceptional. A negative new issue concession means investors did not demand any extra cost incentive to commit capital to the transaction, a result that directly reflects the overwhelming strength of investor appetite and widespread market confidence in Trinidad and Tobago’s sovereign credit standing.

    According to the ministry’s statement, the successful offering repriced the country’s entire sovereign yield curve, a shift that grew out of a two-day investor roadshow hosted by a high-level Trinidadian government delegation. The roadshow was led by Finance Minister Davnedranath Tancoo, Energy Minister Dr Roodal Moonilal, and Central Bank Governor Larry Howai, who walked international investors through the country’s current economic trajectory and policy agenda.

    The transaction drew participation from more than 150 high-quality institutional investors across the globe, with allocations spread across the United States, United Kingdom, continental Europe, the Caribbean, and significant participation from local institutional investors based in Trinidad and Tobago. This broad uptake has not only deepened the country’s existing international investor base but also boosted secondary market liquidity and reinforced broader confidence in Trinidad and Tobago’s credit profile, the ministry added.

    The strong outcome of the offering did not come about by chance: it was underpinned by a year-long, sustained investor engagement strategy executed by the Trinidadian government. In a push to maintain consistent, transparent dialogue with the global investment community, the Ministry of Finance hosted the country’s first ever non-deal roadshow in Washington, DC, back in April 2026. That event gave policymakers the chance to update international investors on the country’s recent fiscal performance, progress in both the energy and non-energy economic sectors, and the government’s ongoing policy reform initiatives.

    Speaking on the milestone, Tancoo emphasized that the overwhelming investor demand is a clear signal that the international community has restored its confidence in Trinidad and Tobago, a shift he attributes directly to the current government’s policy direction. He noted that the administration has prioritized two core economic goals: expanding the non-energy sector to diversify the national economy, while also modernizing and growing the country’s traditional energy sector. This dual strategy has built a more credible, balanced economic outlook that has resonated with global investors, he explained.

    To put the result in perspective, Tancoo compared the 2026 offering to the country’s last similar issuance, a $800 million 10-year bond brought to market by the previous administration in 2024. That earlier offering carried a 6.4% coupon, 20 basis points higher than the current issuance, despite taking place in a less volatile global financial environment. “Today, Trinidad and Tobago has attracted stronger investor interest at a lower coupon interest rate, on more favourable terms, for a longer period and in a more volatile economic and financial environment,” Tancoo said. “This is a clear indication of global confidence in the policy direction and future prospects of Trinidad and Tobago.”

  • Liberty Business unveiled in St Kitts and Nevis – enabling digital transformation across key sectors and supporting enterprise customers

    Liberty Business unveiled in St Kitts and Nevis – enabling digital transformation across key sectors and supporting enterprise customers

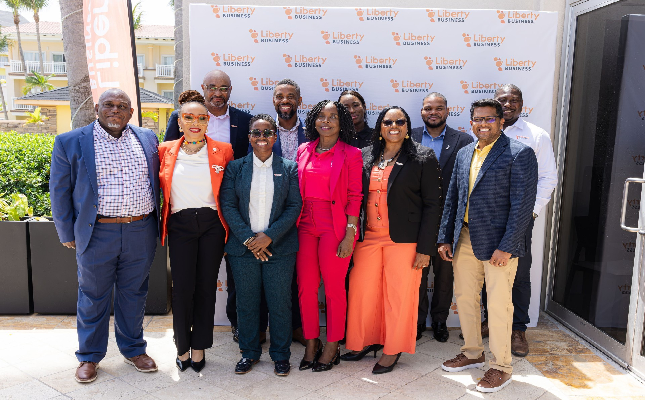
    BASSETERRE, St. Kitts and Nevis – July 10, 2026 – A new era of enterprise digital support has launched in the Federation of St. Kitts and Nevis, as former regional telecommunications provider C&W Business has officially rebranded to Liberty Business. The rebranding milestone, announced at a special stakeholder event attended by senior government officials, industry leaders, key partners, enterprise clients and local media, celebrates the next chapter of an organization that has served the Caribbean nation for generations.

    This shift is far more than a superficial name change, company leaders emphasized during the launch. It represents a full strategic evolution that positions the brand as a trusted digital advisor and strategic technology partner, focused on enabling sustainable, long-term growth for businesses operating in an increasingly interconnected global digital economy. Liberty Business operates under Liberty Caribbean, a regional subsidiary of Liberty Latin America that also manages well-known consumer brands Flow and BTC across more than 20 Caribbean markets.

    Susanna O’Sullivan, Vice President of North Caribbean for Liberty Caribbean, noted that the launch of Liberty Business builds on a 100-plus-year legacy of connectivity and development support originally established by Cable & Wireless Communications in St. Kitts and Nevis. For more than a century, the organization has played a central role in linking people, businesses and local communities, while driving both economic expansion and social progress across the Federation.

    That legacy has accelerated dramatically since the organization joined Liberty Latin America in 2016, a transition that has unlocked billions in regional investment for network modernization, expanded digital infrastructure, and deployment of next-generation connectivity across the Caribbean. Today, Liberty Caribbean manages one of the region’s most extensive communications networks, anchored by approximately 50,000 kilometers of combined subsea and terrestrial fiber optic infrastructure that connects more than 30 regional markets. This extensive footprint delivers resilient, secure, high-performance connectivity to businesses and communities across the Caribbean.

    O’Sullivan explained that for modern enterprises in St. Kitts and Nevis, connectivity has evolved beyond basic access to the internet. It is now a foundational business asset that enables higher productivity, protects critical corporate data, supports distributed hybrid work models, enables seamless adoption of cloud technologies, and builds the operational resilience required to compete in the modern digital economy.

    Lorraine Mitchell, Country Manager for Flow St. Kitts and Nevis, added that the Liberty Business rebrand reflects the organization’s ongoing commitment to helping local organizations navigate digital transformation with confidence, by delivering technology solutions tailored to the unique operating needs of Caribbean businesses.

    “Today’s enterprises need far more than just an internet connection,” Mitchell said. “They require a partner that understands their growth ambitions, helps them mitigate evolving cyber and operational risks, and delivers technology solutions that drive tangible, meaningful business outcomes.” The organization serves a broad cross-section of sectors across St. Kitts and Nevis, including government, tourism, financial services, education, healthcare, and small and medium-sized enterprises. Its core goal is to provide the technical expertise, digital infrastructure, and innovative solutions that help organizations grow, streamline operations, and maintain resilience in an increasingly competitive global market.

    Under the unified Liberty Business brand, the organization has consolidated a full integrated portfolio of enterprise-focused solutions, including advanced high-speed connectivity, industry-leading cybersecurity, cloud services, data center infrastructure, managed IT services, enterprise mobility, and unified communications tools. This consolidated offering is designed to meet the rapidly evolving needs of modern business and government customers across the region.

    Shelton Flash, Director of B2B for North Caribbean at Liberty Caribbean, highlighted that the launch of Liberty Business underscores the company’s strong confidence in the long-term economic future of St. Kitts and Nevis, and its commitment to serving as a long-term strategic partner for the country’s digital development.

    “As local businesses continue to adopt new transformative technologies, Liberty Business will be there to listen to client needs, provide strategic guidance, build resilient infrastructure, protect critical assets, and connect organizations to global markets,” Flash said. “Together with our customers and regional partners, we look forward to helping build a smarter, stronger, and more connected future for the entire Federation.”

    As a regional leading communications and technology provider operating under Liberty Latin America, Liberty Caribbean serves more than 20 markets across the Caribbean, delivering broadband, mobile, video and voice services to residential consumers through its Flow and BTC brands. Through its B2B division Liberty Business, the company delivers enterprise-grade connectivity, cloud infrastructure, cybersecurity, and data center solutions to businesses and government entities, supporting broad-based economic growth in an increasingly digital world. With a regional legacy spanning more than 150 years, Liberty Caribbean remains deeply rooted in local communities across the region, delivering robust network infrastructure, personalized local support, and customized solutions that align with the unique needs of the populations it serves.

  • Cost Pro Supermarket Closes Permanently, Employees Laid Off

    Cost Pro Supermarket Closes Permanently, Employees Laid Off

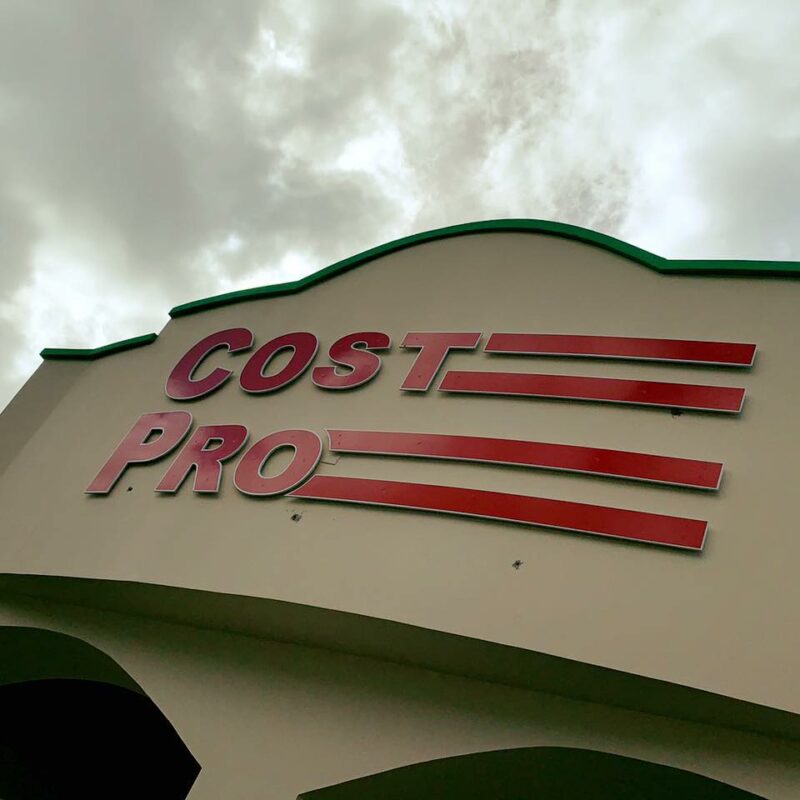
    In a sudden development impacting the local retail sector of Antigua and Barbuda, Cost Pro Supermarket, an established grocery outlet located at Woods Mall in St. John’s, has permanently ceased all operations. The full staff complement of the supermarket has been terminated on redundancy grounds, ending their ties to the business immediately.

    A formal notification letter dated July 9 from the chain’s management confirmed the permanent closure of the location, noting that all existing positions at the supermarket had been eliminated, leading to the immediate end of every employee’s term of service. In line with the country’s labor regulatory requirements, the company has outlined clear next steps for compensating affected workers.

    According to the announcement, all employees will receive full compensation for hours worked up to their final day of employment. Company officials are currently conducting a comprehensive review of payroll records to calculate all additional owed payments, which include accumulated unused vacation pay, statutory notice pay for eligible workers, and severance packages mandated by Antigua and Barbuda’s labor laws.

    Management has committed to distributing itemized final payment statements to every affected worker no later than July 17. These documents will detail all outstanding amounts owed to employees, after all required statutory deductions have been applied. In a corresponding requirement, workers have been directed to return all company-owned assets in their possession by the same July 17 deadline. This includes work uniforms, facility keys, employee identification cards, work-related equipment and all company documents.

    In a closing statement, Cost Pro Supermarket’s management expressed gratitude to all former employees for their years of service to the company and extended well wishes for their upcoming job searches and future career paths. The shutdown brings a definitive end to the supermarket’s years-long tenure as a retail tenant at the Woods Mall location.

  • Economy : Bank credit to the private sector shows a slight increase of 0.3% after 2 years of contraction

    Economy : Bank credit to the private sector shows a slight increase of 0.3% after 2 years of contraction

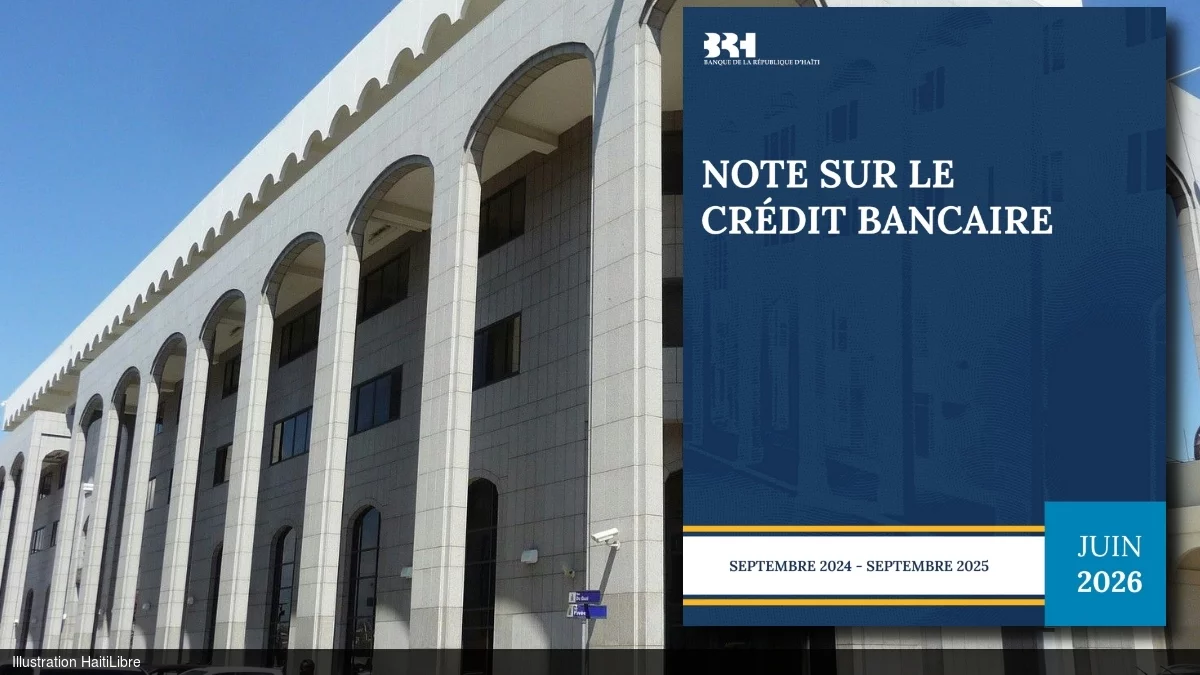
    After two consecutive years of sharp decline, Haiti’s bank lending to the private sector has finally edged into positive territory, new data from the Bank of the Republic of Haiti (BRH) confirms. The central bank’s latest annual report, which tracks credit trends between September 2024 and September 2025, shows a modest 0.3% expansion in the country’s net loan portfolio, ending a downturn that saw credit contract by 15.2% in 2024 and 9.6% in 2023. This fragile growth unfolds against a backdrop of deep systemic challenges that have kept Haitian financial institutions deeply cautious about extending new capital.

    Over the 12-month analysis period, Haiti’s commercial banks maintained a risk-averse lending posture amid ongoing deterioration of the national business climate and a five-year-long worsening security crisis that has disrupted nearly all segments of economic activity. The report documents that the average rate of non-performing loans (NPLs) across the sector climbed to 13% during the period, up from 10.36% in the 2023-2024 fiscal year, a jump that has further incentivized conservative lending strategies.

    Beyond overall growth trends, the BRH analysis highlights significant structural inequalities in Haiti’s credit market. Lending remains heavily concentrated in a small set of sectors and geographic regions, with persistent gender-based gaps in access to financing for small business owners and entrepreneurs. To mitigate ongoing strain on the market, the central bank has already rolled out targeted interventions to support struggling borrowers and prioritize lending to high-impact productive sectors, though the report notes these measures have had limited impact amid broader instability.

    Breaking down credit allocation by sector, the report shows the housing sector and industrial free zones are the largest recipients of bank lending, holding 5.269 billion gourdes and 5.082 billion gourdes in outstanding credit respectively. Together, these two segments account for more than half of all allocated private sector credit, at 26.6% and 25.7% of the total portfolio. Export-focused enterprises follow as the third-largest group, receiving 3.212 billion gourdes in financing equal to 16.2% of total disbursements, while the tourism and hotel sectors hold 2.440 billion gourdes, or 12.3% of total allocated credit.

    The agricultural sector, which benefits from special provisions outlined in BRH’s Circular 113, received 11.9% of total disbursements, and the government’s Real Estate Development Promotion Program (PPDI) accounts for an additional 5.3% of lending. Leasing-focused financial institutions round out the allocation, receiving 400 million gourdes, equal to 2% of total private sector credit.

    In its policy analysis, the BRH emphasizes that sustained growth in private sector lending will depend first on reversing the country’s security crisis. The report notes that improving public safety is a non-negotiable prerequisite to rebuild investor confidence, restart stalled productive activities, and revitalize traditional credit distribution channels. Restoring national stability, the central bank argues, would also lay the groundwork for a more supportive environment for financial innovation that could expand access to underserved groups. Beyond security, the report identifies the development of a robust, comprehensive financial risk management ecosystem as a critical priority to strengthen long-term resilience in Haiti’s banking sector.

    The full 18-page BRH report, published in French, is available for public download via the HaitiLibre official website.

  • Prime Minister Browne Champions Bold “Big Push” Agenda to Double the Size of Eastern Caribbean Economies

    Prime Minister Browne Champions Bold “Big Push” Agenda to Double the Size of Eastern Caribbean Economies

    Against a backdrop of persistent economic headwinds that have held back small island developing states across the Eastern Caribbean for decades, Prime Minister Browne has launched an ambitious, forward-thinking policy agenda dubbed the “Big Push” that aims to double the size of the sub-region’s collective economies over the coming decade.

    Speaking at a regional economic summit hosted in Antigua and Barbuda, Browne, who also serves as chairman of the Organization of Eastern Caribbean States (OECS), framed the initiative as a transformative response to long-standing structural challenges, including heavy reliance on volatile tourism revenue, limited export diversification, chronic infrastructure gaps, and growing vulnerability to climate-related shocks. The agenda centers on five key pillars: targeted investment in renewable energy infrastructure to cut reliance on imported fossil fuels and reduce energy costs for businesses; expansion of the digital economy through improved broadband connectivity and support for tech entrepreneurship; deep integration of regional supply chains to cut cross-border trade costs; targeted investment in upskilling workforces for high-growth emerging sectors; and attracting sustainable foreign direct investment that prioritizes local job creation and community benefits.

    “For far too long, our economies have operated far below their potential, held back by fragmented markets and a dependence on sectors that leave us exposed to global shocks beyond our control,” Browne told attendees. “The Big Push is not just a set of policy proposals—it is a collective commitment to reimagine what our sub-region can achieve. Doubling our economic size will not happen overnight, but with coordinated regional action and aligned investment, it is well within our reach over the next 10 years.”

    Regional stakeholders have broadly welcomed the plan, with many noting that coordinated action is critical for small island economies that lack the scale to compete globally on their own. International financial institutions have also signaled preliminary interest in partnering with the OECS to fund key infrastructure projects outlined in the agenda, though some economists have warned that delivering on the bold target will require consistent policy implementation across member states and strong safeguards to ensure inclusive growth that benefits marginalized communities, rather than just a small segment of the population.

    The initiative comes as Eastern Caribbean economies continue to recover from the devastating economic impact of the COVID-19 pandemic, which collapsed tourism revenue and pushed thousands out of work between 2020 and 2022. Browne emphasized that the “Big Push” will prioritize building more resilient, diversified economies that are better able to withstand future global and climate shocks, rather than simply returning to pre-pandemic growth patterns.

  • Ferry plan must prioritise cargo to be viable, economist says

    Ferry plan must prioritise cargo to be viable, economist says

    As Caribbean Community (CARICOM) leaders prepare to launch a proof-of-concept trial for a new regional ferry service in the coming months, one prominent regional economist is laying out a clear roadmap to avoid the financial pitfalls that sank past regional transport initiatives.

    Jeremy Stephen, an economist with dual experience as a pilot and aviation industry consultant, has thrown his support behind the ambitious intra-regional connectivity project — but only if planners prioritize cargo movement as the core revenue driver, with passenger service taking a secondary role. He argues that this cargo-centric framework is the only path to long-term financial sustainability for the initiative, which aims to cut exorbitant regional trade costs, ease inflationary pressures amplified by global fuel price volatility, and strengthen regional food security.

    “It was very clear that there’s a momentum towards cargo, and from the time that happens, I support it,” Stephen told local outlet Barbados TODAY. “If it’s just driven on cargo, I think it’s way more manageable.”

    To kickstart the project while private sector partners pursue long-term vessel acquisitions, CARICOM will deploy the Galleons Passage, a 74-meter roll-on/roll-off catamaran ferry owned by the government of Trinidad and Tobago. The vessel can accommodate up to 60 vehicles, 400 passengers, and holds substantial space for bulk freight. The initial trial route will link key markets across the southern and eastern Caribbean, connecting Trinidad and Tobago, Guyana, Suriname, St. Vincent and the Grenadines, and Barbados.

    Stephen notes that informal commercial maritime traffic already flows regularly through these corridors, operating below the public radar through existing private merchant networks. “If you download the marine traffic app, you can see there’s traffic moving between Barbados and Saint Vincent every Wednesday for sure — massive shipments of stuff, including coconuts. A lot of people just don’t know this,” he explained. “The issue has always been that nobody has invested in large-scale infrastructure to handle consistent movement between Trinidad and Tobago, the Organisation of Eastern Caribbean States (OECS) and Barbados.”

    To keep service affordable for small-scale traders and vulnerable communities without becoming a permanent drain on regional public finances, CARICOM leaders have tasked the CARICOM Private Sector Organisation (CPSO) and the CARICOM Secretariat with finalizing a detailed financial plan. Stephen says the project’s math only adds up if planners adopt a chain-link transshipment (or “ring topology”) model, rather than relying on simple point-to-point deliveries. “In other words, start in Grenada, pick up some spices, go to Saint Vincent, pick up some stuff, drop off a little bit of stuff, and then transship all the way through to say, Barbados,” he explained. “Only if there’s a transshipment model attached can it make money, especially if the vessels are young enough.”

    Here Stephen raises a critical red flag, drawing a direct parallel to the 2020 collapse of regional carrier LIAT, which collapsed under unsustainable operating costs. He warns that vessel age and maintenance reliability pose the same existential threat to the ferry project. “The issue really comes down to age,” Stephen warned. “Outside of productivity, the issue with LIAT was the average age of the ATR aircraft they had at the time, the carrying costs, and the routes that were unprofitable. Those three components pretty much led to a situation where regional governments had to end up pulling from their pockets.”

    The Galleons Passage, commissioned in 2018, is among a fleet of Trinidad and Tobago government-owned vessels infamous for extended maintenance downtime, Stephen says. “If the vessels are not young enough, it doesn’t matter, because it might spend more time down… and that might not necessarily assist the exercise in a meaningful manner. You also have to ensure the right health and regulatory concerns are baked into the model—you don’t want to be mixing certain spoilages with live chickens, for example.”

    Even with a well-designed route and a reliable fleet, Stephen cautions that outdated, rigid port and customs bureaucracies across the region could still erase the ferry’s potential economic benefits. While Barbados Prime Minister Mia Mottley has called for urgent harmonization of regional customs, licensing, and insurance frameworks within three months, Stephen says the reform needs to go deeper to change entrenched operational cultures, particularly in Barbados.

    “It makes no sense providing cheaper shipments if the ability to clear them still remains the same,” Stephen said. “The culture of customs, at least in Barbados, is one that fights certain reforms. The longer a ship waits just to offload due to issues pertaining to customs, it adds expenses you don’t want—port fees, docking fees, and all that nonsense. Those are the costs that end up eating into any headway or profit.”

    He added that inflexible port operating hours, which prioritize rigid schedules over seamless trade flow, already deter international air carriers from routing heavy freight through Barbados, and the same flaw would harm the ferry project. “You can’t clear anything at the airport past four o’clock. Nobody likes to bring any cargo late. If you have rolling schedules both at the seaport and the airport, then this thing becomes a cheaper exercise. Customs reforms must help this to work.”

    With Trinidad and Tobago providing its state-owned vessel for the free trial, Stephen questions whether the pilot will obscure the project’s true commercial risks, noting that Port of Spain has a long history of heavy subsidization for its domestic sea bridge and regional air links via state-owned Caribbean Airlines. To prevent historical political tensions from resurfacing, Stephen says all regional partners must contribute their fair share of costs.

    Instead of wasting public funds on subsidizing daily operating costs, Stephen urges CARICOM governments to redirect public support toward structural upstream investments that will reduce long-term costs and shield the project from inflationary shocks. His top recommendation: bulk purchasing and centralized storage of maintenance parts, which are notoriously expensive to source in the Caribbean. “I think they should subsidise, to be honest, not operating costs, but a parts store,” he said. “Sourcing parts in the Caribbean is incredibly expensive. If you wait until the last minute, you pay an inflationary premium. If governments spend their subsidies on upfront parts acquisition and storage, and if they focus on subsidising the actual exports to incentivise traders, the region will see a far more meaningful return as economies pick up and trade revenues rise.”

  • Remittances to Dominican Republic top US$6.2 billion through June

    Remittances to Dominican Republic top US$6.2 billion through June

    Santo Domingo – The Dominican Republic has recorded solid growth in cross-border remittance inflows for the opening half of 2026, defying widespread global economic uncertainty to hit a new half-year milestone, new data from the Central Bank of the Dominican Republic (BCRD) confirms.

    According to the BCRD’s latest balance of payments report, total remittances received between January and June 2026 reached more than $6.219 billion, representing a 6.7% year-over-year increase compared to the same six-month period in 2025. Growth accelerated notably through the second quarter, with June alone seeing inflows hit $1.049 billion – a 13.6% annual jump that outpaced the 10.6% growth recorded in May.

    The central bank highlighted that this resilient growth is particularly notable against a backdrop of persistent global economic challenges. Geopolitical tensions across the Middle East have driven up global crude oil prices, kept broad inflationary pressures elevated in most major economies, and eroded household disposable purchasing power for Dominican expatriates across the globe. Even with these headwinds, remittance flows – a core pillar of the Dominican Republic’s external economy – have continued to expand at a steady pace.

    Geographically, the United States remains the dominant source of formal remittance flows to the country. In June, 81.4% of all formal transfers originated from the U.S., totaling $780.7 million. Spain took second place, contributing $61.8 million, equal to 6.4% of June’s total remittances. Italy followed with 1.3% of total inflows, while Haiti and Switzerland each accounted for 1.2% respectively. Smaller but consistent remittance flows also arrived from other European and North American economies including France, Canada, and Germany.