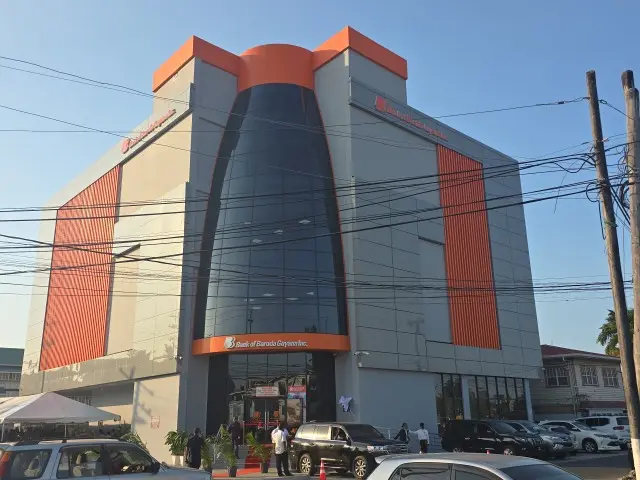
GEORGETOWN, GUYANA – Nov 6, 2026: Just six years after Bank of Baroda, the India-headquartered global commercial lender, was on the verge of winding down its entire Guyana footprint, the institution is celebrating unprecedented financial milestones alongside the official inauguration of its purpose-built new headquarters at the intersection of Carmichael and Quamina Streets in central Georgetown.
Addressing attendees at the opening ceremony, Bank of Baroda Global Managing Director and CEO Debedatta Chand laid out staggering performance metrics that underscore the bank’s dramatic local turnaround: total aggregate business volume has surged from GY$28.7 billion in the 2022-23 fiscal year to more than GY$51.2 billion in 2025-26, marking a nearly 29% year-over-year growth rate for the latest reporting period. Local deposit volumes climbed over 31%, while outstanding loans and advances expanded by more than 22%, driving net profit to GY$774 million for the latest fiscal cycle. Most notably, the bank has executed a striking overhaul of its loan portfolio health, slashing non-performing assets from GY$314 million to a mere GY$38 million, a 87.9% reduction in bad debt over the period.
Guyana’s President Dr Irfaan Ali, who delivered keynote remarks at the event, recalled the pivotal 2020 negotiation that altered the bank’s trajectory in the country: shortly after securing victory in that year’s general and regional elections, he was informed Bank of Baroda intended to fully exit the Guyanese market, a decision he worked actively to reverse. “I could not be more elated to stand here today launching this state-of-the-art new headquarters with all of you, compared to that day in 2020 when we sat across the table discussing your planned withdrawal from our economy – this is a night and day difference,” Ali told the audience.
The head of state went on to challenge Bank of Baroda to deploy a larger share of its global parent capital to tap into Guyana’s robust, low-risk lending landscape, where official central bank data shows national non-performing loan ratios have fallen to just 1.3% of total outstanding credit. “This statistic is a powerful signal of three critical strengths: the high overall quality of lending across our financial sector, the strong repayment capacity of Guyanese borrowers, and the remarkable resilience of our entire financial system, paired with sustained, broad-based credit expansion,” Ali explained. He cited latest macroeconomic data showing private sector credit grew 19% year-over-year in 2025, while the first six months of 2026 delivered 15.5% total domestic credit growth, 11.5% expansion in private sector lending, a 21.2% jump in real estate mortgage disbursements, and 8.1% growth in loans to service sector businesses. Ali emphasized these gains are not inflated by low base effects, but represent consistent, accelerating growth across successive reporting cycles.
Chand, who expressed unbridled optimism about Guyana’s ongoing economic transformation, noted the country’s fast-expanding oil and gas sector, paired with targeted public and private investments in infrastructure, agriculture, renewable energy, and small and medium-sized enterprises, has unlocked unprecedented cross-sector opportunities for local financial institutions. “We see enormous untapped potential for the banking industry to serve as a core engine driving this national transformation, and Bank of Baroda is fully committed to being a leading, active participant in Guyana’s high-growth economic story,” he stated. The CEO outlined upcoming plans to expand the bank’s local product suite, including major upgrades to digital, mobile and internet banking platforms, enhanced card services, expanded trade finance offerings, streamlined cross-border remittance services, and more accessible payment solutions tailored to the unique needs of Guyanese individual customers and domestic businesses. Chand noted the new, spacious, customer-centric headquarters is far more than a symbolic real estate upgrade: it is designed to cut operational friction, deliver a more professional work environment for local staff, and scale the bank’s service capacity to match the fast-growing demands of Guyana’s expanding economy. The event was also attended by Guyana’s Finance Minister Dr Ashni Singh, Bank of Baroda (Guyana) Inc. Chairman Nishant Rajan, and local subsidiary Managing Director Mohit Bakuni.
Bank of Baroda records financial successes after mulling closure