After a decade of advocacy and preparation, Barbados’ largest credit union is poised to expand its lending footprint, buoyed by newly passed legislation that brings state-backed deposit protection to the cooperative financial sector for the first time.
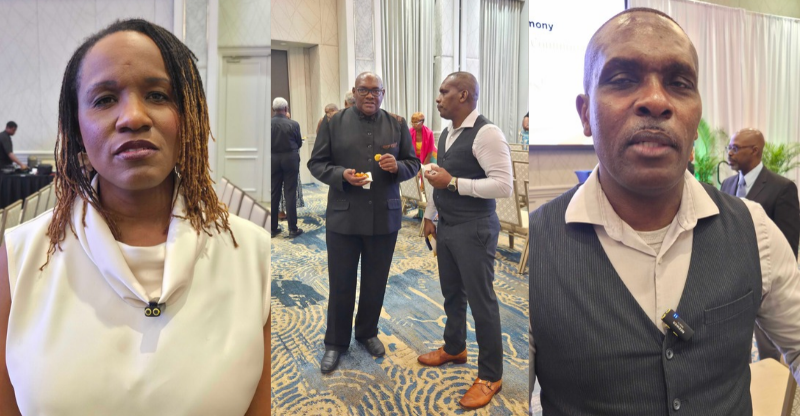
The Barbados Public Workers’ Co-operative Credit Union Limited (BPWCCUL) has publicly praised the recent passage of the Protection of Depositors Act, a policy shift that leaders say will erase the long-held competitive advantage commercial banks have enjoyed in the local financial market. In an exclusive interview with local outlet Barbados TODAY, Group Chief Executive Officer LeVere Catlyn and Chief Operations Officer Corinne Clarke laid out what this regulatory change means for the institution, its 1000s of members, and the wider Barbadian cooperative movement.
For generations, commercial banks in Barbados have operated with the security of legally mandated government-backed deposit insurance, a benefit that credit unions were never able to offer their own customers. This gap created a persistent market imbalance: many savers chose traditional banks over credit unions out of concern for deposit security, even when credit unions offered more favorable rates. Catlyn noted that this disparity has been a top priority for the sector for many years, and the new law finally closes that gap.
“This journey has been roughly a decade in the making,” Catlyn explained. “We saw this change coming years ago, and we proactively set aside $260,000 to help cover the transition costs, even though we know the total expense will ultimately be higher. For years, our members have asked for this protection, and it’s a milestone to finally deliver it.”
Under the new regulatory framework, individual member deposits will be insured up to a threshold of $25,000. That coverage offers critical peace of mind for savers at a time of ongoing global economic uncertainty, Catlyn said, putting credit unions on equal footing with commercial banks as a secure home for consumers’ primary savings. Beyond the direct benefit to BPWCCUL’s own membership, the change also lifts up smaller credit unions across the island. Catlyn explained that BPWCCUL has long served as a stabilizing force for the Barbadian cooperative sector, stepping in to merge with and absorb smaller institutions that face insurmountable financial challenges. Now, all members of those absorbed institutions will automatically gain access to the same state-backed deposit protection that BPWCCUL can offer.
Alongside the new deposit insurance regime, Catlyn confirmed that policymakers are also developing a dedicated bankruptcy and insolvency framework to streamline resolutions for failing financial institutions in the sector, a complementary reform that will further strengthen systemic stability.
When asked if the new legislation meets the sector’s expectations, Catlyn offered a cautiously optimistic assessment. “The bill meets the core baseline requirement of protecting our members, which was our top priority,” he said. “The one outstanding question is what the full long-term cost of this framework will be for our operational budget, and we won’t know that until the regulations are fully implemented.”
Beyond regulatory changes, BPWCCUL is also benefiting from a recent improvement in Barbados’ macroeconomic outlook. In its 2026 annual reporting, the credit union noted that Standard & Poor’s upgraded the rating of Barbados sovereign debt—where BPWCCUL holds large investments—from B- to B+ with a stable outlook. Catlyn explained that the upgrade does not change the institution’s day-to-day liquidity management, which is driven primarily by member deposits, but it has a major positive impact on the credit union’s balance sheet under current international financial reporting standards.
“Under modern IFRS rules, we have to set aside provisions for expected future losses on sovereign debt holdings, rather than just accounting for losses when they are incurred,” he explained. “When the government first defaulted and restructured its debt years ago, we were required to set aside roughly 23% of our total government debt holdings to cover expected credit losses. Now that the rating has been upgraded multiple times, that provisioning requirement has dropped substantially, freeing up capital that we can put to work for our members.”
With a strengthened balance sheet from lower loss provisions and the competitive boost from new deposit insurance, BPWCCUL is now shifting its strategy to grow its loan portfolio and deepen engagement with its membership. Clarke, the operations chief, said the credit union is targeting new, first-time borrowers who already hold savings accounts with the institution but currently borrow from other financial providers.
“For years, we have gradually opened up our lending practices to accept a broader range of member borrowers, as long as their risk profile aligns with our appetite,” Clarke said. “Right now, we have a lot of members who save with us but take out loans elsewhere. We want to change that. We’re rolling out more competitive credit products to encourage members to bring their entire financial portfolio under our cooperative framework, where it belongs. This new regulatory and economic landscape gives us the flexibility to reach those borrowers aggressively.”