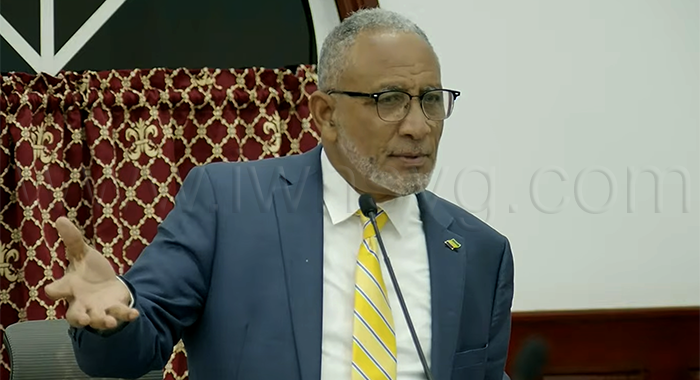
St. Vincent and the Grenadines’ Parliament has greenlit a sweeping set of amendments to the national Companies Act, a reform package Prime Minister Godwin Friday says will roll back overly harsh 2016 regulatory changes, boost the country’s investment appeal, and uphold the nation’s core economic interests. Introducing the Companies (Amendment) Bill 2026, Friday framed the new legislation as a targeted correction for unintended economic damage caused by the previous Unity Labour Party administration’s 2016 reform package.
According to Friday, the 2016 amendments imposed unreasonably restrictive requirements and crippling financial penalties on both domestic and foreign companies, particularly external firms seeking to invest in or own land within the country. He added that the former Ralph Gonsalves-led government brought the 2016 law to a parliamentary vote without meaningful consultation with business and industry stakeholders. Partial provisions of that 2016 law were already repealed in August, when parliament passed an earlier revision without opposition backing.
While Friday acknowledged that the 2016 reform was originally intended to strengthen regulatory oversight and curb documented abuses, he argued that its actual outcome was to impose onerous operational conditions on fully legitimate businesses, drive away much-needed foreign direct investment, and erode St. Vincent and the Grenadines (SVG)’s competitiveness in regional and global markets.
The new reforms form a core plank of the government’s broader economic strategy to leverage both domestic and foreign private capital to pull the country out of its ongoing debt crisis and expand inclusive economic opportunity for citizens. SVG currently carries EC$3.5 billion in public debt, equal to 113% of the country’s annual GDP, with 40 cents of every dollar of government revenue allocated to debt servicing. With public finances under severe strain, Friday noted that the state can no longer act as the primary driver of national economic growth. Instead, his administration’s policy prioritizes liberalizing private capital and building a supportive, attractive business environment across SVG.
“We are committed to stimulating growth in the private sector because it is only through growth in the productive sectors that we can really accelerate the development of our economy, grow our way out of the debt situation that we are in currently, and… provide opportunities for our people,” Friday told parliament. “The private sector is the engine of growth, not government. My administration is not here to compete against the private sector, whether it’s domestic or foreign, and we do not begrudge anybody making money — because if they don’t make money, they won’t invest.”
Linking the new bill to the pro-investment message he delivered during an official visit to Taiwan in August, Friday reaffirmed that “SVG is open for business.” He said the legislative changes are designed to send a clear, consistent signal to both domestic and global investors that the country welcomes credible investment, including from external companies seeking to own land or operate commercial activities within its borders.
A centerpiece of the 2016 amendments that the new reform targets was a tangled web of registration requirements that far outpaced reasonable regional standards. The most controversial rule mandated that not only must an external company that owns land in SVG register locally, every parent company shareholder in that firm’s ownership chain was also required to register as an external company in SVG — even if that shareholder entity had no actual business operations in the country beyond indirect ownership. By striking this requirement from the books, the new bill eliminates unnecessary red tape, cuts administrative burdens, and makes external corporate ownership of property and investment far more attractive to international players.
Friday explained that in practice, the 2016 rules led legal advisors to stop recommending corporate ownership structures for foreign investors, instead pushing individuals to hold land in their personal names. This limited the use of legitimate corporate investment vehicles and directly weakened SVG’s competitiveness as a Caribbean investment hub.
Even more damaging, Friday said, were the exorbitant fees and penalties the 2016 regime imposed that no other Caribbean jurisdiction charged, especially for firms that missed registration deadlines or failed to update corporate information on time. Under the original 2016 rules, an unregistered foreign company operating in SVG faced a fine of EC$350 per day for every day it remained unregistered — a penalty structure Friday called “outside the pale” of reasonable regulatory practice. Firms could quickly accumulate enormous penalty sums through no malicious intent, he noted, often due to administrative delays, poor advice, or simple tardiness, pushing accumulated penalties to levels that made investors question whether it was worth maintaining operations in SVG at all.
The 2026 reform replaces that daily penalty structure with a capped system: a EC$135 monthly fine with a total maximum penalty of roughly EC$27,000. Friday described the new structure as reasonable, arguing it will encourage voluntary compliance rather than driving companies away from the jurisdiction. Similarly, the original EC$100 daily penalty for late filing of updates to “fundamental changes” such as corporate name changes, director appointments, or revised corporate objectives will be replaced with a EC$50 monthly penalty, alongside extending the filing window from 30 to 60 days to accommodate the practical delays of cross-border document filing and certification. Friday emphasized that penalties are meant to encourage compliance, not generate government revenue, a core principle that guided the new penalty structure.
The bill also introduces a six-month amnesty program designed to regularize the status of companies that have accumulated unpaid late fees and penalties, replacing the previous opaque system of ad-hoc cabinet discretion with a transparent, equal-access framework open to all qualifying companies. Under the amnesty, both local and external companies with outstanding charges from late annual returns or fundamental change filings can settle their status by paying just 50% of their total accumulated debt, with that payment counted as full settlement. Companies that decline to take advantage of the amnesty will remain liable for 100% of their outstanding penalties and will not be eligible for future discretionary relief from cabinet.
Friday noted that the program will allow hundreds of companies that have fallen behind on filings — in some cases carrying hundreds of thousands of dollars in accumulated penalties — to return to good standing, resume operations, and contribute to SVG’s economic growth. The amnesty will also generate government revenue that would otherwise likely go uncollected, he said, noting “half a loaf is better than none.” At the same time, it clears debilitating legacy liabilities that have kept companies from expanding, hiring new employees, and operating as active contributors to local communities.
Friday stressed that the reforms do not amount to a regulatory free-for-all, nor do they abandon the rule of law. Instead, the changes are intentionally structured to be pro-business without sacrificing critical regulatory safeguards. “This is really… the environment in which we’re creating. There’s no hostility. There’s no seeking to be punitive. What we are wanting to do, we want business to do business. We want the country to free up. We want people to feel the country light again,” he said. The government will remain vigilant in upholding regulatory standards and protecting SVG’s national interests, he added, balancing pro-investment policy with the state’s responsibility to secure tax revenues, job growth, and broad economic benefits for citizens. The goal of regulation, he argued, should be to enable legitimate economic activity rather than smother it.
Not all lawmakers support the reforms, however. Opposition Leader Ralph Gonsalves, who led the previous administration that passed the 2016 amendments, has denounced the 2026 bill as “a bad bill.” He accused the current government of sacrificing critical public revenue and weakening regulatory safeguards to benefit non-compliant external companies and a small group of local lawyers who, he claims, failed to fulfill their professional duties to foreign clients. Gonsalves, a trained lawyer, argued that the reforms will disproportionately benefit non-compliant external companies that owe millions of dollars in accumulated penalties, as well as local attorneys who collected fees from clients but never completed required corporate filings. He also warned that the scale of fee reductions — which he calculates reach 98% to 99% in some cases — is arbitrary, illogical, and creates dangerous regulatory precedent.